

IRA Financial vs uDirect IRA
Both IRA Financial and uDirect IRA help investors take control of their retirement savings through Self-Directed IRAs and Solo 401(k) plans. Each provider offers access to a wide range of alternative investments, from real estate to private placements. uDirect IRA is known for straightforward, education-driven service, while IRA Financial combines that same breadth of investment access with checkbook control and a fully integrated technology platform.
Here’s how they compare across pricing, investment options, technology, and reputation.
Pricing & Fees: Transparent, Flat, and Investor-Friendly
Cost is often the first consideration for investors choosing a Self-Directed IRA provider. Both companies maintain flat, straightforward pricing that doesn’t scale with account value, but the transaction allowances differ in an important way.
IRA Financial | uDirect IRA | |
Setup Fee | $0 | $50 |
Annual Fee | $495 | $275 |
Asset Value Fee | $0 | $0 |
Investment Fee | $0 | $0 (6 free lifetime transactions) |
Roth Conversion Fee | $0 | $75 |
1 Year Total Cost | $495 | $325 |
5 Year Total Cost | $2,475 | $1,425 |
Pricing pulled from company website, as of the article publish date, based on 4 investments with a $200K total balance.
IRA Financial:
- Flat annual pricing: Self-Directed IRAs start at $495/year, with other plans available from $100/year
- No setup fee for custodian-controlled plans, and only a one-time establishment fee for Checkbook IRA structures
- Truly unlimited transactions at no additional cost, for the life of the account
- IRAfi Crypto platform offers low-cost trading for buying, selling, and managing crypto directly in the app
uDirect IRA:
- $50 setup fee, then a flat $275/year that doesn’t scale with account value
- Includes 6 free transactions, but only for the life of the account, not per year
- Once those 6 are used, each additional transaction (checks, wires, asset acquisitions) costs $10
- $75 Roth conversion fee
Summary
uDirect IRA’s lower flat fee makes it genuinely cheaper for investors who stay within their 6 lifetime free transactions, which is realistic for a buy-and-hold investor with a handful of assets. But that allowance doesn’t reset, ever, so an active investor who transacts more over the years will eventually pay per transaction, while IRA Financial’s flat fee includes unlimited transactions for as long as the account is open.
Winner: uDirect IRA (on price), IRA Financial (on predictability).
uDirect costs less upfront and annually, but its free-transaction allowance is fixed for the life of the account. IRA Financial costs more but never runs out of included transactions.
Investment Flexibility & Product Options
Both IRA Financial and uDirect IRA offer broad access to alternative investments, but the degree of investor control differs. IRA Financial provides direct checkbook control, while uDirect IRA follows a more traditional custodian-managed model.
IRA Financial | uDirect IRA | |
Account Type | ||
Self-Directed IRA | ||
Solo 401(k) | ||
HSA | ||
Checkbook Control | ||
ROBS Structure | ||
Platform & Investments | ||
Crypto Platform | ||
Stock Trading | ||
Compliance & Protection | ||
In-House Compliance & Tax Services | ||
IRS Audit Protection |
IRA Financial:
- Invest in real estate, private equity, notes, precious metals, crypto, and more
- Direct crypto investing through IRA Financial’s integrated platform
- Full checkbook control means no custodian pre-approval needed for investments
- Supports SEP, SIMPLE, HSA, Coverdell, traditional and Roth accounts, plus ROBS for business funding
- Solo 401(k) plan available with both traditional and Roth options
uDirect IRA:
- Offers Traditional, Roth, SEP, and SIMPLE IRAs, plus Solo 401(k) plans
- Supports checkbook control through an IRA-Owned LLC structure
- Permits investments in real estate, notes, private placements, precious metals, and crypto
- Crypto held through uDirect carries a 1% transaction fee plus a 1% monthly storage fee, notably higher-cost than IRA Financial’s integrated crypto platform
- No ROBS structure, HSA, or in-house compliance and audit protection services
Summary
Both providers give investors access to the same core alternative asset classes, and both support checkbook control through an LLC structure. IRA Financial goes further with HSA accounts, ROBS for business funding, and in-house compliance support, and its integrated crypto platform costs meaningfully less than uDirect’s 1% transaction and monthly storage fees.
Winner: IRA Financial
Broader account types, ROBS for business funding, in-house compliance support, and lower-cost crypto access that uDirect does not match.
Technology: Built for the Modern Investor
A streamlined, mobile-first experience helps investors stay connected to their retirement accounts. Here’s how IRA Financial and uDirect IRA compare in terms of technology and ease of use.
IRA Financial:
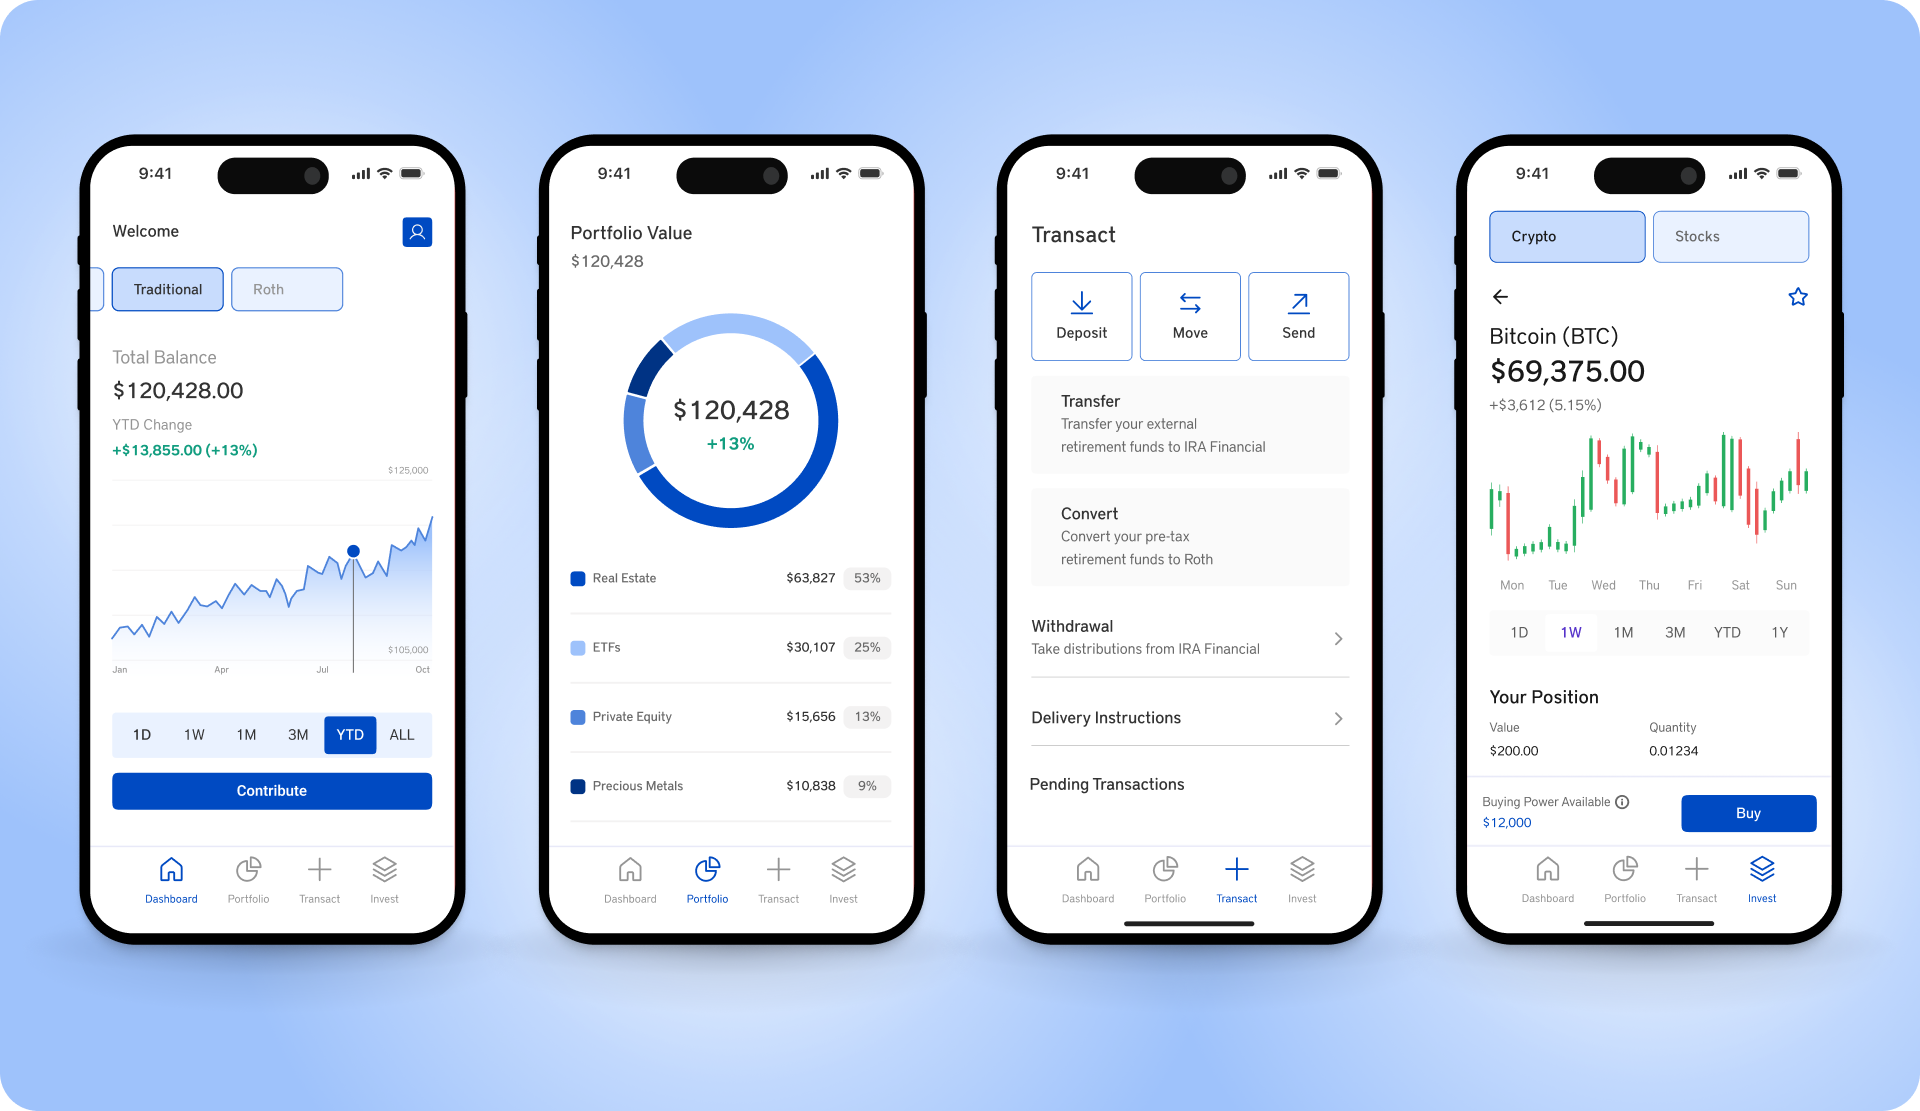
- Mobile app to open accounts, fund, invest, and manage your retirement plan
- Integrated dashboard for all investment types, including crypto and real estate
- Digital document uploads and e-signing streamline onboarding
uDirect IRA:
- Offers online account setup and secure document management
- Relies primarily on email and web portal communication for transactions
- No dedicated mobile app or in-app investment tools
Summary
uDirect IRA’s digital systems are reliable and secure, but geared toward administrative support rather than investor-driven management. IRA Financial’s app-based experience gives investors more direct, real-time control over their accounts.
Winner: IRA Financial.
A more modern, integrated platform built for today’s investors.
Reputation & Customer Reviews: Trusted by Thousands
Reputation plays a vital role when selecting a Self-Directed IRA provider. Both IRA Financial and uDirect IRA have earned respect for professionalism and investor education.
IRA Financial | uDirect IRA | |
Trustpilot | 4.8 / 5 | N/A |
4.3 / 5 | 4.6 / 5 |
IRA Financial:
- Strong reputation for fast account setup, responsive customer service, and straightforward pricing.
- Over 3,000 5-star reviews across Google, Trustpilot, and other platforms.
- Founded by tax attorney Adam Bergman, who educates investors via weekly videos, podcasts, and blog articles.
uDirect IRA:
- Strong Google rating with a meaningful review volume: 4.6/5 from 184 reviews
- Founded in 2009, with a long-standing focus on investor education
- No presence on Trustpilot to draw a comparison from
Summary
uDirect IRA’s Google reviews reflect a genuinely well-regarded, education-focused team. IRA Financial’s advantage comes from a strong, consistent presence across multiple major platforms rather than concentrated on one.
Winner: IRA Financial.
Strong reviews across multiple platforms, rather than a single review source.
The Bottom Line: Why IRA Financial Is the Smarter Choice
Both IRA Financial and uDirect IRA empower investors to diversify beyond traditional assets, and uDirect’s lower flat fee and education-first approach are real strengths for investors who plan to make very few transactions over the life of their account. But for investors who want unlimited transactions, broader account types, ROBS for business funding, and lower-cost integrated crypto access, IRA Financial offers more.
Book a free call with a self-directed retirement specialist
- Review your self-directed retirement options
- Learn about investing in alternative assets
- Get all of your questions answered

Related Articles
IRA Financial vs Inspira Financial
When it comes to self-directed retirement investing, IRA Financial and Inspira Financial (formerly Millennium Trust Company) take very different…

IRA Financial vs STRATA Trust Company
When choosing a self-directed retirement provider, investors often compare IRA Financial and STRATA Trust Company, two established names offering…
