

IRA Financial vs Inspira Financial
When it comes to self-directed retirement investing, IRA Financial and Inspira Financial (formerly Millennium Trust Company) take very different approaches. Inspira operates as a large-scale custodian focused on traditional oversight and compliance, while IRA Financial is designed for investors who want more hands-on control through a flexible, technology-driven platform.
In this comparison, we’ll break down how the two companies stack up across pricing, investment flexibility, technology, and reputation.
Pricing & Fees: Transparent, Flat, and Investor-Friendly
Fees can make or break your long-term returns. IRA Financial and Inspira Financial both charge administrative costs, but their structures are fundamentally different. IRA Financial offers flat, predictable pricing, while Inspira Financial’s fee scales with the number of alternative assets held.
IRA Financial | Inspira Financial | |
Setup Fee | $0 | $0 |
Annual Fee | $495 | $750 |
Asset Value Fee | $0 | $0 |
Investment Fee | $0 | $0 |
Roth Conversion Fee | $0 | $50 |
1 Year Total Cost | $495 | $750 |
5 Year Total Cost | $2,475 | $3,750 |
Pricing pulled from company website, as of the article publish date, based on 4 investments with a $200K total balance.
IRA Financial:
- IRA Financial offers flat, transparent annual fees starting at $495/year for a Self-Directed IRA, with other plans available starting as low as $100 annually.
- No asset-based fees, no transaction fees, and no hidden charges; what you see is what you pay.
- Their IRAfi Crypto platform offers low trading fees for buying, selling, and trading crypto through the integrated app.
Inspira Financial:
- No account setup fee
- $100 annual maintenance fee, plus an alternative asset holding fee that scales with the number of holdings: $350 for one, up to $650 for four or more
- No per-transaction purchase or sale fee for alternative assets
- $50 fee for Roth conversions or recharacterizations, plus a $150 per-asset re-registration fee if transferring assets out
Summary
Inspira’s fee structure is a flat annual maintenance fee plus a holding fee that increases with the number of alternative assets, but doesn’t scale further with account value or transaction activity. At 4 holdings, Inspira actually comes in slightly higher than IRA Financial in year one and stays higher every year after, since the holding fee doesn’t decrease even if account value is modest.
Winner: IRA Financial.
A single flat annual fee that’s lower than Inspira’s cost once 4 or more alternative assets are held.
Investment Flexibility & Product Options
Both IRA Financial and Inspira Financial let clients move beyond traditional investments, but they differ greatly in how investors access and control those assets. Inspira offers a strong custodial model, while IRA Financial provides true Checkbook Control and direct investing power.
IRA Financial | Inspira Financial | |
Account Type | ||
Self-Directed IRA | ||
Solo 401(k) | ||
HSA | ||
Checkbook Control | ||
ROBS Structure | ||
Platform & Investments | ||
Crypto Platform | ||
Stock Trading | ||
Compliance & Protection | ||
In-House Compliance & Tax Services | ||
IRS Audit Protection |
IRA Financial:
- Offers all the traditional SDIRA investments, including real estate, private lending, startups, precious metals, as well as direct crypto investing.
- Integrated platform for crypto, checkbook control, real estate, and more under one roof.
- Stock, ETF, bond, and options trading powered by Interactive Brokers – available as a $100/year add-on, fully integrated inside your IRA Financial account.
- Advanced structures like Solo 401(k) plans, SEP & SIMPLE IRAs, HSA & Coverdell accounts, and ROBS structures for business funding.
- IRA Compliance Shield ($299/year): in-house audit protection, tax consultation, deal reviews, prohibited transaction pre-clearance, and UBIT/UDFI modeling.
Inspira Financial:
- Account types limited to Traditional, Roth, SEP, and SIMPLE IRAs, no Solo 401(k) or Checkbook Control
- HSAs are offered as a separate consumer benefits product, not part of the Self-Directed IRA
- Supports alternative investments like hedge funds, private equity, real estate, and marketplace loans, plus direct stock, ETF, and mutual fund trading in the same account
- Custodian-based structure; every alternative investment requires Inspira’s approval before it’s processed
Summary
Inspira offers an impressive list of alternative investment options and even supports direct stock trading, a genuine strength. But every alternative asset transaction requires custodial approval, and Inspira doesn’t offer Checkbook Control, Solo 401(k), or ROBS. IRA Financial gives investors true independence through Checkbook Control, allowing quicker action and greater flexibility, along with broader account types.
Winner: IRA Financial
With Checkbook Control, Solo 401(k), and ROBS for business funding, IRA Financial offers more ways to structure and control your retirement investing.
Technology: Built for the Modern Investor
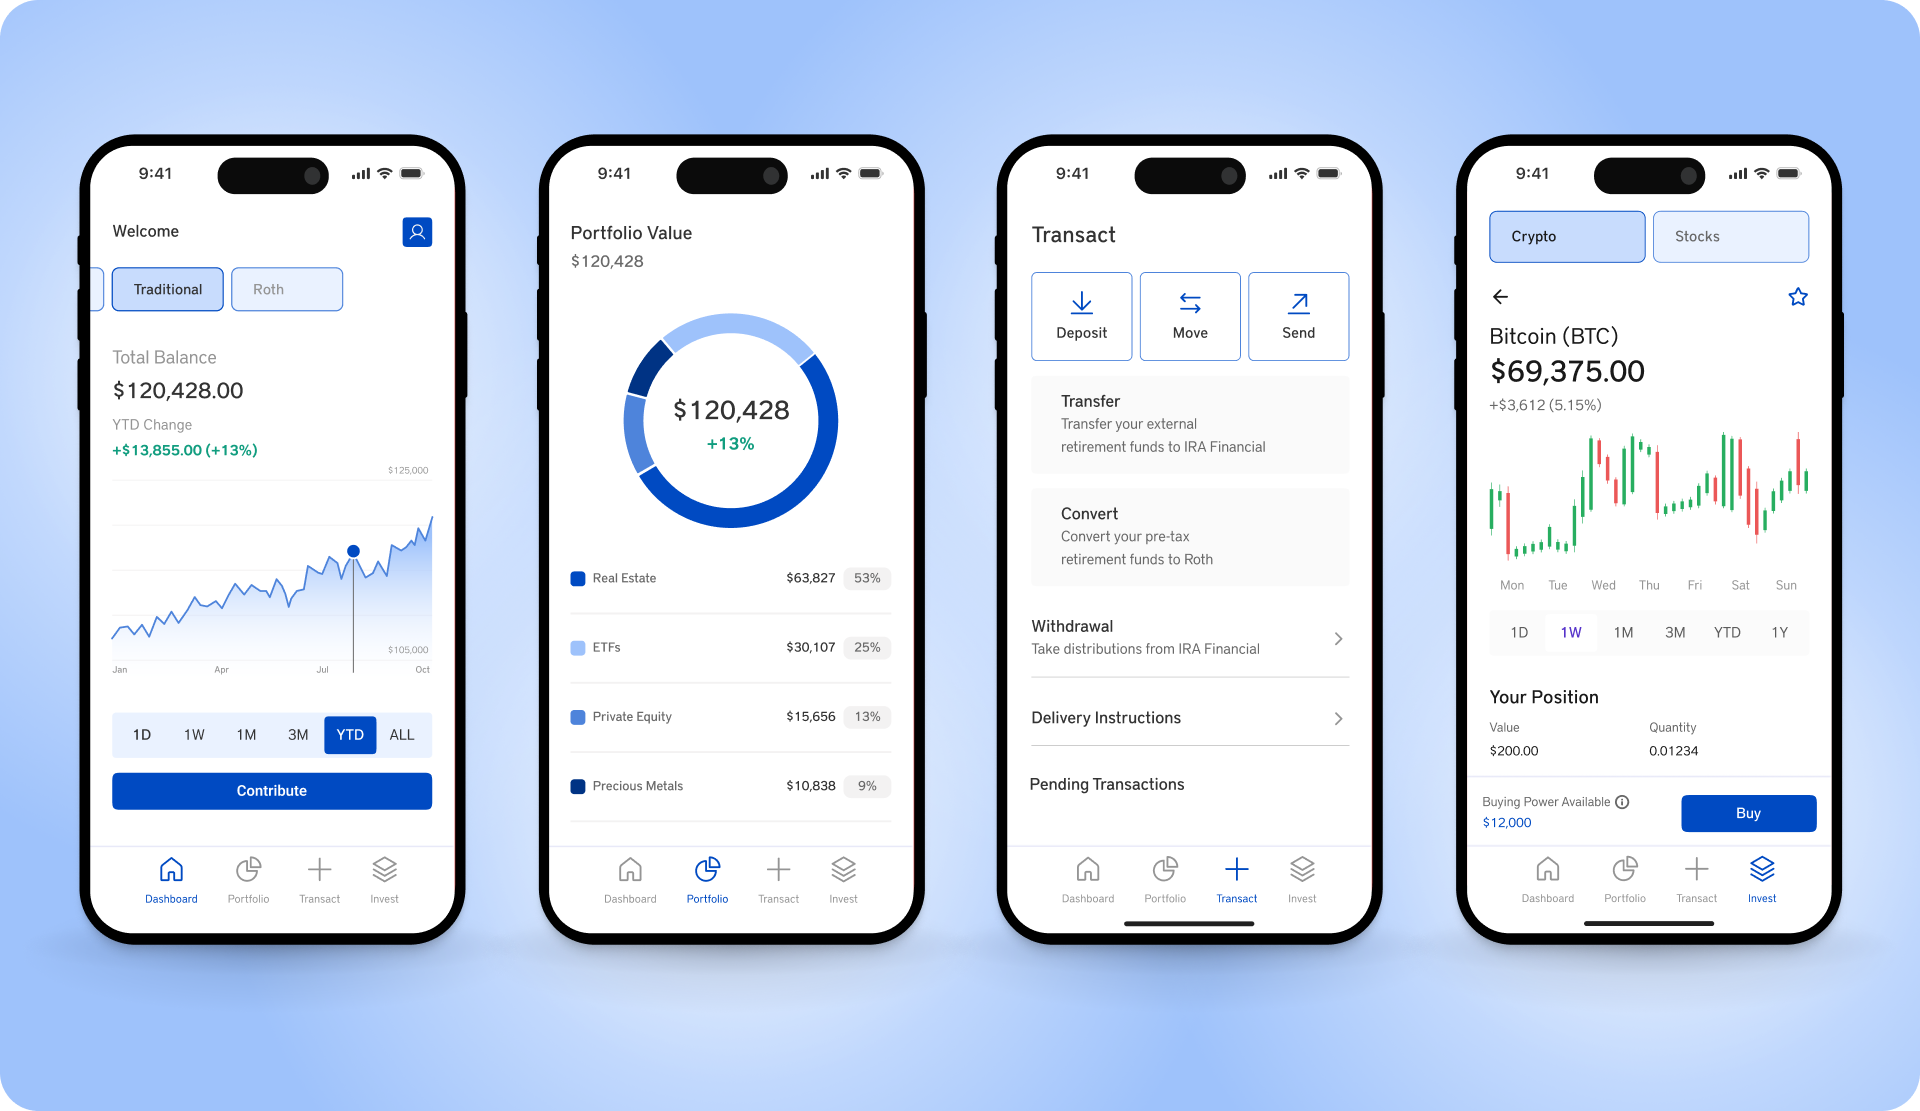
Today’s investors expect fast, seamless account management. IRA Financial’s technology-first approach delivers that with an integrated mobile app, while Inspira’s tools are built around traditional custodial workflows.
IRA Financial:
- Newly-updated mobile app and account dashboard with clean UI/UX and modern functionality.
- Offers a fully digital on-boarding experience, automated compliance, and secure document storage.
- In-house crypto trading, real-time dashboards, and checkbook control in a single portal.
Inspira Financial:
- Online account portal for clients and advisors
- Primarily focused on administrative tasks and reporting
- Limited functionality for direct alternative-asset investing or digital transactions
- More dependent on manual document processing and support requests
Summary
Inspira’s platform supports reliable account management but lacks the modern, investor-facing tools that make the process efficient. IRA Financial’s app-based system offers convenience, control, and speed, ideal for hands-on investors.
Winner: IRA Financial.
IRA Financial stands out for its integrated mobile platform, providing real-time access and digital management that Inspira’s traditional interface can’t match.
Reputation & Customer Reviews: Trusted by Thousands
Both IRA Financial and Inspira Financial have built strong reputations for serving investors nationwide. Inspira’s long-standing experience as a large custodian adds credibility, while IRA Financial stands out for its innovation, customer education, and accessibility.
IRA Financial | Inspira Financial | |
Trustpilot | 4.8 / 5 | 3.7 / 5 |
4.3 / 5 | 4.1 / 5 |
IRA Financial:
- Strong reputation for fast account setup, responsive customer service, and straightforward pricing.
- Over 3,000 5-star reviews across Google, Trustpilot, and other platforms.
- Founded by tax attorney Adam Bergman, who educates investors via weekly videos, podcasts, and blog articles.
Inspira Financial:
- Formerly Millennium Trust, with decades of custodial experience and a very large client base across retirement, health, and benefits accounts
- Solid Google rating at real scale: 4.1/5 from 1,180 reviews
- Some client feedback mentions slow turnaround times for investment approvals, transfers, and communication
Summary
Inspira’s Trustpilot sample size is enormous, but the 3.7/5 score reflects feedback across Inspira’s entire business, including consumer benefits accounts like HSAs and FSAs, not just its self-directed IRA product specifically. IRA Financial’s rating, while smaller in volume, is more concentrated and consistently high across platforms.
Winner: IRA Financial.
A higher, more consistent rating focused specifically on self-directed retirement services.
The Bottom Line: Why IRA Financial Is the Smarter Choice
Inspira Financial is a trusted name in custodial retirement services, offering extensive experience and a broad investment menu, including direct stock trading alongside alternative assets. However, IRA Financial delivers something different: greater freedom through Checkbook Control, broader account types like Solo 401(k) and ROBS, and a modern platform designed for investors who want full control over their retirement future.
Book a free call with a self-directed retirement specialist
- Review your self-directed retirement options
- Learn about investing in alternative assets
- Get all of your questions answered

Related Articles

IRA Financial vs STRATA Trust Company
When choosing a self-directed retirement provider, investors often compare IRA Financial and STRATA Trust Company, two established names offering…
IRA Financial vs uDirect IRA
Both IRA Financial and uDirect IRA help investors take control of their retirement savings through Self-Directed IRAs and Solo 401(k) plans. Each…
