


The Solo 401(k) Plan – Ultimate Retirement Plan for Truckers
According to the Americas Trucking Association, America's trucking industry is the lifeblood of the U.S. economy. In fact, nearly every good consumed in the U.S. is put on a truck at some point. As a result, "the trucking industry hauled 72.5% of all freight transported in the United States in 2019, equating to 11.84 billion tons."
- Truckers are the lifeblood of America
- Owner operator truckers have the most flexibility
- Independent truckers should consider the Solo 401(k) for their retirement savings
There is a growing trend in the trucking industry to hire truckers as independent contractors versus employees of the trucking company. In other words, truck drivers are frequently owner-operators of their own freelance trucking business and are therefore considered independent contractors. An owner-operator has the truck and has control over the type of trucking jobs it takes. Owner operator truckers are essentially free agent truckers who have greater control over their hauls and schedule.
Most trucking companies have an employment contract with their truckers that describes whether they are considered an employee or independent contractor. This classification is essential for IRS purposes, and each classification comes with its own benefits. The classification comes down to W2 Employees or 1099 Workers (independent contractors) for taxes and the IRS. Both of these represent two forms that relate to the earnings you make from your employment.
Advantages of Being an Independent Contractor
1099 independent contractors do not receive the same benefits as an employee, such as health care. Although, being classified as a 1099 worker has its own benefits. There are many advantages to working as an independent contractor, such as:
Work Flexibility
A 1099 independent contractor provides one with more flexibility with the type of work one does, as well as with work-life balance. An independent contractor can select the jobs they want to work on and how many hours they want to work. Basically, an independent trucker can work whenever they want, however many hours and days they want, and wherever you want.
Greater Earnings
As a 1099 worker, a trucker can get paid more than a W2 employee. An independent trucker may also have the ability to set their own prices and rates for each contract and delivery. A trucker that is operating as a 1099 independent contractor, is basically operating their own business rather than serving as an employee.
Superior Retirement Plan Options
One of the biggest advantages of being your own boss and choosing to be an owner operator trucker is that you can take advantage of one of the most powerful retirement tools available – the Solo 401k) plan.
A 401(k) Plan is an IRS approved qualified retirement plan. As the name suggests, the Solo 401(k) plan is an IRS-approved qualified 401(k) plan designed for a self-employed individual or the sole owner-employee of a corporation. Hence, any owner-operator trucker who is self-employed and does not have any employees that work more than 1000 hours annually, excluding a spouse or partner, can set-up a Solo 401(k) plan.
Why Should a Trucker Choose a Solo 401(k) Plan?
- Put away up to $67,500 a year in pretax or Roth. In 2022, the maximum one can contribute to an IRA is $6,000 (with a $1,000 additional “catch up” contribution for those age 50+). The Solo 401(k) annual contribution limit is $61,000, with an additional $6,500 catch-up contribution for those at least age 50. In addition, if your spouse generates compensation from the business, he or she can also make high contributions to the plan.
Based on the 2022 Solo 401(k) contribution rules, a plan participant under the age of 50 can make a maximum employee deferral contribution in the amount of $20,500. That amount can be made in pretax or Roth. On the profit-sharing side, the business can make a 25% (20% in the case of a sole proprietorship or single member LLC) profit sharing contribution up to the combined maximum for the year, including the employee deferral, of $61,000.
For plan participants who are at least age 50, an individual can make a maximum employee deferral contribution in the amount of $27,000. Again, that amount can be made in pretax or Roth funds. On the profit-sharing side, the business can make a 25% (20% in the case of a sole proprietorship or single member LLC) profit sharing contribution up to the combined maximum for the year, including the employee deferral, of $67,500.
- Borrow up to $50,000 tax-free for any purpose. An IRA, including the popular SEP IRA, does not allow one to borrow even one penny from the plan. However, assuming the plan documents allow for it, a Solo 401(k) participant can borrow up to $50,000 or 50% of their account value (whichever is less) for any purpose! The best part is the interest rate. The lowest interest rate is Prime for the loan, which is 5.50% as of August 30, 2022. This is way lower than any bank loan you may receive.
This offers a Solo 401(k) plan participant the ability to access up to $50,000 to use for any purpose, including paying personal debt or funding a business. In fact, you can use the loan to help buy a truck or even finance your trucking business. Best of all, the loan option will allow you to have tax- and penalty-free use of the funds, and the loan payments go back to your plan instead of a bank or a credit card company. Hence, you can use your 401(k) funds for personal or business purposes and instead of paying back a with credit card company you are paying your plan back, with interest.
- Self-Directed investment options. IRA Financial is one of the few companies that offer Solo 401(k) plans with self-directed investment options, including real estate, private placements, precious metals, cryptocurrency, tax liens, investment funds, private business investments, and much more. The Internal Revenue Code does not describe what a Solo 401(k) can invest in, only what it cannot invest in. Code Sections 408 & 4975 prohibits Disqualified Persons from engaging in certain types of transactions. In general, if the self-directed Solo 401(k) does not purchase collectibles or engage in a prohibited transaction outlined in Code Section 4975, then the investment can be made!
Having the ability to invest in alternative asset investments with a Solo 401(k) plan can provide truckers with the ability to better diversify their retirement assets as well gain the opportunity to invest in a wide variety of investments. Best of all, all income and gains generated by the Solo 401(k) plan will go back to the plan without tax. This is known as tax-deferral.
- Use leverage to buy real estate with no tax. For truckers that are interested in using a retirement funds to invest in real estate, the Solo 401(k) plan offers participants the ability to invest in real estate and use a non-recourse loan without triggering the Unrelated Debt Financed Income (UDFI) tax. UDFI is a type of Unrelated Business Taxable Income (UBTI) which, if triggered, could subject the investment to close to a 37% tax for 2022 when using an IRA.
However, a Solo 401(k) plan using nonrecourse financing for a real estate investment is exempt from the UDFI tax (Internal Revenue Code Section 514(c)(9).
Conclusion
Being an owner operator trucker has so many financial and work-life benefits. In addition, being a self-employed trucker allows one to take advantage of the most powerful retirement plan – the Solo 401(k). With a Solo 401k), an owner-operator trucker can maximize his or her tax deductions, while at the same time gaining investment diversification, as well as the ability to borrow up to $50,000 to use for any purpose, including starting or financing a trucking business.

Solo 401(k) Contribution Limits and How to Maximize Your Savings
Solo 401k Contributions for 2026
Starting a Solo 401(k) plan in 2026 has even more benefits than it did in years prior. The Solo 401(k) plan is designed specifically for self-employed individuals or small business owners with no full-time employees other than the owner(s) and their spouse(s). There are many features of the plan that make it so appealing and popular among self-employed business owners. However, the ability to make high annual maximum contributions is probably the most popular Solo 401(k) plan feature.
Solo 401k plans are designed for entrepreneurs, contract workers and the self-employed who have no employees other than a spouse, and there can be big benefits to using this type of plan. Participants can self-direct their money and investments, there are generous contribution limits, and there are minimal tax filing requirements. It offers all of the benefits of a traditional plan as well as some additional benefits. The generous contribution opportunities are what will be discussed herein.
Maximum Solo 401(k) Plan Contribution
In general, a Solo 401(k) plan consists of two components: (i) employee deferrals and (ii) employer profit sharing contributions. First, there is the elective deferral which is the contribution you make as the employee. The second type of contribution for a Solo 401(k) is the employer contribution, which is a percentage of your self-employment income or your schedule C if you’re a single member LLC or sole proprietor.
For 2026, the maximum aggregate Solo 401(k) contribution, including employee deferrals and employer profit-sharing contributions, is $72,000 for individuals under age 50, and $80,000 for those age 50 or older. For participants between ages 60 and 63, the maximum contribution can be as high as $83,250.
Two Types of Solo 401k Contributions
As the employee, you can contribute $24,500 if you are under age 50, or $32,500 if you are 50 or older in 2026. This contribution can be made on a pre-tax basis, up to 100% of your earned income.
Additionally, you can contribute up to 20% of your net self-employment income as the employer, which is also made with pre-tax dollars. Your contributions as both employer and employee can quickly add up.
Your Solo 401k limits apply per person, rather than by plan. So, it’s important to know your individual contributions. Some Solo 401k providers also offer a Roth 401k option, but this requires investment on an after-tax basis. Those would be tax-free in retirement.
Who Can Get Started?
If you generate some form of self-employment income, you can (and should) establish a Solo 401k plan. Even if that self-employment income is a side gig in conjunction with a regular 9-to-5, you qualify. Establishing a Solo 401k is a great way to maximize your retirement savings if you were late in getting started. It will also benefit investors who are uncomfortable making traditional investments.
Related: Solo 401(k) Investment Options
How to Get Started:
To establish a Solo 401k, set up an application with your Self-Directed 401k provider. You must have an Employee Identification Number (EIN). As you contribute more and more to your plan, you may need to fill out additional paperwork. Be aware of any fees a plan custodian may charge so you know what your true cost is, and then begin building your retirement savings for yourself.
Using 401k Funds to Start a Business
Many entrepreneurs are shocked to learn that the IRS allows you to use your former employer 401(k) funds or even your IRA funds to buy or start a business. Individuals can also use their 401k funds to invest their current businesses. This article will explore how you can use your 401k to fund or invest in a business with ROBS 401(k). The ROBS 401(k) structure will allow you to start or fund a business you can run, manage and even earn a salary from. If you are leaving your job or plan to leave your job and have a qualified 401(k) retirement plan, then the Rollover Business Start-Up Solution (ROBS) will likely be the most tax advantageous solution for you.
Can I Use 401(k) Funds to Start a Business?
This may come as a shock to some 401(k) plan participants, but a plan participant is not permitted to rollover current employer 401(k) funds to an IRA or another 401(k) plan unless there is a plan triggering event. The plan triggering rules essentially restrict a plan participant from rolling over 401(k) plan funds to another retirement plan or take a distribution, except for certain hardship exceptions, until they reach the age of 591⁄2, their job is terminated, or the plan is terminated. Hence, unless a plan participant can satisfy one of the plan triggering rules or specific exception, such as a hardship, he or she will likely not be able to use their 401(k) to start a business.
Read More: ROBS Solution for Entrepreneurs
ROBS 401(k)
The ROBS solution is basically the only way one can use retirement funds to invest in a business they will personally be involved in. Although a Self-Directed IRA allows one to make passive investments with retirement funds, it does not permit one to use IRA funds to invest in any business that the IRA holder or any disqualified person will personally be involved in, directly or indirectly. In other words, if one wants to use former employer 401(k) funds or IRA funds to buy or start a business that they or a family member (lineal descendant) will be personally involved in, the ROBS solution is essentially the only way to do it
Learn More: What is the Rollover as Business Startup Solution?
Schedule a Free Consultation
How to Use Your 401(k) Funds to Start a Business
The ROBS solution typically involves the following sequential steps:
1. A new or existing C Corporation is set-up or used. IRA Financial can assist with the set-up of the C Corporation.
2. The C Corporation adopts a prototype 401(k) plan from IRA Financial that specifically permits plan participants to direct the investment of their plan accounts into a selection of investment options, including employer stock, also known as “qualifying employer securities.”
3. The retirement account holder directs a rollover or trustee-to-trustee transfer of retirement funds from another qualified retirement plan into the newly adopted 401(k) plan. Note Roth IRA funds cannot be rolled into a 401(k) plan.
4. The 401(k)-plan trustee then directs the investment of his or her 401(k) plan account to purchase the C Corporation’s newly issued stock at fair market value (i.e., the amount that the entrepreneur wishes to invest in the new business).
5. The C Corporation utilizes the proceeds from the sale of stock to purchase an existing business or to begin a new venture.
Related: Top Businesses Using Rollover Businesses as Startups
Common Questions About Using Your 401k to Start a Business
IRA Financial Rollover Business Startup Solution
IRA Financial literally wrote the book on the ROBS Solution. Our founder, Adam Bergman, published the first book on the ROBS solution titled, “Turning Retirement Funds Into Start-Up Dreams”
IRA Financial has helped thousands of entrepreneurs and small business owners over the years use their retirement funds to start the business of their dreams or help build their existing business. The ROBS solution is the most tax advantageous way to use retirement funds in a tax and penalty free manner to start or fund a business. With the ROBS solution, you will not have to pay tax or even a 10% early distribution penalty on any IRA or 401(k) plan distribution. For example, if one is under the age of 591⁄2 and in the 25% income tax bracket, taking a taxable distribution of $100,000, would leave the individual with approximately $65,000, not including any state income tax. Whereas the ROBS solution would allow the individual to rollover the full $100,000 to start or fund a business without any tax or penalty.
Related: Rollover as Business Startup Compliancy Rules
Learn More
You can learn more about the ROBS solution by downloading the free IRA Financial Rollover for Business Startups info kit.
McNulty Case Reaffirms Physical Possession Rules
The recent court case, McNulty v. Commissioner has reaffirmed the physical possession rule. Although there hasn't been much guidance in the past, this case shows why you should not hold IRS-approved metals and coins personally. It's a clear violation of Internal Revenue Code Section 408(m). Here is what we know about the case.
McNulty Case - Summary
The McNultys established a Self-Directed IRA under I.R.C. sec. 408 and directed assets held in the IRA to invest in a single-member LLC. Ms. McNulty was the manager of the LLC that her IRA invested in. She directed it to purchase American Eagle coins and took physical possession of the coins. The IRS determined that the McNultys received taxable distributions equal to the cost of the coins in the year they received physical custody of them.
The Facts of the McNulty Case
In August 2015 Mrs. McNulty purchased services from Check Book IRA, LLC through its website, that included assistance in establishing a Self-Directed IRA. She then formed an LLC to which she would transfer IRA funds through purchases of membership interests. From there, she purchased American Eagle coins using IRA funds.
During 2015, Check Book’s website advertised that an LLC owned by an IRA could invest in the coins and IRA owners could hold the coins at their homes without tax consequences or penalties so long as the coins were “titled” to an LLC.
There are, in the record, no certificates of ownership for the coins or any other documentation that establishes legal title.
On August 19, 2015, Mrs. McNulty established a Self-Directed IRA using Check Book’s services and named Kingdom Trust Co. the IRA custodian. They are an independent qualified custodian under the Investment Advisers Act of 1940.
On August 24, 2015, Check Book formed Green Hill Holdings, LLC. Green Hill’s articles of organization, which were filed with the secretary of state of Rhode Island on August 25, 2015, state that Green Hill is a single-member LLC that is a disregarded entity for Federal tax purposes and its sole initial member was Mrs. McNulty’s IRA.
Petitioners were appointed Green Hill’s initial managers and were the managers during 2015 and 2016. Petitioners’ personal residence is Green Hill’s principal place of business. Green Hill opened a bank account over which petitioners had signatory authority.
During 2015 and 2016 Mr. McNulty used funds from his IRA to invest in a condominium and American Eagle coins through an LLC structure. Mrs. McNulty exercised sole control over her IRA’s investment decisions. She funded the IRA through direct transfers from two qualified retirement accounts: an individual retirement annuity and a 401(k) plan.
Mrs. McNulty instructed Kingdom Trust to use her IRA funds to purchase membership interests in Green Hill. The IRA purchased membership interests on three occasions during 2015 and 2016 (Green Hill investments). For each investment, Mrs. McNulty instructed Kingdom Trust to transfer the purchase price of the membership interests from the IRA to Green Hill’s bank account.
In turn, Mrs. McNulty, as the LLC’s manager, had Green Hill use almost all of the funds to purchase American Eagle coins from Miles Franklin, Ltd. The invoices from Miles Franklin list Green Hill as the purchaser. However, the shipping labels identified Mrs. McNulty, individually or along with her IRA, as the recipient of the shipments.
The coins were shipped to petitioners’ personal residence and were stored in a safe there along with coins purchased with funds from Mr. McNulty’s IRA and coins purchased by petitioners directly. The coins purchased with funds from Mrs. McNulty’s IRA, through Green Hill, were labeled as such.
The first Green Hill investment and coin purchase occurred in August through September 2015 with the funds transferred from the annuity. Mrs. McNulty instructed Kingdom Trust to purchase 375,000 membership units of Green Hill at $1 per unit for an investment of $375,000. The funds for the purchase were wired from the IRA to Green Hill’s bank account.
Mrs. McNulty then had Green Hill purchase 320 one-ounce American Eagle gold coins for $374,000 from Miles Franklin and that money was wired from Green Hill’s bank account to Miles Franklin. Miles Franklin shipped the coins to petitioners. residence, addressed to “Donna McNulty Green Hill”, where they were stored in the safe.
The second Green Hill investment and coin purchase occurred in late January through February 2016 with IRA funds that had been transferred from the 401(k). Mrs. McNulty instructed Kingdom Trust to purchase 43,274.70 membership units of Green Hill at $1 per unit for an investment of $43,274.70.
Kingdom Trust wired $43,274.70 from the IRA to Green Hill’s bank account. Mrs. McNulty had Green Hill use part of the funds to purchase 2,000 one-ounce American Eagle silver coins for $37,380, and the funds were wired from Green Hill’s bank account to Miles Franklin. Miles Franklin shipped the coins to petitioners’ residence, to “Green Hill * * * FBO Donna McNulty”, where they were stored in the safe.
In August 2016, Green Hill used $6,731 of the funds remaining in its bank account from the annuity and 401(k) transfers to purchase four one-ounce American Eagle gold coins, two one-quarter-ounce American Eagle gold coins, and one one-tenth-ounce American Eagle gold coin. A payment of $6,746 for the coins plus insured shipping was wired from Green Hill’s bank account to Miles Franklin.
Miles Franklin shipped the coins to “Donna McNulty” at petitioners’ residence, where they were stored in the safe.
Kingdom Trust filed Form 5498, IRA Contribution Information, with the IRS for 2015 and 2016, reporting the IRA’s fair market values of $349,856 and $388,247, respectively. The 2015 Form 5498 omitted Green Hill’s year-end bank account balance, and the 2016 Form omitted the value of the 2016 silver coins. Kingdom Trust did not have any role in the management of Green Hill, the purchase of the coins, or the administration of Green Hill’s assets or the IRA assets.
The above facts appear to have been discovered on audit of the taxpayer’s individual returns, though it is not clear how the details were uncovered.
Discussion
IRC section 408(m) generally prohibits the investment of assets of an IRA (and any self-directed qualified plan account) in certain “collectibles” including precious metals; however, there are exceptions for certain coins (American Eagle coins meet this exception) and bullion.
With respect to bullion, the exception applies “if such bullion is in the physical possession of a trustee [which is a bank or qualified non-bank custodian].” Some unscrupulous marketers have made false assertions that custody requirements do not apply to coins. However, based on the plain language of the text and legislative history, the court found that no such exception exists.
The surprising aspect of the Court’s opinion is how long it is. The Court simply needed to rule that holding the coins at home violated IRC 408(m). The facts were not at issue and holding coins at home in an IRA clearly violates IRC 408(m).
As stated:
“Independent oversight by a third-party fiduciary to track and monitor investment activities is one of the key aspects of the statutory scheme. When coins or bullion are in the physical possession of the IRA owner (in whatever capacity the owner may be acting), there is no independent oversight that could prevent the owner from invading her retirement funds. This lack of oversight is clearly inconsistent with the statutory scheme. Personal control over the IRA assets by the IRA owner is against the very nature of an IRA”
The Court focus on the taxpayer’s “control” of an IRA asset can have far reaching implications for Self-Directed IRA LLC clients beyond bullion coins.
In outlining its argument, the Court cites numerous cases confirming that an IRA can own an LLC and that the IRA owner is entitled to direct how his or her IRA assets are invested without forfeiting the tax benefits of an IRA. Though, the Court stated, “IRA owners cannot have unfettered command over the IRA assets without tax consequences. It is on the basis of Mrs. McNulty’s control over the AE coins that she had taxable IRA distributions.”
The use of the term “unfettered command” goes above and beyond the analysis of bullion coins and IRC 408(m) and could potentially be used in the framework of an IRA owning other alternative assets.
The McNulty case will not impact Self-Directed IRA LLC investors investing in most alternative assets, such as real estate, notes, private placements, investment funds, private businesses, since there is no potential for the IRA owner to have “unfettered control” over the underlying asset.
For example, Ancira v. Commissioner, 119 T.C. 135, 137-140 (2002), held that no taxable distribution occurred when the IRA owner personally received a check that he could not negotiate. The funds were then used to acquire stock, and the stock certificate was issued in the IRA’s name.
Furthermore, in McGaugh v. Commissioner, the court held that no taxable distribution occurred even if a stock certificate was in the IRA owner’s possession but it was issued in the IRA’s name and thus the owner could not realize any benefits from it and did not have constructive receipt of IRA assets.
In this case, Mrs. McNulty had complete, unfettered control over the American Eagle coins and was free to use them in any way she chose. This is true irrespective of Green Hill’s purported ownership of the coins and her status as Green Hill’s manager.
Once she received the coins, there were no limitations or restrictions on her use of them, even though she asserts on brief that she did not use them.
While an IRA owner may act as a conduit or agent of the IRA custodian, she may do so only as long as she is not in constructive or actual receipt of the IRA assets.
What About Cryptos?
However, in the case of digital assets, such as cryptocurrencies, holding the cryptos in a cold wallet that is controlled by the IRA owner would provide the IRA owner with “unfettered control” over the IRA asset even though IRC 408(m) does not apply to cryptos.
The majority of crypto investors tend to hold the cryptos on a licensed exchange, such as Bitstamp, which controls the private key and prevents the IRA owner from having constructive or actual receipt of the IRA owned cryptos. However, a number of clients wish to hold their IRA-owned cryptos on a cold wallet for security purposes.
A cold wallet can be detached from the internet. Hardware wallets and paper wallets are both cold wallet options. Hardware wallets use a physical medium — typically in the shape of a USB stick — to store the wallet’s private keys, making them de facto unreachable to hackers or other malicious parties.
Conclusion
The McNulty case should have been a very short and bland opinion since the facts concerning holding coins in an IRA at home so clearly violates IRC 408(m). Instead, the Court sought to focus on the criteria of “control” to determine whether an IRA owner holding assets in a Self-Directed IRA LLC triggered a taxable distribution.
The McNulty case will have very little impact on most Self-Directed IRA LLCs since case law is clear that holding stock certificates, deeds, and other forms of ownership documentation does not trigger a taxable distribution. However, in the case of digital assets, such as cryptocurrencies, held in a cold wallet off an exchange by the IRA holder directly, the opinion would seem to suggest that this could trigger a taxable distribution as the IRA owner would have “unfettered control” over the IRA owned cryptocurrencies.
The good news is that the majority of Crypto IRA clients hold their cryptos on a licensed and insured crypto exchange in the name of the IRA. For those IRA owners wishing to hold IRA-owned cryptos on a cold wallet off the exchange directly for security purposes, solutions exist, such as dual signatures, that allows the IRA owner to hold the cryptos on a cold wallet but without “unfettered control.”
How to Choose the Best Solo 401(k) Provider in 2026

I get asked some version of this question almost every week: which Solo 401(k) provider should I actually use? It's a fair question, because the market is crowded and the providers are not interchangeable. Some are custodians who will hold your paperwork and little else. Some are administrators who understand the plan documents but outsource everything else. And a few, including my firm, try to do the whole job in house. If you're comparing options, here's what actually separates a good Solo 401(k) provider from one that will cost you time, money, or a compliance headache down the road.
Key Takeaways
- A Solo 401(k) provider should give you real investment flexibility, not just access to stocks, bonds, and mutual funds.
- For 2026, Solo 401(k) participants can contribute up to $72,000 total, or $83,250 if you're between 60 and 63.
- Checkbook control lets you write a check and make an investment the same day, without waiting on custodian approval.
- Setup and annual fees for Solo 401(k) providers vary widely, from under $500 to well over $1,500 in the first year.
- The people drafting your plan documents should be tax attorneys or ERISA professionals, not a call center reading from a script.
What Is a Solo 401(k) Plan?
A Solo 401(k) is built for self-employed individuals and owner-only businesses, meaning you and, if applicable, your spouse are the only participants. It combines the high contribution limits of a traditional 401(k) with the investment freedom of a Self-Directed IRA, plus a couple of features neither one offers on its own: the ability to borrow from your own plan and, in most cases, a Roth option.
For 2026, the numbers look like this:
| Contribution Type | 2026 Limit |
|---|---|
| Employee deferral (under 50) | $24,500 |
| Catch-up contribution (age 50-59, and 64+) | $8,000 |
| Enhanced catch-up (age 60-63) | $11,250 |
| Total contribution (under 50) | $72,000 |
| Total contribution (age 50-59, and 64+) | $80,000 |
| Total contribution (age 60-63) | $83,250 |
That enhanced catch-up bracket for savers aged 60 to 63 is new under SECURE 2.0, and it's worth knowing about if you're in that window and trying to maximize what you put away in your final working years.
One more 2026 wrinkle: if you're 50 or older and your W-2 wages from your own business exceeded $150,000 in the prior year, your catch-up contributions have to go in as Roth, not pre-tax. That threshold is based on FICA wages from the same employer, so if your income comes mostly from self-employment on a Schedule C rather than a W-2 from an S-corp you run, it typically won't apply to you. It's a rule that trips up business owners who don't have a provider watching for it, and a good Solo 401(k) provider should be flagging it for you before it becomes a problem.
Look at the Investment Options It Allows
Not every Solo 401(k) is self-directed in practice. A lot of providers, especially the ones attached to a big brokerage or bank, will set up your plan and then hand you a menu of the same stocks, bonds, and mutual funds you could have bought anywhere. That's not a knock on those investments, but it defeats a lot of the reason people set up a Solo 401(k) in the first place. If you want to hold real estate, private equity, precious metals, or cryptocurrency inside your plan, confirm upfront that the provider actually supports it, and ask how the custody and reporting work in practice, not just whether it's technically allowed.
Check Whether the Provider Offers a Roth Solo 401(k)
A Roth Solo 401(k) lets you contribute after-tax dollars in exchange for tax-free qualified withdrawals once you've held the account at least five years and reached age 59½. Depending on your income and where you expect your tax rate to land in retirement, that trade can be worth a lot. Roth accounts also sidestep Required Minimum Distributions during your lifetime, which matters if you're trying to control your taxable income later in life. Not every provider offers a Roth option, and some that do offer it as an afterthought rather than a fully built-out feature, so ask specifically how their Roth Solo 401(k) is administered.
Make Sure Your Provider Actually Understands Tax Law
This is where I see people get burned the most. Setting up a Solo 401(k) isn't just filling out a form, it's establishing a qualified retirement plan governed by the IRS and ERISA. At some companies, the people drafting your plan documents aren't tax attorneys or even tax professionals. They're sales staff trained to process an application. That gap doesn't show up on day one. It shows up two or three years later, when you've made an investment the plan document didn't actually contemplate, or a loan that wasn't structured correctly, and now you're looking at a prohibited transaction. Ask directly who drafts and reviews your plan documents, and don't accept a vague answer.
Ask About the Loan Option
Most Solo 401(k) plans allow you to borrow from your own account for any reason, which is one of the more underused features of this structure. The rules are straightforward:
- Maximum loan amount: the lesser of $50,000 or 50% of your account balance
- Repayment: at least quarterly, over a term of up to five years, at the Prime interest rate
- No credit check, no bank underwriting: since you're borrowing from yourself, approval is fast and the interest you pay goes back into your own plan
Confirm your provider actually supports plan loans and can walk you through the documentation, since this is another area where a provider without in-house tax expertise tends to fall short.
Find Out Whether You Get Ongoing Support
A lot of providers are great at getting you set up and largely gone after that. The real test of a Solo 401(k) provider isn't the sign-up process, it's what happens in year two or three when you have a question about a new investment, a contribution calculation, or an IRS notice. Look for a provider with in-house staff who will still take your call once the account is open, not one that hands you off to a directory of outside accountants.
Confirm You'll Have Checkbook Control
Checkbook control means you can make an investment by writing a check or wiring funds directly, without asking a custodian to sign off first. That's a meaningful difference from a custodial-controlled plan, where every purchase or sale has to route through the custodian's approval process, sometimes adding days or weeks to a transaction. If speed and flexibility matter to your investment strategy, real estate deals in particular, confirm the provider's structure gives you actual checkbook control and not just marketing language that implies it.
Make Sure Plan Maintenance Isn't Outsourced
Some providers set up your plan and then refer every follow-up question to a third-party accountant or attorney they don't employ. That arrangement usually means slower answers, inconsistent advice, and an extra layer of cost. A provider with in-house professionals handling ongoing maintenance, including your annual IRS Form 5500-EZ where applicable, tends to give more consistent answers because the same team that built your plan is the one maintaining it.
Make Sure You Can Talk Directly to a Tax Professional
If your only point of contact is a salesperson or an account representative without specialized tax training, that's a problem waiting to happen. You want direct access to someone who actually understands 401(k) plan rules well enough to answer a real question, not read a script. That access is what prevents a lot of the prohibited transaction issues I see happen after the fact, when a client made a decision based on bad information from someone who wasn't qualified to give it.
Compare What You'll Actually Pay
Fees vary more across Solo 401(k) providers than most people expect, and the difference isn't always obvious until you're a year or two in. Here's how a few of the more commonly compared providers stack up as of this writing:
| Custodian | Setup | Application |
|---|---|---|
| IRA Financial | $999 | $0 |
| Equity Trust | $1,295 | $0 |
| MySolo401k | $650 | $0 |
| Nabers | $499 | $0 |
| Directed IRA | $595 | $0 |
| Rocket Dollar | $900 | $0 |
None of these providers charge an application fee, so the setup fee is really the number to compare. But it's not the whole picture either. Setup buys you the plan document itself, so before you decide based on price alone, ask what's actually included at that price, ongoing tax support, IRS Form 5500-EZ filing, loan document preparation, and Roth administration all vary by provider even when the upfront cost looks similar.
The IRA Financial Difference
I started IRA Financial in 2010 after spending a career as a tax attorney and running into this exact problem for a client: nobody could give her a straight answer about what she could actually do inside a Self-Directed IRA. I found the answer in the law library in about two hours, and it became clear the market needed a provider that treated this as tax law, not sales. That's still how we run the Solo 401(k) side of the business. Setup is $999 for the first year and $399 annually after that, and it includes your adoption agreement, basic plan document, trust agreement, loan documents, and free tax and ERISA support from our in-house team, not an outside referral. We work with more than 27,000 clients across all 50 states, and our team includes in-house tax attorneys and ERISA specialists who are the people you'll actually talk to if a question comes up.
Book a free call with a self-directed retirement specialist
- Review your self-directed retirement options
- Learn about investing in alternative assets
- Get all of your questions answered
Final Thoughts
None of this is complicated once you know what to look for, but it's easy to miss if you're comparing providers on price alone. Look at the investment flexibility, confirm the Roth and loan options actually exist rather than just being advertised, make sure checkbook control is real, and above all, make sure the people behind the plan understand tax law well enough to keep you out of trouble. Take the time to ask these questions before you sign up, not after, because a Solo 401(k) is a long-term relationship with whichever provider you choose, and the cheapest option upfront isn't always the one that saves you money over time.
This content is for educational purposes only and does not constitute legal, tax, or investment advice. Consult a qualified professional before making any investment decisions.
How to Transfer a SIMPLE IRA to a Self-Directed IRA
Self-Directed SIMPLE IRA
Individuals generally transfer IRA (individual retirement account) or rollover eligible qualified retirement plan assets into a Self-Directed IRA LLC structure. You can also roll over after-tax retirement funds to a Self-Directed SIMPLE IRA.
What is the Most Common Way to Fund a Self-Directed SIMPLE IRA?
Transfers and rollovers are types of transactions that allow the movement of assets between similar individual retirement accounts. For example, traditional IRA to Traditional IRA, including Savings incentive match plan for employees of small employers (SIMPLE). A SIMPLE IRA transfer is the most common method of funding a Self-Directed SIMPLE IRA LLC.
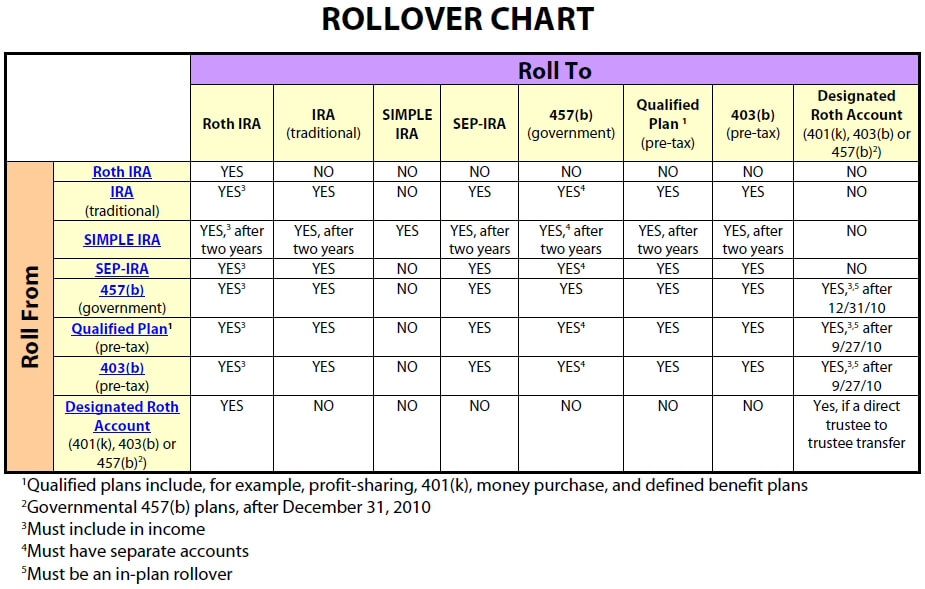
It's important to note that SIMPLE IRA assets may rolled over to a Self-Directed SIMPLE IRA anytime. However, SIMPLE IRA assets can roll over to a 401(k) qualified retirement plan, 403(b) plan, governmental 457(b) plan, or a Traditional IRA only after you meet a two (2) year waiting period. But a 401(k) qualified retirement plan, 403(b) plan, or governmental 457(b) plan may not roll into a SIMPLE IRA. Also, a Roth IRA cannot be rolled into a SIMPLE IRA.
Rollover Chart
Self-Directed SIMPLE IRA Transfers
A SIMPLE IRA-to SIMPLE IRA transfer is among the most common methods of moving assets from a SIMPLE IRA to a Self-Directed SIMPLE IRA. A transfer usually occurs between two separate financial organizations. However, a transfer can also occur between SIMPLE IRAs held at the same organization. When a SIMPLE IRA transfer is handled correctly, it's neither taxable nor reportable to the IRS (Internal Revenue Service). With a SIMPLE IRA transfer, the SIMPLE IRA holder directs the transfer, but doesn't actually receive the IRA assets. Instead, the transaction is completed by the distributing and receiving financial institutions.
In order for the SIMPLE IRA transfer to be tax-free and penalty-free, the IRA holder must not receive the SIMPLE IRA funds in a transfer. The check must be payable to the new individual retirement account custodian. Also, there is no reporting or withholding to the Internal Revenue Service on an IRA transfer.
The retirement tax professionals at the IRA Financial Group will help you fund your Self-Directed SIMPLE IRA LLC. They will transfer your current SIMPLE IRA funds to your new Self-Directed SIMPLE IRA structure. This is tax-free and penalty-free.
How the SIMPLE IRA to Self-Directed IRA Transfer Works?
The Self-Directed Simple IRA is rather simple. We assign you to a retirement tax professional who will help you establish a new Self-Directed SIMPLE IRA account. This occurs at a new FDIC and IRS approved IRA custodian. With your consent, the new custodian then requests the transfer of your SIMPLE IRA assets from your existing individual retirement account custodian. The IRA transfer is tax-free and penalty-free. Once the IRA funds are either transferred by wire or check tax-free to the new SIMPLE IRA custodian, the new custodian will invest the SIMPLE IRA assets into the new SIMPLE IRA LLC “checkbook control” structure. After the transfer of funds to the new SIMPLE IRA LLC, you, as manager of the SIMPLE IRA LLC, will have “checkbook control” over your retirement funds. This means you can make traditional as well as non-traditional investments tax-free and penalty-free.
60-Day Rollover Rule
You generally have 60 days from receipt of the eligible rollover distribution from a SIMPLE IRA account to roll the funds into a Self-Directed SIMPLE IRA LLC structure. The 60-day period starts when you receive the distribution. Usually, no exceptions apply to the 60-day time period. In cases where the 60-day period expires on a Saturday, Sunday, or legal holiday, you can perform the rollover on the following business day.
What happens if you receive the eligible rollover distribution? You may rollover the entire amount or any portion of the amount you receive. The amount of the eligible rollover distribution that you don't roll into an IRA is generally included in the individual’s gross income. It may be subject to a 10% early distribution penalty if the individual is under the age of 59 1/2.
How the 60-Day Rollover Works with a Self-Directed SIMPLE IRA
The retirement tax professionals at the IRA Financial Group will assist you in rolling over your 60-day eligible rollover distribution to a new FDIC and IRS approved IRA custodian. Once you deposit the 60-day eligible rollover distribution with the new IRA custodian within the 60-day period, the new custodian will be able to invest the SIMPLE IRA assets. You also have the option to establish a Self-Directed IRA LLC with “checkbook control.” If you decide to open a Self-Directed IRA LLC, you will have access to your funds once the transfer process is complete. With a Self-Directed IRA LLC, you, as manager of the SIMPLE IRA LLC, will have “checkbook control” over your retirement funds. You can make traditional as well as non-traditional investments tax-free and penalty-free.
Learn More:
Buying Stocks in a Self-Directed IRA
Solo 401k Contributions After 70 1/2
Solo 401k contributions after 70 1/2 are different than contributions at this age with an individual retirement account (IRA). With a traditional IRA, participants cannot make additional contributions once they reach 70 1/2 and are required to take out a minimum distribution (RMD). One of the benefits of the Solo 401k is that participants can still contribute after 70 1/2. In this article, we will explain exactly how this can be done.
Making Contributions to a Solo 401k Plan After 70 1/2
Unlike a Traditional IRA, which doesn't allow you to make pre-tax IRA contributions after reaching age 70 1/2, a solo 401(k) plan participant can make 401(k) plan contributions after age 70 1/2. In other words, if you're still an employer with a solo 401(k) retirement plan, you can continue making contributions to your employer-sponsored solo 401k or SEP IRA. Additionally, there's no requirement to take required minimum distributions (RMDs). This is only if you do not own 5% or more of the company.
This differs in the case of a solo 401k plan, also known as a self-employed 401(k) or individual 401(k) plan. If you satisfy the 5% threshold, it may prove difficult since most solo 401k plans are adopted by a sole business owner.
Roth IRA at 70 1/2
In addition, an individual may contribute directly to a Roth IRA after he or she has reached age 70 ½ (up to the annual $7,000 limit, which includes a $1,000 catch up amount). Direct Roth IRA contributions, however, are subject to income limitations. These limitations apply to reduce the contribution limits for taxpayers who earn more than $189,000 (married taxpayers) or $120,000 (single taxpayers) in 2018.
In sum, if you have a solo 401k plan and receive earned income from the business that adopted the plan, you may still make contributions to the plan after age 70 1/2. However, assuming you don’t own less than 5% of the company, you must continue to take RMDs on the value of your 401(k)-plan balance as of 12/31.
The annual RMD amount is generally around 3% of the fair market value of the 401(k) plan assets. The same rules apply to a SEP IRA. Whereas, in the case of a Roth IRA, contributions can be made after the age of 70 1/2. There will be no RMD requirements. This is because Roth IRAs don't have an RMD requirement. However, in the case of a pre-tax traditional IRA, no contributions can be made after the age of 70 1/2. The pre-tax IRA is subject to the RMD regime.
You can learn more about our services, including our solo 401k plan here.
Using an IRA to Buy a Home
In general, one is not able to purchase a home with a retirement account that they or a “disqualified person” will use. A retirement account, nevertheless, is able to invest in real estate as a passive investment but it cannot be used for any personal purpose. You do have options when using an IRA to buy a home.
- One can use his or her IRA funds to help purchase a home.
- There are tax implications on certain IRA distributions
- A 401(k) loan is another option if you have one available to you
Below are the most common options an IRA owner has when it comes to using their IRA to buy a home for personal use.
IRA Distributions
IRS rules allow one to take an IRA distribution anytime that can be used for any purpose. The IRS rules dictate that for traditional (pretax) IRAs, tax and a 10% early distribution penalty are due on any distributions taken prior to the age of 59 1/2. However, if a distribution is taken after the IRA owner reaches the age of 59 1/2, only income tax is due.
On the other hand, in the case of a Roth IRA, so long as one is over the age of 59 1/2 and any Roth IRA has been opened at least five years, then all Roth IRA distributions are tax-free. In addition, all Roth IRA contributions can be taken out at any point tax free.
Hence, a smart strategy would be to make Roth IRA contributions over a number of years and pull out the contributions if needed to buy a home tax-free and the remaining Roth funds (the appreciation on the contributions) can continue to grow tax free. This strategy allows one to save for retirement in a tax-free account as well as use the Roth contributions as a down payment for a home tax free.
Hardship Distribution
The IRS allows an IRA holder to take a one-time $10,000 hardship distribution for new homeowners from an IRA. The hardship distribution is still subject to tax, but the 10% early distribution penalty will be waived. This is a smart option for someone with a pretax IRA that needs extra funds for the purchase of a home as a first-time home buyer. Note – a 401(k) plan does not include a hardship distribution option.
What is considered a "first-time home buyer?" It's important to keep in mind that this doesn't have to be your first home purchase. So long as it's been at least two years since you last owned a house, you will qualify for the hardship distribution. One last thing to keep in mind is the $10,000 is a lifetime exception. Once you exhaust those funds, that's it. For example, you can use $5,000 for a home purchase, and then use the remaining $5,000 for a future purchase (assuming you qualify).
Learn More About Using an IRA to Invest in Real Estate
401(k) Loan
If an IRA owner also participates in a 401(k) plan and the plan offers a Solo 401(k) loan option, the plan participant has the opportunity to borrow the lesser of $50,000 of 50% of the account value. The loan proceeds can be used for any purpose, including for the purchase of a home. The loan is generally a five-year loan where payments are due at least quarterly at an interest rate of at least Prime. That rate stands at 5.50% as of August 30, 2022. Generally, you'll pay a point or two above the prime rate, however, that's much better than any loan you can get at a bank. In addition, some plans allow for the loan term to be greater than five years for the purchase of a home.
You must keep up with your loan repayments. Failure to do so will lead to the distributions of the amount not repaid. Those funds will be treated as taxable income and an early distribution penalty will apply if you are younger than 59 1/2. The benefit is that you repay the loan back to your 401(k) plan, including interest. Much better than giving that money to a bank or other lender!
Using an IRA to Buy a Home
Obviously, you probably cannot outright buy a home with your IRA funds, unless you have a large balance and can afford an even larger tax bill. However, using an IRA to buy a home may be attractive for some individuals. It's important to work with a financial planner to see how this may affect your future. Remember, any funds withdrawn from your IRA or 401(k) won't be working for you anymore. Withdrawing funds from your retirement savings should really only be a last resort. However, if it's your dream to be a homeowner, your IRA can help!
If you have any questions, please reach out to us @ 800.472.0646. We will be glad to explain how it works in greater detail. In fact, if you are reading this before June 22, 2021, IRA Financial President and CEO will be doing a YouTube Live all about real estate investing with retirement funds. The video will be on our YouTube channel as soon as it's done! Check it out!
Buying Dogecoin with a Self-Directed IRA or Solo 401(k)
Dogecoin gets treated like a joke by a lot of the financial world, and it started as one. But a meme coin with real trading volume and a real market cap is still a taxable event every time you buy, sell, or swap it, unless you hold it inside a retirement account. Buying Dogecoin through a Self-Directed IRA or Solo 401(k) doesn't change the coin's volatility, but it does change how the IRS treats every trade you make along the way. Here's how it actually works, and what to weigh before you do it.
Key Takeaways
- Crypto held in a retirement account isn't a taxable event on every trade. Gains grow tax-deferred in a traditional plan or tax-free in a Roth, instead of triggering short- or long-term capital gains each time you buy or sell.
- Buying Dogecoin outright, without margin or leverage, doesn't create Unrelated Business Taxable Income in either an IRA or a Solo 401(k). UBTI concerns only show up if you're trading on margin.
- Dogecoin peaked near $0.72 in May 2021 on Reddit and Elon Musk-fueled momentum. As of 2026 it trades for a small fraction of that, in the $0.08 to $0.09 range with roughly a $13 billion market cap, though it remains one of the most actively traded meme coins by volume.
- The self-employed generally get more room with a Solo 401(k), including a participant loan option up to the lesser of $50,000 or 50% of the vested balance. Everyone else uses a Self-Directed IRA.
- A meme coin should be a small slice of a diversified retirement portfolio, not the whole strategy.
Why Buy Dogecoin Inside a Retirement Account?
There are three real reasons to hold Dogecoin, or any cryptocurrency, in a retirement account instead of a personal brokerage or exchange account: the tax treatment, the diversification, and early access to a still-developing asset class. Dogecoin might be the coin you're interested in, but the same logic applies to the hundreds of other tokens available in a Self-Directed IRA.
Tax Treatment
The IRS has treated cryptocurrency as property, not currency, since Notice 2014-21, and that classification still governs how crypto gets taxed today. Outside a retirement account, that means every sale or swap is a capital gains event: short-term if you held it under a year, long-term if you held it longer, and you're on the hook for tracking cost basis and holding periods on every transaction.
Inside a Self-Directed IRA or Solo 401(k), none of that applies while the funds stay in the plan. A traditional account defers tax until you take distributions in retirement. A Roth account is funded with after-tax money, but qualified distributions, meaning you're at least 59½ and the account has been open five years, come out completely tax free. Either way, you can buy, sell, and trade Dogecoin inside the account without generating a capital gains bill along the way.
Diversification
Concentrating a retirement account in one volatile asset is a bad idea no matter what that asset is. Spreading exposure across stocks, bonds, real estate, precious metals, and a measured allocation to crypto lets a portfolio absorb a bad stretch in any one asset class without taking down the whole account. Dogecoin has had some of the widest price swings of any actively traded crypto asset, which is exactly why it belongs in a diversified mix rather than as the whole strategy.
Getting In Early on an Emerging Asset Class
Crypto as an asset class is still young relative to stocks or real estate, and the underlying blockchain technology keeps evolving. That doesn't mean every token is a good investment, and it doesn't mean Dogecoin specifically will keep pace with the broader market. It does mean some investors want measured exposure to the space through a retirement account rather than sitting it out entirely. Whether that trade-off makes sense depends on your own risk tolerance, and it's worth talking to a financial advisor and doing your own research before allocating any retirement funds to it.
Book a free call with a self-directed retirement specialist
- Review your self-directed retirement options
- Learn about investing in alternative assets
- Get all of your questions answered
Solo 401(k) or Self-Directed IRA for Dogecoin?
Which account makes sense mostly comes down to how you earn income.
Solo 401(k)
A Solo 401(k) requires self-employment income, whether from your own business, freelance work, or gig income, and no full-time employees other than a spouse or business partner. For anyone who qualifies, it's typically the stronger plan: higher annual contribution limits than an IRA, a Roth option, and a participant loan feature that lets you borrow up to the lesser of $50,000 or 50% of your vested balance. As long as the investment isn't a collectible and doesn't involve a disqualified person, cryptocurrency, including Dogecoin, is fair game.
Self-Directed IRA
Anyone with earned income can open a Self-Directed IRA, and it's the more accessible option if you don't have self-employment income to work with. Existing 401(k) or IRA balances can typically be rolled into one. A Self-Directed IRA custodian that supports crypto, like IRA Financial, lets you hold Dogecoin and other digital assets right alongside more traditional alternative investments. Traditional and Roth versions work the same way here as they do for a Solo 401(k): pretax contributions with deferred tax, or after-tax contributions with tax-free qualified withdrawals.
Does Buying Dogecoin Trigger UBTI?
This is worth clearing up, because it gets misstated a lot. Simply buying and holding Dogecoin, or any crypto, in a Self-Directed IRA or Solo 401(k) isn't a trade or business, so it doesn't create Unrelated Business Taxable Income on its own, in either account type. UBTI becomes a real concern only if you're trading crypto on margin or with borrowed funds, which brings in the same debt-financed income rules that apply to leveraged real estate. If you're curious how that calculation actually works, I've broken down the mechanics in more detail in this piece on real estate UBTI, and the same underlying framework applies. For a straightforward, unleveraged Dogecoin purchase, it's not something you need to plan around.
Why Dogecoin, Specifically?
Dogecoin started as a joke in 2013, built around the “Doge” meme of a Shiba Inu with broken-English captions, and for years it traded for a fraction of a penny. That changed in early 2021, when a wave of Reddit-driven retail trading, amplified by Elon Musk's public enthusiasm for the coin, pushed it to an all-time high near $0.72 in May of that year before it settled back down considerably.
As of 2026, Dogecoin trades in the $0.08 to $0.09 range with a market cap of roughly $13 billion, well off its 2021 peak but still among the more actively traded and liquid meme coins by volume. It remains a fraction of the price of Bitcoin, which trades well above $75,000 per coin today. Dogecoin describes itself as “an open source peer-to-peer digital currency, favored by Shiba Inus worldwide,” a description that doesn't take itself too seriously, and it's built a real niche in microtipping and crowdfunding campaigns along the way. It's not likely to replicate the returns of the larger, more established cryptocurrencies, but for investors who want a small, low-cost way to get exposure to the meme coin corner of the market, it's an accessible entry point.
Final Thoughts
Dogecoin is a volatile, speculative asset whether you buy it inside a retirement account or outside one. What changes inside a Self-Directed IRA or Solo 401(k) is the tax drag: no capital gains bill on every trade, and no year-end scramble to track cost basis on dozens of transactions. If you're going to take a position in Dogecoin as part of a diversified retirement portfolio, doing it inside a tax-advantaged account is usually the more efficient way to do it. Just size the position sensibly, and do your own due diligence before committing any retirement funds to it.
Real Estate UBTI in a Self-Directed IRA: When Does It Apply?
I get some version of this question from almost every client who wants to buy real estate inside a Self-Directed IRA: will I owe tax on this? Most of the time, the answer is no. Real estate is one of the most tax-efficient assets you can hold in an IRA. But there's a real exception called Unrelated Business Taxable Income, or UBTI, and it catches people off guard when they finance a deal with debt or start running a property like a business rather than holding it as an investment. Here's when real estate UBTI actually applies, and when it doesn't.
Key Takeaways
- Most rental income and gains from real estate sales are exempt from UBTI in a Self-Directed IRA, but that exemption breaks down the moment you use debt to finance the purchase.
- Unrelated Debt-Financed Income (UDFI) taxes only the percentage of income or gain tied to the leveraged portion of the property, not the whole return.
- If your IRA is taxed on UBTI or UDFI, it's taxed using compressed trust tax brackets, which hit the top 37% federal rate at just $16,000 of taxable income for 2026, far sooner than an individual filer would hit that bracket.
- The IRS uses a six-factor “facts and circumstances” test, first laid out in Adam v. Commissioner, to decide whether a real estate sale looks like investment activity or an active real estate business.
- Structuring the deal correctly up front, and knowing which factors the IRS actually weighs, is usually enough to keep a real estate investment out of UBTI territory entirely.
What Is UBTI?
UBTI stands for Unrelated Business Taxable Income. The IRS defines it as gross income from any trade or business that a tax-exempt organization, including an IRA, regularly carries on, minus the deductions directly connected to that business. When your IRA is a partner in an LLC or limited partnership, the entity's UBTI passes through to the IRA as if the IRA earned it directly.
The IRS created these rules in the 1950s for a straightforward reason: to stop tax-exempt entities from competing unfairly against taxable businesses by running an active trade without paying tax on the profits. Those rules live in Internal Revenue Code Sections 511 through 514, and a Self-Directed IRA, which is otherwise tax-exempt under Section 408, isn't excused from them.
When Debt-Financed Real Estate Triggers UDFI
The exception inside the exception is Unrelated Debt-Financed Income, or UDFI, and it's the one that actually affects most real estate investors using a Self-Directed IRA to invest in real estate.
Most real estate rental income is exempt from UBTI outright. Rents, along with dividends, interest, annuities, and royalties, are on the IRS's list of excluded income types. But that exclusion disappears for any portion of a property financed with debt, whether that's a mortgage, a note from a private lender, or seller financing. Only the leveraged percentage of the income is taxed, calculated as the average acquisition debt divided by the property's average basis over the year. If your IRA put 50% down and financed the rest, roughly half the rental income becomes subject to UDFI.
The same math applies when you sell. Gain on the sale of a leveraged property is UDFI too, unless the debt has been fully paid off for more than 12 months before the sale closes. Pay off the loan a year ahead of a sale and the UDFI exposure goes away. For a deeper walkthrough of how the calculation works in practice, I've written more on UBIT and UDFI on leveraged IRA real estate.
What Counts as a Regularly Carried-On Business
UBTI can also show up without any debt involved, if your IRA is operating what looks like an active business rather than holding a passive investment. Running a factory, a gas station, or an equipment rental operation through an IRA-owned LLC would all trigger UBTI, because those are trades regularly carried on for profit, not investment holdings.
Gains and losses from selling property are generally excluded from this analysis, with one exception: property held as inventory, or held primarily for sale to customers in the ordinary course of business, doesn't get the exclusion. That's where the real estate-specific test comes in.
Book a free call with a self-directed retirement specialist
- Review your self-directed retirement options
- Learn about investing in alternative assets
- Get all of your questions answered
The Tax Rate on UBTI and UDFI
Here's the part that surprises people. An IRA is treated as a trust for tax purposes, and trusts hit the top federal rate far faster than individuals do. For 2026, the trust tax brackets are:
|
Taxable Income |
Tax Rate |
|
$0 – $3,300 |
10% |
|
$3,300 – $11,700 |
$330 plus 24% of the amount over $3,300 |
|
$11,700 – $16,000 |
$2,346 plus 35% of the amount over $11,700 |
|
Over $16,000 |
$3,851 plus 37% of the amount over $16,000 |
An individual filer doesn't reach the 37% bracket until well into six figures of income. A trust, and by extension an IRA with UBTI or UDFI exposure, gets there at $16,000. That compression is exactly why it's worth structuring a leveraged real estate deal carefully, or using a Solo 401(k), which has its own UDFI exception for real estate that an IRA doesn't get. Note also that UBTI only becomes a filing obligation once it crosses $1,000 in a given tax year, so smaller, partially leveraged deals often stay under the radar entirely.
How to Calculate UBTI on a Rental Property
The math looks intimidating until you walk through it once. Here's a simplified example using a leveraged rental property.
Say your IRA buys a $400,000 rental property, putting $200,000 down in cash and financing the other $200,000 with a nonrecourse loan. IRAs can't personally guarantee a loan, so any financing has to be nonrecourse.
- Find the debt-to-basis ratio. Divide the average acquisition debt for the year by the property's average adjusted basis: $200,000 ÷ $400,000 = 50%. That percentage is what's “unrelated debt-financed” and taxable.
- Apply the ratio to net income. If the property nets $24,000 in rental income for the year after expenses and depreciation, 50% of that, or $12,000, is UDFI.
- Subtract the $1,000 specific deduction. Every exempt organization, including an IRA, gets a flat $1,000 deduction against UBTI under IRC Section 512(b)(12), regardless of income level. That leaves $11,000 in taxable UDFI.
- Apply the trust tax brackets. Using the 2026 table above, $11,000 falls in the second bracket: $330 plus 24% of the amount over $3,300, which comes out to roughly $2,178 in tax.
On $24,000 of rental income, the IRA owes about $2,178, an effective rate under 10% of the total return, not the 37% top bracket most people assume applies to the whole thing. The tax gets paid directly out of the IRA's own funds, and once UBTI or UDFI exceeds $1,000 for the year, the IRA needs its own EIN and has to file Form 990-T. Pay off that loan and the calculation, along with the filing requirement, goes away on future years' rental income.
Book a free call with a Self-Directed IRA specialist
- Walk through how a specific leveraged property, syndication, or LLC investment would be taxed under UDFI before you commit capital
- Get a plain-English read on whether your deal looks more like an investment or an active real estate business under IRS rules
- Compare how a Self-Directed IRA versus a Solo 401(k) would treat the same deal, since the UDFI exception only applies to one of them
I started IRA Financial after spending two hours in a law library in 2008 tracking down the answer to a client's question about what a Self-Directed IRA could actually hold. UBTI questions come up constantly in that same spirit: the rules are more workable than most investors assume, but only if you understand them before you sign a purchase agreement. Our in-house tax attorneys review deal structures with clients directly, which is part of why we've kept a flat $495 annual fee instead of charging based on assets under management.
How the IRS Decides Whether a Real Estate Sale Is a Business
This is where most of the real disputes happen, and it's also where a decades-old Tax Court case still does the heavy lifting. In Adam v. Commissioner, 60 T.C. 996 (1973), no relation, the Tax Court laid out six factors for deciding whether a real estate sale was an investment or an active dealer transaction subject to UBTI. Courts and the IRS still apply this same “facts and circumstances” test today, including in private letter rulings involving exempt organizations and IRAs.
- Purpose of Acquisition
Why did you buy the property in the first place? If the original intent was to hold it as an investment, that supports excluding the eventual sale from UBTI. Intent at acquisition carries real weight throughout the rest of the analysis.
- Frequency, Continuity, and Size of Sales
This is often the deciding factor. A single sale, or a handful of infrequent ones, looks like an investor liquidating a position. A steady pattern of sales over time starts to look like a business. That said, the IRS has issued favorable rulings even at meaningful volume, including one allowing up to 15 sales spread over 5 to 10 years, and another approving the sale of 45 of 68 lots when inflated development costs forced a faster sell-off than originally planned.
- Improvement and Disposition Activities
Selling raw, undeveloped land with minimal activity on your part supports investment treatment. In one favorable ruling, an organization sold undeveloped land where all improvements had been built by unrelated third parties, and the lack of development activity on the seller's side was central to the finding.
- Extent of Improvements Made
There's a real tension here. Doing more to a property can increase its value and your return, but it also looks more like a business. The IRS has allowed improvements required by local ordinances, such as streets, curbs, sidewalks, and utility hookups needed to subdivide land for sale, without treating that as disqualifying. Staying hands-off on marketing and advertising, and limiting your role to what's legally required, tends to help.
- Proximity of Sale to Purchase
Longer holding periods favor investment treatment. In one case, a school held land received by bequest for years before an eventual sale forced by condemnation, and that extended holding period, paired with no active marketing, kept the sale out of UBTI.
- Purpose During the Taxable Year
This overlaps with the holding period question but looks specifically at intent during the year of sale. The longer and more clearly the property was held for investment purposes right up until the sale, the stronger the case for exclusion.
No single factor decides the outcome on its own. The Tax Court, and the IRS in the private letter rulings that followed, weighs all six together against the full set of facts.
Final Thoughts
Real estate UBTI is one of the more misunderstood corners of Self-Directed IRA investing, mostly because the exceptions get more attention than the rule. Most straightforward, all-cash real estate investments in an IRA never touch UBTI at all. The exposure shows up specifically around leverage and around deals that start to look like an active business rather than a passive investment. Know which bucket your deal falls into before you close, structure around it where you can, and you'll keep the tax advantages of the IRA intact.
