

The Peter Thiel Roth IRA Playbook: How Ordinary Americans Can Use the Same Tax-Free Strategy

The Peter Thiel Roth IRA has become one of the most famous examples of what can happen when an investor combines an extraordinary investment with an extraordinary tax structure. Most people know Thiel as the billionaire who co-founded PayPal and Palantir and became one of the earliest outside investors in Facebook. From my perspective as a tax lawyer, however, the most interesting part of his story isn’t only the investments he made. It’s where he made some of them.
Key Takeaways
- According to ProPublica, Thiel’s Roth IRA grew from less than $2,000 in 1999 to roughly $5 billion by 2019.
- He didn’t contribute billions; he placed low-value, high-growth private investments inside a Roth and let appreciation do the work.
- A Self-Directed Roth IRA can hold real estate, private businesses, and other alternative assets that most brokerages won’t offer.
- IRA-owned real estate must be a true investment, since IRC Section 4975 bars you from personally using the property.
- High earners can still reach Roth treatment through a Backdoor Roth IRA or a Roth conversion, which has no income limit.
Peter Thiel, Casa Encantada, and the Investor Mindset
Thiel reportedly used his Roth IRA to acquire very inexpensive shares of early-stage private companies before those companies became enormously valuable. That story has always fascinated me because it shows something about the Roth IRA that most Americans still don’t appreciate. If used properly, a Roth IRA can be one of the most powerful tax-free investment vehicles available under the Internal Revenue Code.
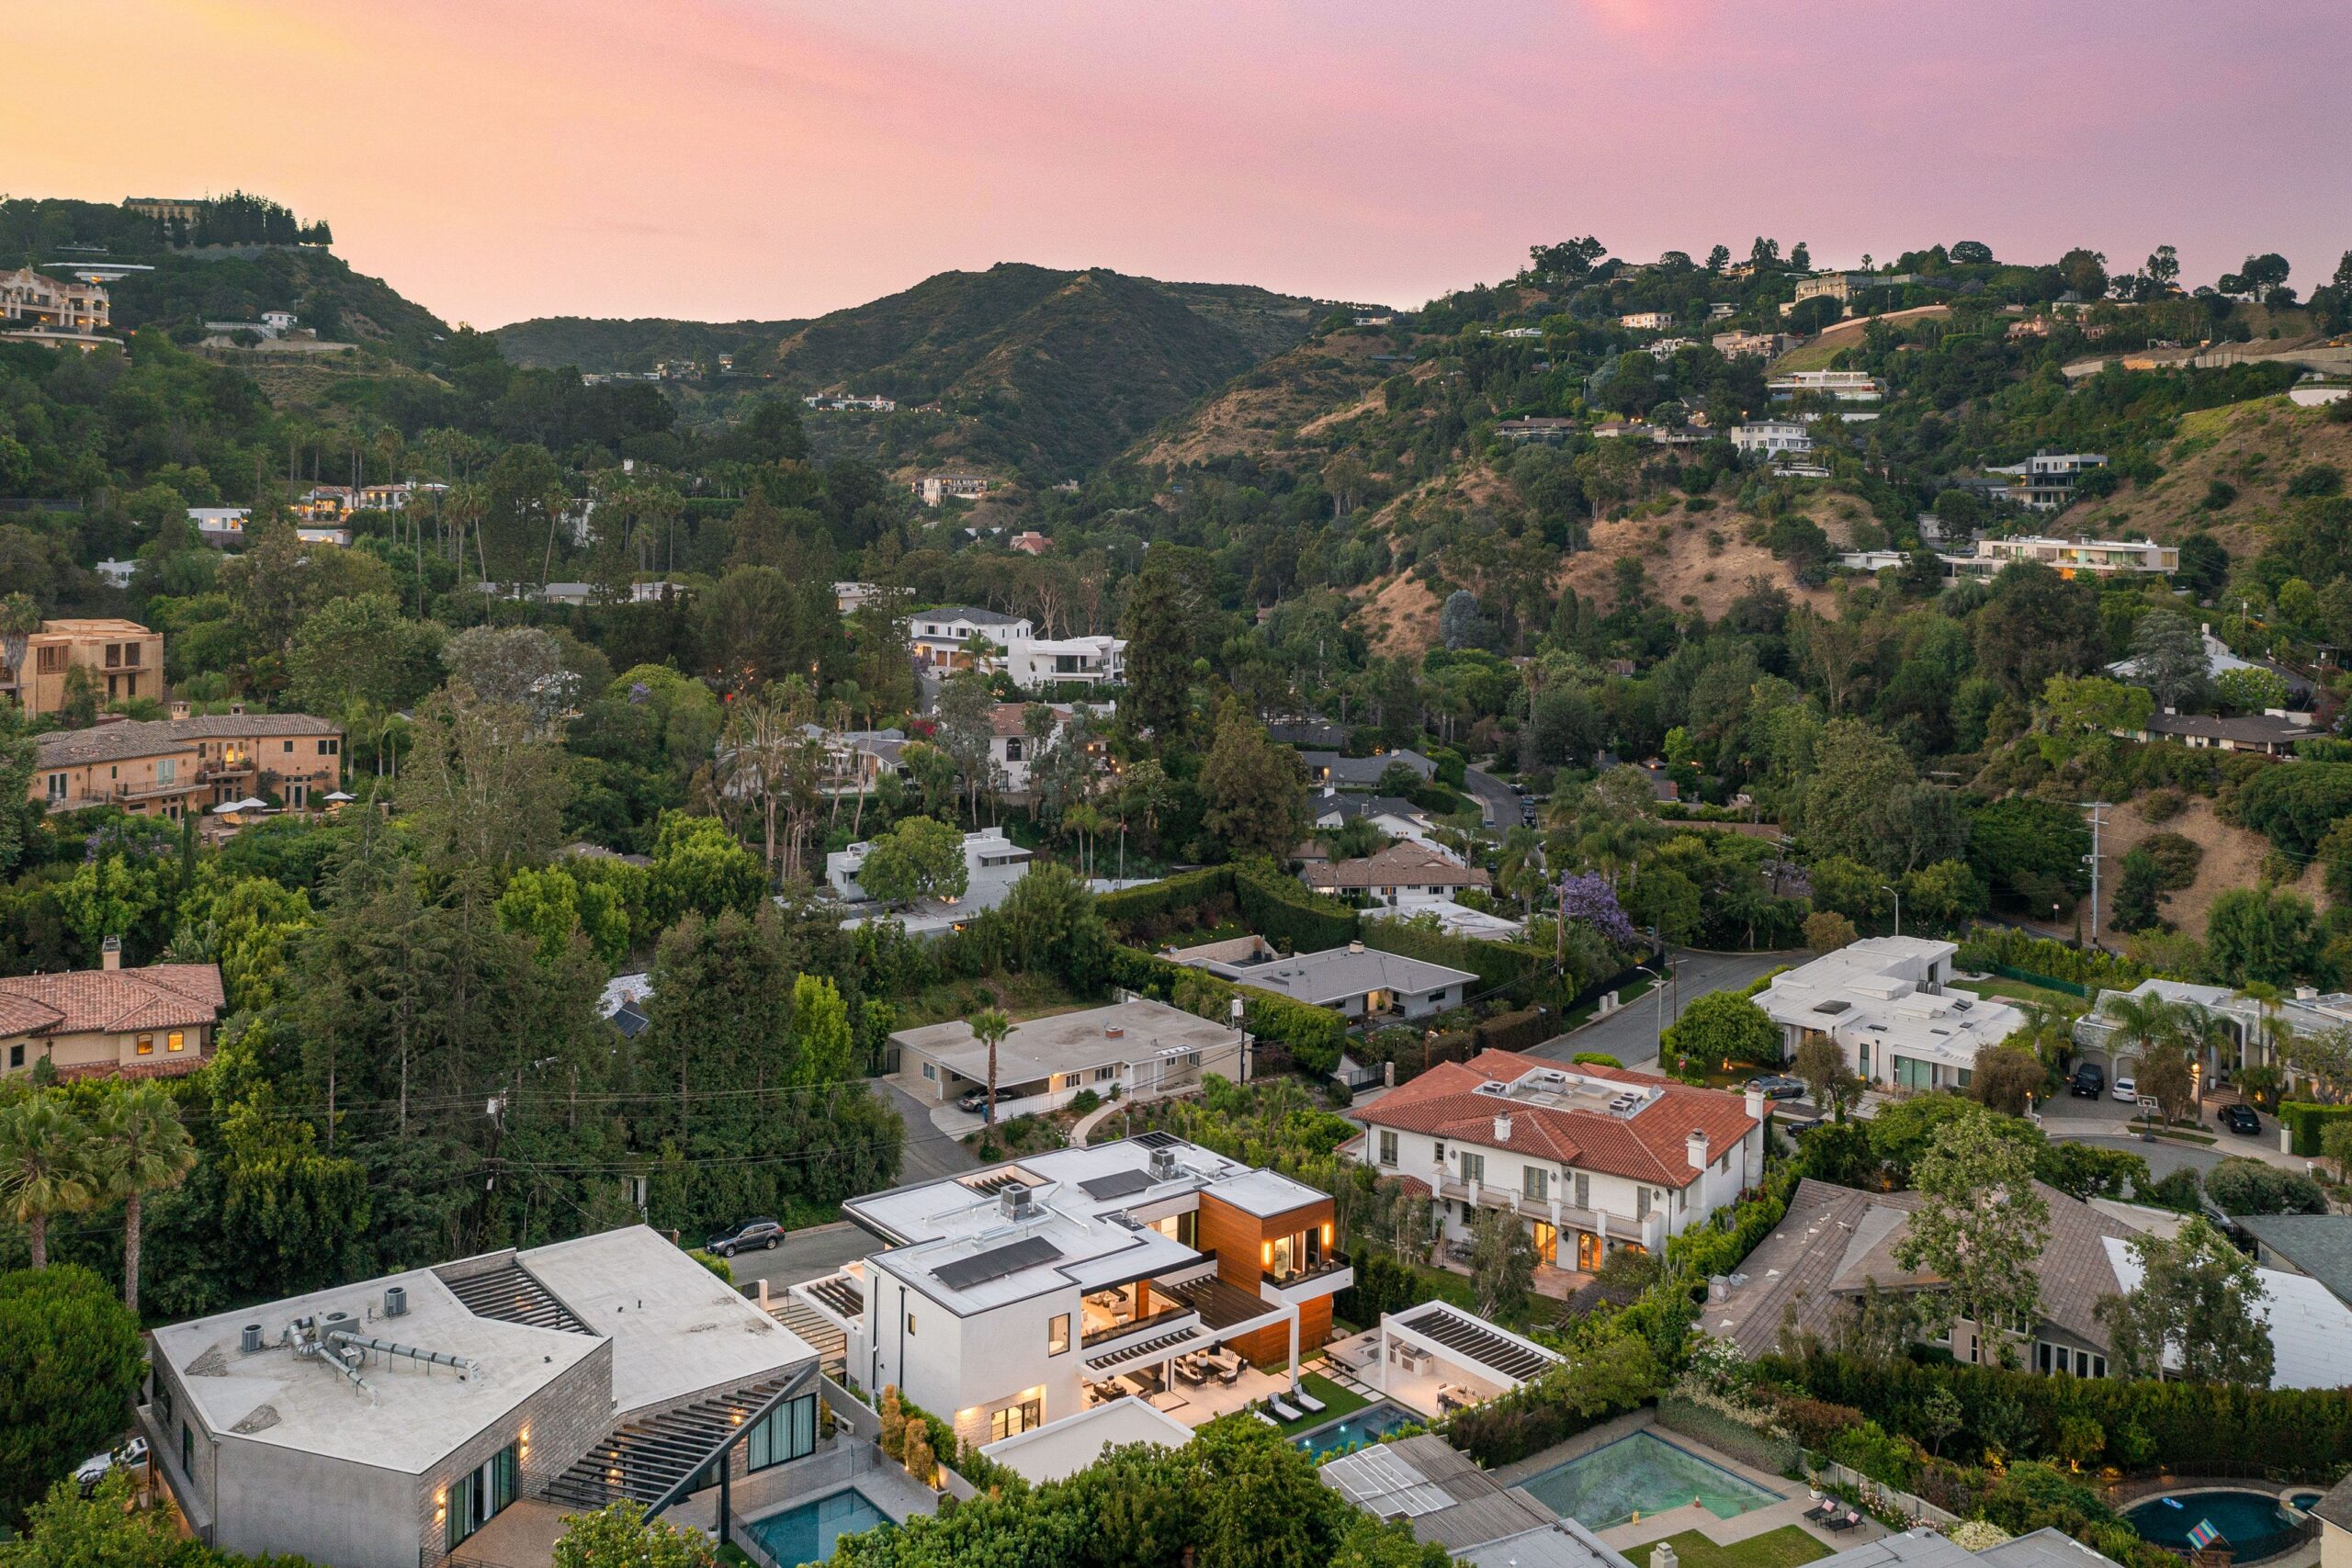
A recent Wall Street Journal story brought this concept back to mind. According to the Journal, Thiel was behind the $130 million purchase of Casa Encantada, a roughly 40,000-square-foot estate on about 8.5 acres in Bel-Air, acquired at a foreclosure auction through an LLC associated with him. The most interesting detail to me was that Thiel reportedly doesn’t intend to live in the house. He views the property as an investment and plans to renovate it.
There’s no public evidence that Thiel purchased Casa Encantada through his Roth IRA, and I’m not suggesting that he did. But the transaction reminded me of the philosophy behind his famous Roth IRA strategy: invest in assets with significant long-term appreciation potential, and combine that with the tax advantages of a Roth.
How Peter Thiel Built a $5 Billion Roth IRA
The origins of the Peter Thiel Roth IRA go back to the early days of PayPal. According to ProPublica’s reporting, Thiel acquired approximately 1.7 million founder shares of the company that became PayPal through his Roth IRA in 1999, for roughly $1,700, or about one-tenth of a cent per share. At the time, those shares were highly speculative, and they had little value because the company was still at a very early stage. That’s exactly what made the Roth IRA so powerful.
As PayPal grew, the appreciation occurred inside Thiel’s Roth. ProPublica reported that the account grew from less than $2,000 in 1999 to approximately $3.8 million by the end of 2000. By the end of 2002, the year eBay acquired PayPal, it was worth roughly $28.5 million. Thiel then redeployed that capital inside the Roth into additional investments, and reporting has connected his Roth IRA to companies such as Palantir and Facebook. By 2019, ProPublica reported that the account had reached approximately $5 billion.
| Year | Reported Roth IRA value |
|---|---|
| 1999 | Less than $2,000 |
| 2000 | About $3.8 million |
| 2002 | About $28.5 million |
| 2019 | About $5 billion |
The most important point is that Thiel didn’t contribute $5 billion to a Roth IRA. He couldn’t have, because Roth contribution limits are relatively small. Instead, he placed investments with extraordinary appreciation potential inside a Roth when those investments had relatively low values, and the appreciation did the rest. That’s the Peter Thiel Roth IRA playbook in its simplest form.
Why the Roth IRA Can Be So Powerful
The basic tax concept behind a Roth IRA is surprisingly simple. You generally don’t receive a deduction for a Roth contribution because it’s made with after-tax dollars. In exchange, future earnings and appreciation can be distributed tax-free if the requirements for a qualified distribution are satisfied. Generally, that means the five-year requirement has been met and the distribution occurs after age 59½, although the tax law provides certain other circumstances that can produce qualified distributions.
This creates an enormously attractive opportunity for long-term investors. If I place $10,000 into a Roth IRA investment and it becomes worth $20,000, the tax savings are useful. If that same $10,000 becomes worth $500,000 or $1 million, the value of the Roth structure becomes dramatically more important. Thiel simply demonstrated the concept at an almost unimaginable scale.
His story also shows why investors should think about more than how much they can contribute each year. Contributions matter, but investment selection and asset location can be equally important. You should also think about which investments you want growing inside your Roth.
The Self-Directed IRA Is the Missing Part of the Story
There’s another aspect of the Thiel story that often gets overlooked. He didn’t build his enormous Roth IRA by purchasing publicly traded stocks or mutual funds. He used private-company investments, and that’s where the Self-Directed IRA becomes so important.
Most Americans have been conditioned to believe an IRA is essentially a brokerage account. They open one at a large financial institution, get offered stocks, bonds, mutual funds, and ETFs, and naturally assume those are the only investments an IRA can legally own. A Self-Directed IRA operates under the same general IRA tax rules. The principal difference is that a Self-Directed IRA custodian is willing to administer alternative investments, which, depending on the structure, can include real estate, private businesses, private equity, venture capital, investment funds, certain precious metals, and other alternative assets.
This is what makes a Thiel-style strategy possible. If you want to use retirement money to invest in an early-stage business, a private fund, or investment real estate, you generally need a provider willing and able to custody or administer that asset. These opportunities have existed for decades. Most Americans have simply never been told about them, which is a big part of why I started IRA Financial in 2010.
Why Aren’t Self-Directed IRAs Better Known?
I’ve worked in the self-directed retirement industry for more than two decades, and this remains one of the most frustrating aspects of our retirement system. The IRA has existed for more than 50 years, yet many Americans still believe their retirement account is legally limited to stocks, bonds, and mutual funds.
In my view, much of this comes down to economics. Large banks and brokerage firms have built very successful businesses around products they can efficiently custody, trade, and monetize. Investment real estate doesn’t fit that model, and neither does a private business or a venture capital investment. There are also legitimate administrative, valuation, compliance, and liquidity issues with alternative investments, which helps explain why many institutions choose not to offer them.
The result is that many investors confuse the investment menu offered by their financial institution with the investment rules imposed by Congress. Your brokerage firm determines which investments it’s willing to offer you. The Internal Revenue Code determines the legal boundaries of what your IRA can own.
Could a Self-Directed Roth IRA Own Real Estate Like Casa Encantada?
Again, there’s no public evidence that Peter Thiel used his Roth IRA to acquire Casa Encantada. However, I wouldn’t be surprised if he did. If I had to bet, I’d bet he used Roth IRA funds for at least some part of the investment. He reportedly has an enormous Roth IRA, a long history of using it for investments with significant appreciation potential, and Casa Encantada is reportedly being acquired as an investment rather than a personal residence. From a tax-planning standpoint, it’s exactly the type of asset that makes a Self-Directed Roth IRA so attractive.
Of course, that’s my speculation based on his publicly reported investment history, not a statement that his Roth IRA owns the property. What we do know is that a properly structured Self-Directed Roth IRA can own investment real estate. The important word is “investment.”
An IRA can’t purchase a house so that the IRA owner can live in it. The prohibited transaction rules under Internal Revenue Code Section 4975 generally prevent an IRA owner and certain other disqualified persons from personally using or benefiting from IRA-owned property. If your Self-Directed Roth IRA buys a beachfront home, you can’t spend your summer vacation there. If it buys a condominium in Miami, you can’t use it for a weekend. Paying fair-market rent wouldn’t necessarily solve the problem either, because the issue is the transaction between the IRA and a disqualified person.
That’s why the Casa Encantada detail caught my attention. Thiel reportedly views the property as an investment, which illustrates the distinction between buying real estate for personal use and buying it because you believe it’s an attractive investment. That distinction is fundamental in the Self-Directed IRA world, and I cover the mechanics in more detail in my guide to using your IRA to buy a rental property.
You Don’t Have to Be Peter Thiel to Get Money Into a Roth
Another misconception I regularly hear is that higher-income Americans can’t have Roth IRAs. The tax law does impose income limitations on direct Roth IRA contributions, but that doesn’t mean a higher-income taxpayer is locked out of the Roth world.
The Backdoor Roth IRA strategy can allow a high-income taxpayer to make a nondeductible contribution to a Traditional IRA and then convert those funds to Roth. Anyone considering it must be aware of the IRA aggregation and pro-rata rules, particularly if they already have pre-tax Traditional, SEP, or SIMPLE IRA assets.
Book a free call with a self-directed retirement specialist
- Review your self-directed retirement options
- Learn about investing in alternative assets
- Get all of your questions answered
There’s also a much larger opportunity through Roth conversions. There’s generally no income limitation on converting eligible pre-tax IRA funds to Roth. The converted amount that hasn’t previously been taxed is generally included in taxable income for the year of conversion. In other words, you voluntarily pay income tax today in exchange for moving money into the Roth environment.
The Best Time to Think About a Roth Conversion
I don’t believe everyone should automatically convert all of their pre-tax retirement savings to Roth. A Roth conversion is a tax transaction, and it needs to be analyzed carefully. These are the four questions I look at.
- What is the asset worth today? If an investment has fallen significantly in value but I remain extremely bullish on its long-term prospects, that may create an attractive conversion opportunity. A lower valuation means less taxable income today, while future appreciation can occur inside the Roth.
- How strongly do you believe in its future appreciation? The Roth becomes more valuable when the underlying investment performs exceptionally well. If an asset could increase fivefold or tenfold over a long period, paying tax on today’s lower value may look very attractive years later.
- Can you afford the tax? A conversion can generate a significant current tax liability. In many situations, it’s better to pay the tax with personal funds outside the retirement account so more retirement money stays invested.
- How does your current tax rate compare with your expected future rate? Nobody knows where tax rates will be 10, 20, or 30 years from now. If you believe your future rate will be the same or higher, paying tax today becomes more attractive.
I’ve personally followed this strategy. I converted pre-tax retirement funds to Roth over a period of years because I wasn’t in a position to pay the tax on converting the entire balance in a single year. Spreading the conversions out let me gradually move assets into Roth while managing the tax liability, and it taught me that Roth planning doesn’t have to be an all-or-nothing decision.
I Followed the Thiel Playbook Myself
My results are nowhere near Peter Thiel’s reported $5 billion Roth IRA. However, the basic strategy behind his success has influenced how I’ve managed my own retirement investments.
As a tax lawyer, I look at every investment through two lenses. The first is how much the investment could potentially earn. The second is how much of that return I’ll actually keep after taxes. Over the years, I’ve used self-directed retirement structures to invest in real estate, Bitcoin, and several private businesses. My objective wasn’t to find the next PayPal. It was to identify investments I believed had substantial long-term appreciation potential and, whenever appropriate, hold them in a Roth structure.
Following that philosophy helped me become a tax-free retirement millionaire in my mid-40s. It’s also one of the reasons I’m so passionate about educating Americans about Self-Directed Roth IRAs. I’ve seen firsthand how powerful the combination of alternative investments and Roth tax treatment can be.
Final Thoughts: The Thiel Strategy Is Available to Ordinary Americans
The biggest lesson from Peter Thiel’s Roth IRA shouldn’t be that billionaires have access to some magical retirement account ordinary Americans can’t use. The Roth IRA rules are part of the same Internal Revenue Code that applies to everyone.
Very few people will ever replicate Thiel’s results. Finding an early-stage PayPal, Facebook, or Palantir is extraordinarily difficult, and private investments involve substantial risk. But you don’t need to turn $2,000 into $5 billion for the strategy to have a meaningful impact on your retirement. Imagine investing $25,000 of Roth money into a private company that eventually becomes worth $250,000, or buying investment real estate inside a Self-Directed Roth IRA that appreciates significantly over 20 years. The numbers don’t need to reach billions before the tax benefits become significant.
The broader lesson is to think about your Roth IRA as a long-term investment vehicle, one where your most successful investments can compound for decades without annual taxation and ultimately be distributed tax-free if the qualified distribution requirements are met. Thiel acquired investments when their values were low, placed some of them inside a Roth, let the appreciation happen in that tax-advantaged environment, and kept reinvesting.
For me, that’s the most important lesson of the Peter Thiel story. The goal shouldn’t be to become Peter Thiel. It should be to understand what he understood very early: when you believe an investment has significant long-term appreciation potential, where you own it can be almost as important as what you own. And when that investment can legally and appropriately be held inside a Self-Directed Roth IRA, the potential tax benefits can last a lifetime.
This content is for educational purposes only and does not constitute legal, tax, or investment advice. Consult a qualified professional before making any investment decisions.

Related Articles
Carried Interest in Your Roth IRA: What Investment Professionals Need to Know
For private equity managers, venture capital sponsors, real estate syndicators, and hedge fund managers, a carried interest is often the most…
Why I Support the Trump Account: A Tax Attorney’s Perspective
As a tax attorney, I spend my days thinking about one thing: how to legally help Americans keep more of their money and build long-term wealth. For…
The Rise of Progressive Politics and the Roth IRA: Why Locking In Tax-Free Wealth Matters More Than Ever
If there is one lesson I have learned during more than two decades practicing tax law, it is this: tax laws never stand still. Congress changes.…
Buy a Home in Your Self-Directed Roth IRA and Live in It Tax-Free
Most investors understand that a Roth IRA offers tax-free growth and tax-free withdrawals. What many people don't realize is that a Roth IRA can do…