

Does a Solo 401(k) Have the Same UBTI Rules as a Self-Directed IRA LLC?
Yes and No. Like an IRA, the tax advantage of a Solo 401(k) Plan is that income is tax-free until distributed. In general, an exempt organization is not taxed on its income from an activity that is substantially related to the charitable, educational, or other purpose that is the basis for the organization's exemption. Such income is exempt even if the activity is a trade or business. However, to prevent tax-exempt entities from competing unfairly with taxable entities, tax-exempt entities are subject to unrelated business taxable income (UBTI) when their income is derived from any trade or business that is unrelated to its tax-exempt status. Solo 401(k) and UBTI rules are much different than an IRA.
What is Unrelated Business Taxable Income?
UBTI is defined as “gross income derived by any organization from any unrelated trade or business regularly carried on by it” reduced by deductions directly connected with the business. The UBTI rules only apply to exempt organizations such as charities, IRAs, and 401(k) Plans. Congress enacted the UBTI rules in the 1950s in order to prevent charities from competing with for-profit businesses since charities do not pay tax giving them an unfair advantage over for- profit businesses. With the enactment of ERISA in 1974, IRAs and 401(k), who are considered tax-exempt parties pursuant to Internal Revenue Code Sections 408 and 401 respectively, became subject to the UBTI rules. As a result, if an IRA or 401(k) invests in an active business through an LLC or partnership, the income generated by the IRA or 401(k) from the active business investment will be subject to the UBTI rules. In other words, a 401(k) Plan that is a limited partner, member of a LLC, or member of another non-corporate entity will have attributed to it the UBTI of the enterprise as if it were the direct recipient of its share of the entity's income which would be UBTI had it carried on the business of the entity. For example, if a Solo 401(k) Plan invests in an LLC that operates an active business such as a restaurant or gas station, the income or gains generated from the investment will generally be subject to the UBTI tax. However, if the Solo 401(k) Plan invested in an active business through a C corporation, there would be no UBTI since the C Corporation acts as a blocker blocking the income from flowing through to the Solo 401(k) Plan. This is why you can invest IRA and 401(k) funds into a public company, such as IBM without triggering the UBTI tax. Remember that if an IRA or 401(k) Plan makes a passive investment, such as rental income, dividends, and royalties, such income would not be subject to the UBTI rules.
Related: Solo 401(k) Investments
UDFI and The Solo 401(k) Plan
However, unlike a Self-Directed IRA LLC, in the case of a Solo 401(k) Plan, UBTI does not apply to unrelated debt-financed income (UDFI). The UDFI rules apply when a 401(k) Plan uses leverage to acquire property such as real estate. Pursuant to Internal Revenue Code Section 514(c)(9), a 401(k) Qualified Plan is not subject to the UDFI rules and, thus, the UBTI tax if non-recourse leverage is used to acquire property such as real estate. With the UBTI tax rates at approximately 40% for 2019, the Solo 401(k) Plan offers real estate investors looking to use non-recourse leverage in a transaction with a tax efficient solution.
Exceptions to the UBTI Rules
There are some important exceptions from UBTI: those exclusions generally exclude the majority of income generating investment activities from the UBTI rules - dividends, interest, annuities, royalties, most rentals from real estate, and gains/losses from the sale of real estate.
What is an Unrelated Business?
For a Solo 401(k), any business regularly carried on or by a partnership or corporation of which it is a member/partner is an unrelated business. For example, the operation of a shoe factory by a pension trusts, the operation of a financial consulting business for high net worth individuals by a university, or the operation of an computer rental business by a hospital would likely be treated as an unrelated business and subject to UBTI.
Solo 401(k) and UBTI - Real Estate Investments
Although there is little formal guidance on UBTI implications for Solo 401(k) Plans investing in real estate, there is a great deal of guidance on UBTI implications for real estate transactions by tax-exempt entities. In general, Gains and losses on dispositions of property (including casualties and other involuntary dispositions) are excluded from UBTI unless the property is inventory or property held primarily for sale to customers in the ordinary course of an unrelated trade or business. This exclusion covers gains and losses on dispositions of property used in an unrelated trade or business, as long as the property was not held for sale to customers. In addition, subject to a number of conditions, if an exempt organization acquires real property or mortgages held by a financial institution in conservatorship or receivership, gains on dispositions of the property are excluded from UBTI, even if the property is held for sale to customers in the ordinary course of business. The purpose of the provision seems to be to allow an exempt organization to acquire a package of assets of an insolvent financial institution with assurance that parts of the package can be sold off without risk of the re-sales tainting the organization as a dealer and thus subjecting gains on re-sales to the UBTI.
How Do I Avoid UBTI?
In general, if you make passive investments with your Solo 401(k) Plan, such as stocks, mutual funds, precious metals, foreign currency, rental real estate, etc. the passive income generated by the investment will generally not be subject to the UBTI tax. Only if your Solo 401(k) Plan will be making investments into an active business, such as a retail store, restaurant, software company using a passthrough entity such as an LLC or partnership will your Solo 401(k) Plan likely be subject to the UBTI tax. Solo 401(k) and UBTI rules can get very complicated. Please speak with a knowledgeable adviser concerning these matters.

Solo 401k Plan Controlled Group Rules
Solo 401k Plan Controlled Group
Some of our Solo 401k clients ask whether a business or individual can adopt a separate Solo 401k plan for another business or entity. One must first determine whether adopting the additional Solo 401k would violate the Controlled Group Rules set up by the IRS and Department of Labor.
The Controlled Group Rules were created to protect employees from a business owner or executive who establishes a separate 401k plan for another business and does not offer those employees the benefits inherent in participating in a 401k qualified retirement plan.
The IRS and Department of Labor were concerned that business owners who wanted to establish a qualified retirement plan did not want the burden of having to provide benefits to all eligible employees. As a result, they would create a new separate business which has no eligible employees and then adopt a Solo 401k plan for that company.
Since the new company would be wholly owned by the business owner and would not have any full-time employees, the business owner could establish his or her own Solo 401k plan and, thus, enjoy all the benefits of having a qualified retirement plan without having to provide any benefit to the employees from the other company.
What is a controlled group of corporations?
As per Internal Revenue Code Section 414, a controlled group is any two or more corporations connected through stock ownership in any of the following ways:
Parent-subsidiary group
- 80% of stock of each (subsidiary) corporation is owned by another member of the group
- Parent corporation must own 80% of the stock of at least one of the other members of the group
- The rules are subject to the stock attribution rules under Internal Revenue Code Section 318
Brother-sister group
- The same five or fewer individuals own at least 80% of the stock of the corporations
- “Individual” includes ownership by an estate or trust
- “Ownership” includes having a controlling interest and effective control of the corporations
- The rules are subject to the stock attribution rules under Internal Revenue Code Section 318
Combined group
- Combination of a Parent-subsidiary and a Brother-sister group
Determining who is part of a Controlled Group
To determine whether one is part of a controlled group, one must take into account the stock attribution rules. The purpose of the stock attribution rules is to attribute shares, or interest in a company held by certain family members, to the person in question and determine whether that person is part of a controlled group. Internal Revenue Code Section 318 governs the stock attribution rules. Pursuant to Internal Revenue Code Section 318, an individual shall be considered as owning the stock, owned directly or indirectly, by or for -
(i) his/her spouse (other than a spouse who is legally separated from the individual under a decree of divorce or separate maintenance)
(ii) his/her children, grandchildren, parents
Can companies in a controlled group be treated as separate companies?
The IRS does have a procedure through which a company can request to be treated as a Separate Line of Business (see IRC §414(r)). The following are limitations for these requests:
- Must have a valid business purpose
- Must have at least 50 employees within each line of business
- Restrictions on HCE ratios in each separate line of business
- Must notify IRS to request their approval
Do all members of a controlled group have to participate in one plan?
No. Members of a controlled group may each have a different plan. Similarly, two or more members of the controlled group may adopt a single plan. In either case, all employees of the controlled group must be taken into account for testing purposes.
For example, if one company is owned by a shareholder with greater than 80% and has no employees, but that same person also has ownership of over 80% in another company with full-time employees, a single plan may be adopted for both companies. However, the adopted plan must provide benefits to the eligible employees from the second company.
In other words, the rules are in place to restrict the owner(s) of a business with full-time employees from establishing a new company with no employees and adopting a Solo 401(k) plan that would exclude the full-time employees from the other company. The IRS and Department of Labor wanted to make sure that all eligible employees of a company that is part of a controlled group receive all available retirement benefits.
Controlled Group Examples
Example 1: Joe owns 90% of Company A that has 3 employees. Joe wants to adopt a qualified retirement plan, but does not want to offer any benefits to his employees. Joe decides he will establish a new company that has no employees and adopt a Solo 401k Plan through that new company. Before proceeding, Joe talks with a tax attorney about his idea. Joe’s tax attorney quickly points out that since Joe would own more than 80% of Company A and the newly established company, both companies would be part of a controlled group. This would prohibit Joe from establishing a plan for the new company without offering the employees from Company A the same plan benefits.
Example 2. Joe owns 45% of Company A and Joe’s son, Mike, owns the remaining 55% interest. Company A has 5 full-time employees. Joe and Mike want to establish a 401(k) plan so they make tax-deferred contributions, but don’t want to provide the employees with any plan benefits. Joe and Mike come up with the idea of forming a new company that will have no employees other than themselves and adopt a 401(k) plan through the new company. Joe talks this over with his tax attorney and learns that since Joe and Mike are father and son, under Internal Revenue Code Section 318 they will be treated as owning each other’s shares, giving them each over 80% interest in Company A and, thus, triggering the controlled group rules. Hence, Joe and Mike would be limited from opening a 401(k) plan for the new business and not offering plan benefits to the employees from Company A. Joe and Mike could establish a plan for the new company, but the controlled group rules would require that the plan benefits be provided to all eligible employees from both companies.
Example 3. Joe owns 78% of Company A and Tim, his friend, owns the remaining 22%. Company A has 12 full-time employees. Company A does not have a 401(k) Plan. Tim does some consulting on a part-time basis and wants to establish a new corporation for his consulting business as well as establish a Solo 401k plan. Tim speaks with his tax attorney to inquire whether he could adopt a Solo 401k plan for his new business without being required to offer benefits to the 12 full-time employees with Company A. Tim’s tax attorney told Tim that because he owns less than 80% of Company A, his new consulting company would not be part of a controlled group and, thus, he would not be required to offer 401(k) benefits from his new company to the Company A employees.
Example 4. Joe and Tim each own 50% of Company A, which has 4 full-time employees. Company A currently offers its employees 401(k) plan benefits. Joe and Tim are each over the age of 59 ½ and are interested in using some of their retirement funds to purchase real estate. Unfortunately, Company A’s retirement plan does not allow for non-traditional investments, such as real estate. Joe and Tim decide to establish a new corporation, which they will each own 50% of and then have that new company adopt a new 401(k) plan. Before proceeding, Joe and Tim decided to speak with their tax attorney to make sure this strategy would work. Joe and Tim’s tax attorney advised them that as the new company will be owned by the both of them, just like Company A, the controlled group rules would be triggered since the same five or fewer individuals own at least 80% of the stock of the two corporations. Thus, Jim and Tim would not be able to adopt a new 401(k) plan without offering the same benefits to the employees from Company A.
Affiliated Service Group
In light of Section 414(b) and (c) which requires that all employees of commonly controlled corporations or trades or businesses be treated as employees of a single corporation or trade or business, some business owners have attempted to circumvent these rules by arranging the ownership of related business entities in an artificial manner.
In order to prevent business owners from adopting a 401(k) plan through a newly established and wholly owned entity, Internal Revenue Code Section 414(m) was enacted. Section 414(m) was enacted to prevent such circumvention by expanding the idea of control to separate, but affiliated, entities. Proposed Treas. Reg. § 1.414(m) provides that all employees of the members of an affiliated service group shall be treated as if a single employer employed them.
What is an Affiliated Service Group?
An affiliated service group is one type of group of related employers and refers to two or more organizations that have a service relationship and, in some cases, an ownership relationship, described in IRC section 414(m). An affiliated service group can fall into one of three categories:
1. A-Organization groups (referred to as “A-Org”), consists of an organization designated as a First Service Organization (FSO) and at least one “A organization”,
2. B-Organization groups (referred to as “B-Org”), consists of a FSO and at least one “B organization”, or
3. Management groups.
First Service Organization
A First Service Organization (“FSO”) must be a "service organization". Performance of services is the principal business of the organization as defined in section 414(m)(3), and Proposed Treas. Reg. § 1.414(m)-2(f) .
A “Organization”
An “A” Organization refers to a corporation, partnership, or other organization. To be an A-Org, an organization must satisfy a two-part test:
1. Ownership Test: The organization is a partner or shareholder in the FSO (regardless of the percentage interest it owns in the FSO) determined by applying the constructive ownership rules as specified in section 318(a), and
2. Working Relationship Test: The organization "regularly performs services for the FSO," or is "regularly associated with the FSO in performing services for third parties. Facts and circumstances are used to determine if a working relationship exists.
“B” Organization
To be a B-Org, the organization must meet the following requirements:
1. A significant portion of its business must be the performance of services for a FSO, for one or more A-Org’s determined with respect to the FSO, or for both,
2. The services must be of a type historically performed by employees in the service field of the FSO or the A-Org’s, and
3. Ten percent or more of the interests in the organization must be held, in the aggregate, by persons who are highly-compensated employees (pursuant to IRC § 414(q)) of the FSO or A-Org.
Note – An A or B-Org need not be a service organization.
What is Considered Performance of Services?
The principal business of an organization will be considered the performance of services if capital is not a material income-producing factor for the organization, even though the organization is not engaged in a field listed in Proposed Treas. Reg. § 1.414-(m)-2(f)(2) .
Whether capital is a material income-producing factor must be determined by reference to all the facts and circumstances of each case. In general, capital is a material income-producing factor if a substantial portion of the gross income of the business is attributable to the employment of capital in the business as reflected, for example, by a substantial investment in inventories, plant, machinery or other equipment.
Capital is a material income-producing factor for banks and similar institutions. Capital is not a material income-producing factor if the gross income of the business consists principally of fees, commissions or other compensation for personal services performed by an individual.
Regardless of whether the above subparagraph applies, an organization engaged in any one or more of the following fields is a service organization:
- Health
- Law
- Engineering
- Architecture
- Accounting
- Actuarial science
- Performing arts
- Consulting
- Insurance
An organization will not be considered as performing services merely because:
- It is engaged in the manufacture or sale of equipment or supplies used in the above fields,
- It is engaged in performing research or publishing in the above fields,
or
- An employee provides one of the enumerated services to the organization or other employees of the organization, unless the organization is also engaged in the performance of the same services for third parties
Affiliated Service Group Examples
Example 1: Bob Brown, a doctor, is incorporated as Bob Brown, P.C. and this professional corporation is a partner in the Jones Surgical Group. Bob Brown and Bob Brown, P.C., are regularly associated with the Jones Surgical Group in performing services for third parties. The Jones Surgical Group is an FSO. Bob Brown, P.C. is an A-Org because it is a partner in the medical group and is regularly associated with the Jones Surgical Group to perform services for third parties. Thus, Bob Brown, P.C. and the Jones Surgical Group would constitute an affiliated service group. As a result, the employees of Bob Brown, P.C. and the Jones Surgical Group must be aggregated and treated as if they were employed by a single employer per section 414(m).
Example 2: The Ewing, Frank and Gold Partnership is a law partnership with offices in numerous cities. EFG, of New City P.C., is a corporation that is a partner in the law firm. EFG, of New City P.C. provides paralegal and administrative services for the attorneys in the law firm. All of the employees of the corporation work directly for the corporation, and none of them work directly for any of the other offices of the law firm.
The law firm is an FSO. The corporation is an A-Org because it is a partner in the FSO and is regularly associated with the law firm in performing services for third parties.
The corporation and the partnership would together constitute an affiliated service group. Therefore, the employees of EFG of New City, P.C. and the employees of The Ewing, Frank, and Gold Partnership must be aggregated and treated as if they were employed as a single employer per section 414(m).
Example 3: Richards & Associates is a financial services organization that has 11 partners. Each partner of Richards owns one percent of the stock in Ames Corporation. Ames provides services to the partnership of a type historically performed by employees in the financial services field. A significant portion of the business of Ames consists of providing services to Richards. Considering Richards as an FSO, the Ames Corporation is a B-Org because:
1. A significant portion of its business is in the performance of services for the partnership of a type historically performed by employees in the financial services field. and,
2. More than 10% of the interests in the Ames Corporation is held, in the aggregate, by the highly-compensated employees of the FSO (consisting of the 11 common owners of Richards and Associates). Accordingly, the Ames Corporation & Richards and Associates constitute an affiliated service group. Therefore, the employees of the Ames Corporations and Richards and Associates must be aggregated and treated as if they were employed by a single employer per section 414(m).
Example 4: Douglas Properties, Inc. sells land that it has purchased and developed. Curt is a 25% shareholder of Douglas and a 50% shareholder of Curt and Son Construction Company, Inc. Douglas Properties regularly engages the services of Curt and Son. Although it appears that Douglas Properties could be an FSO, the affiliated service group rules do not apply because Douglas Properties is not a service organization.
The Broad Scope of the Affiliated Service Group Rules & The Solo 401k Plan
The affiliated service group rules are extremely broad and can trigger the controlled group rules in many unexpected cases. For this reason it is extremely important to work with a trained tax and ERISA professionals to determine whether the affiliated service group rules would trigger the controlled group rules and, hence, prevent the adoption of a Solo 401k Plan or activate the need to offer plan benefits to certain employees. In other words, if the affiliated service rules are violated, the controlled group rules would apply and can prevent a business owner from adopting a Solo 401k Plan due to employees from an affiliated owned company.
Using a Loan with the Solo 401k Plan
Retirement investors often wonder if they can use a Solo 401k plan loan to make investments that require leverage, such as real estate. How does it work? Do the same rules that apply to acquiring a loan with a Self-Directed IRA also apply to the Solo 401k? In this article, we will explain the rules of a Solo 401k loan with references from the law.
Solo 401k Plan Loan
The IRS has always allowed a Solo 401k Plan to make traditional as well as non-traditional investments, such as real estate. However, the rules under Internal Revenue Code Section 4975 restrict a Solo 401k Plan participant from engaging in certain transactions known as the prohibited transaction rules.
Under IRC section 4975, one of the categories of prohibited transactions involve a disqualified person personally guaranteeing a loan made to a Solo 401k Plan. A Solo 401k plan participant is treated as a disqualified person pursuant to IRC 4975. As a result, a Solo 401k, also known as an Individual 401(k) or Self Directed 401(k) Plan, cannot use a recourse loan to purchase property owned by a Plan because a disqualified person (Solo 401k Plan participant) cannot personally guarantee a loan. Hence, you cannot use a Solo 401(k) loan to purchase real estate.
Related: How to Diversify Your Retirement Savings
Nonrecourse Loan to Purchase Real Estate
While a Solo 401(k) loan may not be an option to purchase real estate in your IRA, you can pursue nonrecourse financing. A non-recourse loan is a loan that does not require a personal guarantee on the part of the Solo 401k plan participant. In other words, a loan would limit a lender’s (bank) ability to go after an individual personally for non-payment of the loan. Instead, the lender’s sole remedy would be to look to the underlying property as satisfaction of the loan. Of course, this type of loan is more difficult to acquire and can be more expensive for a borrower.
Internal Revenue Code Section 514(c)(9) permits a few types of exempt organizations to make debt-financed investments in real property without becoming taxable under Code Section 514. Note – the exemption only applies to real estate purchases and not to other types of non-recourse financing, such as margin on stock.
Read more: Solo 401(k) for Real Estate
Organizations Exempt from Tax
The Section 514 exemption applies to any “qualified organization,” a term that includes (1) schools, colleges, universities, and their “affiliated support organizations,” (2) qualified pension, profit sharing, and stock bonus trusts, and (3) title holding companies exempt under § 501(c)(25). In general, indebtedness incurred by a qualified organization in acquiring or improving real property is not acquisition indebtedness if the transaction navigates through a long list of prohibitions.
Related: Best Alternative Investments for Retirement Accounts
Solo 401k Plan UBTI Exemption on Real Estate Investments
In other words, a Solo 401k Plan can use non-recourse leverage when purchasing real estate property with Plan assets and not be subject to the Unrelated Debt-Financed Income rules, which in-turn trigger an Unrelated Business Taxable Income (UBTI or UBIT) tax. Note – only non-recourse leverage can be used when acquiring property by a Solo 401k Plan since a disqualified person (401(k) plan participant or trustee) cannot personally guarantee the loan (recourse loan) since that would violate the prohibited transaction rules pursuant to Internal Revenue Code Section 4975.
It is important to remember that this exemption would not apply to an IRA since an IRA is not a qualified pension, profit sharing, and stock bonus trusts.
To satisfy the exemption under Internal Revenue Code Section 514, the price paid by the organization for the property or improvement must be fixed when the property is acquired or the improvement is completed, neither the amount nor the due date of any payment under the indebtedness can be contingent on the revenue, income, or profits from the property, and the property may not be leased to the person who sold the property to the organization or to any person related to the seller within the meaning of Code Section 267(b) or Code Section 707(b).
Types of Exempt Organizations
If the organization is a qualified pension, profit sharing, or stock bonus trust, the property may not be purchased from or leased to the employer of any of the employees covered by the trust or any one of several persons related to the employer. Financing for the property may not be received from the person who sold the property to the organization, a person related to the seller within the meaning of Code Section 267(b) or Code Section 707(b), or, if the organization is a qualified employee trust, an employer or related person who is disqualified from being seller or lessee under the rule described in the preceding sentence.
The property must usually be owned directly by the qualified organization, except that an interest in a partnership or other pass-through entity qualifies if all of the partners or other owners are qualified organizations and each partner or other owner is allocated the same distributive share of every item of partnership income, deduction, and credit.
When § 514(c)(9) was enacted in 1980, it applied only to qualified pension, profit sharing, and stock bonus plans, but its scope was broadened in 1984 to include schools, colleges, and universities.
401(k) Exemption from UBTI Tax
Many people ask why this exemption only applies to 401(k) Plans and not IRAs. The only reason given in the committee reports for the exemption is that some people wanted it: “Trustees of these plans are desirous of investing in real estate for diversification and to offset inflation. Debt-financing is common in real estate investments.” The provision was originally limited to qualified employee trusts on the theory that the income would eventually be taxed to employees and their beneficiaries.
Interested in learning more about a Solo 401(k) plan and your options to purchase real estate, and other alternative investments? Give us a call at 1-800-472-0646, email us at info@irafinancial.com, or hit the chat button to talk to one of our dedicated retirement specialists.
The Self-Directed IRA LLC Operating Agreement

A Self-Directed IRA LLC gives you checkbook control over how your retirement funds get invested, but that flexibility only works if the LLC's operating agreement actually reflects the rules an IRA has to follow. A standard, off-the-shelf operating agreement, the kind an attorney would draft for an ordinary small business, doesn't address any of that, and using one is one of the more common mistakes I see in this structure. Here's what a Self-Directed IRA LLC operating agreement actually needs to include, who ends up asking to see it, and what's changed recently around a filing requirement that used to be part of this conversation.
Key Takeaways
- A Self-Directed IRA LLC operating agreement has to build in the IRA prohibited transaction rules under IRC 4975, not just standard LLC governance language.
- Both your IRA custodian and the bank holding the LLC's checking account will typically ask to see a copy of the operating agreement before opening the account.
- A single-member IRA LLC is generally treated as a disregarded entity for tax purposes; a multi-member LLC files its own partnership return on Form 1065.
- As of a FinCEN rule finalized in August 2026, U.S. companies, including a domestic Self-Directed IRA LLC, are no longer required to file beneficial ownership information reports.
- The LLC still has to file Form 990-T if it generates more than $1,000 of unrelated business taxable income in a year.
How a Self-Directed IRA LLC Works
The checkbook control structure starts with an LLC that's funded and wholly owned by your IRA, typically with you, the IRA owner, serving as the LLC's manager. Instead of routing every investment through your custodian, who has to review and process each transaction, you write checks or wire funds directly from the LLC's own bank account. For an investor making frequent transactions, buying and selling real estate, funding a private deal, moving on time-sensitive opportunities, that speed is the entire point.
The LLC also adds a layer of liability protection, since a claim tied to one property or investment generally can't reach the IRA's other assets, and it gives you more privacy than a custodian-titled account, where every transaction passes through a third party's records. None of that changes what the underlying rules require, though. The LLC still has to follow the same prohibited transaction restrictions under IRC 408 and 4975 that would apply if the IRA held the asset directly. If you're still weighing whether the structure makes sense for what you're investing in, I've laid out the tradeoffs in more detail in do I need an LLC for my Self-Directed IRA investment.
Why a Standard LLC Operating Agreement Doesn't Work Here
A generic LLC operating agreement covers member rights, capital contributions, management authority, distributions, and dissolution, and that's genuinely enough for an ordinary small business. It says nothing, though, about disqualified persons, prohibited transactions, or the fact that the LLC's sole member is a retirement account rather than a person. A compliant agreement has to graft those IRA-specific restrictions onto the standard LLC provisions, which is exactly why a template pulled from a generic legal forms site or an attorney unfamiliar with retirement account law tends to fall short.
What the Agreement Actually Has to Address
| Provision | What It Has to Say |
|---|---|
| Sole purpose | The LLC exists to hold and invest IRA assets, and nothing else |
| Prohibited transactions | Explicit restrictions mirroring IRC 4975, barring transactions with disqualified persons |
| Manager authority | Who can act for the LLC, typically the IRA owner, and the limits on that authority |
| Distributions | All proceeds flow back to the IRA, never to the manager or another disqualified person personally |
| Dissolution | How the LLC unwinds and how any remaining assets return to the IRA |
Who Actually Asks to See This Document
In practice, two parties want a copy before anything moves. Your IRA custodian will generally require the executed operating agreement before releasing IRA funds to the LLC. The bank where you open the LLC's checking account will usually ask for it too, as part of the standard due diligence any bank runs before opening an account for an entity rather than an individual. Keep an executed copy on hand for both rather than scrambling to produce one when either party asks.
The Beneficial Ownership Reporting Question, Now Resolved
When the Corporate Transparency Act first took effect, most LLCs, a Self-Directed IRA LLC included, were expected to file a beneficial ownership information report with FinCEN identifying who controls the entity. That requirement went through a lot of back and forth: an interim rule in March 2025 narrowed it substantially, and FinCEN made that rollback permanent with a final rule effective August 14, 2026. U.S. companies, both domestic reporting companies and U.S. persons, are no longer required to file a BOI report at all. Foreign entities registered to do business in the U.S. still carry reporting obligations, but a domestic Self-Directed IRA LLC generally does not.
I'd still keep your formation documents, and any FinCEN identifier you may have obtained earlier, organized and accessible. This is an area that's changed direction more than once already and could again, but as of this writing, it isn't an active filing requirement for most clients setting up a Self-Directed IRA LLC.
Tax Filing for the LLC Itself
How the LLC gets taxed depends on how many members it has. A single-member IRA LLC, owned by just one IRA, is generally treated as a disregarded entity, meaning there's no separate federal return for the LLC itself. A multi-member LLC, owned by more than one IRA or investor, files its own partnership return on Form 1065 and issues a Schedule K-1 to each member. Either way, if the LLC produces unrelated business taxable income, from debt-financed real estate or an operating business, for example, a Form 990-T is required once that income passes $1,000 for the year. I go through the full compliance picture, state by state, in our Self-Directed IRA LLC compliance guide.
Who Drafts the Agreement
The agreement should come from someone who understands both LLC law and the IRA prohibited transaction rules together, not a generic template pulled offline. Our agreements at IRA Financial come out of an in-house team that includes tax attorneys, several of whom, myself included, began our careers at large law firms before I founded IRA Financial in 2010. That combination, real LLC formation experience paired with a background specifically in retirement account law, is what a compliant agreement actually requires.
What's Included When We Draft Yours
- Customized Self-Directed IRA LLC design built around your specific investment plans
- State Articles of Organization filing
- A custom operating agreement built around IRC 408 and 4975
- EIN (tax ID) acquisition for the LLC
- IRS reporting on the IRA side, Forms 5498 and 1099-R
- Form 1065 and Form 990-T preparation when the LLC's structure requires them
- One-on-one guidance on disqualified persons and prohibited transaction questions
- A flat annual fee, with no per-transaction or asset-value charges
Final Thoughts
The operating agreement isn't paperwork you file away and forget. It's the document your custodian, your bank, and, if it ever comes to it, the IRS will all look to when a question comes up about how your Self-Directed IRA LLC is supposed to work. Getting it right at formation, with the IRA-specific restrictions actually built in rather than bolted on as an afterthought, is a lot easier than trying to fix it once money has already moved.
If you're setting up a Self-Directed IRA LLC for the first time, or you're looking at one you formed a few years ago and aren't sure it still reflects the current rules, that's worth a closer look before your next transaction rather than after.
Venture Capital Investments with a Solo 401(k)
The advantage of purchasing venture capital funds with retirement funds is the ability to gain tax advantages, such as tax-deferral or tax-free growth on income or gains the investment generates. A self-directed retirement plan, such as the Solo 401k plan, gives you the freedom to purchase venture capital funds with a checkbook control structure.
Buying Venture Capital Funds with Retirement Funds
Many successful companies, such as Google and Amazon have been funded and grown from venture capital investments. Venture capital investments are a high reward/high-risk investment. A venture capital firm may fund 10 companies, but only one needs to be successful to yield high rewards.
For example, Facebook’s $22 billion acquisition of WhatsApp in 2014 was (and still is) the largest private acquisition of a venture capital-backed company. It was also a big win for Sequoia Capital, the company’s only venture investor, which turned its $60 million investment into $3 billion.
Venture capital investments with a Solo 401(k) or IRA are seen as a tax-attractive option because the gains from the investment would generally flow back to the retirement account without being subject to tax. Additionally, in the case of a Roth Solo 401(k), the income or gains have the potential to fully be tax exempt.
What is Venture Capital?
Venture capital is financing that investors provide to new start-ups and small businesses that are believed to have great potential. Venture capital generally comes from:
- Accredited investors
- Family offices
- Any financial institution
Venture capital funds generally make money by charging a small fee for managing the fund (typically around 2%) and then taking a cut of the gains from the investments above a certain set threshold. This is known as the carried interest and is typically 20%.
The fees associated with investing in a venture capital fund are steeper than investing in a mutual fund or ETF, but the hope is that the returns will more than make up for the associated costs.
What is the difference between venture capital and private equity?
Venture capital and private equity investments are very similar. However, venture capital typically invests in early-stage companies with no revenue. Private equity invests in mature companies generating revenue but needs to be revitalized.
Both private equity and venture capital funds typically raise money from wealthy accredited investors, family offices, banks, financial institutions, other investment funds, pension funds, and even IRAs.
Venture Capital Investments with a Solo 401(k)
With a Solo 401(k) retirement plan, the business owner or plan participant (you) can serve as trustee. As a result, you can make private equity investments simply by writing a check or wiring funds directly from the Solo 401(k) bank account, which can be opened at any local bank or credit union, such as Capital One.
By establishing a Solo 401(k), you can make private equity investments without the formation of an LLC. Instead, the Solo 401(k) Plan can be adopted by any business including a sole proprietorship, LLC, C Corporation, S Corporation, or partnership.
Unlike a conventional Solo 401(k) Plan that can be opened at a traditional financial institution such as Fidelity, the Solo 401(k) Plan offered by the IRA Financial Group is open architecture and 100% self-directed. This provides you (the trustee) with "checkbook control" over the 401k plan assets and 100% control over the investments of the plan.
With the Solo 401(k), also known as a Self-Directed 401(k), you will have total control over your retirement funds so you can make private equity and 401k plan investments tax-free.
Solo 401(k) Prohibited Transaction Rules
You can use a Solo 401(k) for venture capital investments, but you must be aware of the IRS prohibited transaction rules under Internal Revenue Code Section 4975
The IRS has restricted certain transactions between the Solo 401k Plan and a “disqualified person.” Disqualified persons include, but are not limited to the IRA holder and any of his/her lineal descendants.
The prohibited transactions rules tend to become more of an issue when the person using the retirement funds or another disqualified person related to the retirement account holder has a personal interest or relationship with the venture capital fund investment. In other words, a retirement account holder can generally make an investment into any venture capital fund in which neither the retirement account holder nor any disqualified person has any personal ownership or relationship with.
Issues will arise from an IRS prohibited transaction standpoint when the retirement account holder wishes to use retirement funds to invest in a fund where he/she or a disqualified person is either an owner, executive or, in some cases, has a professional relationship with the fund in question.
If structured correctly, there may be a way to use your retirement funds to invest in a venture capital that you are personally involved in. The key is to make sure that the retirement account investment into the fund will not personally benefit you (directly or indirectly) or any disqualified person since that type of investment would likely trigger a prohibited transaction.
Triggering a prohibited transaction is based on the facts and circumstances involved. You must prove that you did not personally benefit from the retirement account investments (directly or indirectly). Failure of proof can trigger very steep taxes and penalties.
Putting it All Together
Venture capital investments are one of the more popular investment options for a Solo 401(k) plan. Venture capital investments are generally high risk/high reward investments, but typically do not involve much prohibited transaction risks, assuming you or any disqualified person is actively involved in the fund.
Why IRA Financial
IRA Financial has helped over 15,500 self-directed IRA investors invest over $4.5 billion in alternative assets. IRA Financial has significant experience assisting venture capital clients navigate the IRS rules in connection with all types of domestic and foreign investments.
For additional information on using a self-directed IRA to make venture capital investments, please contact one of our Solo 401k Experts at 800-472-0646.
What is a Checkbook Control IRA?
A checkbook control IRA is a Self-Directed IRA that owns a limited liability company, with you serving as the LLC’s manager. Instead of asking a custodian to approve and process every investment, you write a check or send a wire from the LLC’s bank account yourself. I’ve been setting up these structures since 2010, and for investors in real estate and other alternative assets, the speed and control they offer can make the difference between closing a deal and losing it. That control also puts the responsibility for following the IRS rules squarely on you.
Key Takeaways
- A checkbook control IRA is a Self-Directed IRA that owns an LLC, which you manage and invest through directly.
- The structure is rooted in Swanson v. Commissioner (1996), where the Tax Court sided with an IRA that invested through an entity.
- You can invest without custodian approval for each transaction, which speeds up real estate closings and private deals.
- As manager, you’re responsible for avoiding prohibited transactions and keeping all IRA money inside the LLC.
- At IRA Financial, a Checkbook IRA costs $999 to set up and $495 a year, with no fees based on asset value.
How a Checkbook Control IRA Works
A traditional Self-Directed IRA is held by a custodian, and the custodian has to review, sign, and fund every investment you make. That works, but it can be slow, especially when a seller wants earnest money today or a private deal closes on a tight deadline. Each transaction can also come with its own custodial fee.
A checkbook control IRA adds one layer. Your Self-Directed IRA, held with a passive custodian, invests in a newly formed LLC. The IRA is the LLC’s sole member, and you are its manager. The LLC opens a business checking account at a local bank, and once the IRA funds the LLC, you can make investments directly from that account. Rental income, interest, dividends, and sale proceeds flow back into the LLC’s account, where they continue to grow tax-deferred, or tax-free in a Roth IRA.
The legal foundation for the structure goes back to Swanson v. Commissioner, 106 T.C. 76 (1996). In that case, the IRS argued that an IRA’s investment in a newly formed company owned by the IRA was a prohibited transaction. The Tax Court disagreed and found that a newly formed entity with no other owners isn’t a disqualified person when the IRA makes its initial investment. That reasoning is why an IRA can form and fund its own LLC today.
Benefits of a Checkbook Control IRA
Speed. You can make an investment the moment you decide to, without waiting days for a custodian to review the documents. In competitive real estate markets, that matters.
Control. You sign the contracts, pay the bills, and deposit the income. No one at a custodian has to sign off on a repair invoice or a property tax payment.
Lower transaction costs. Many custodians charge fees for each transaction, each asset held, or a percentage of account value. With the LLC handling day-to-day activity, those per-transaction fees largely go away.
Diversification. You can invest in assets most brokerage firms won’t touch, and move between them as opportunities come up.
Privacy. Investments are made in the LLC’s name, not in a custodian’s name for the benefit of your IRA.
What You Can Invest In With a Checkbook Control IRA
The IRS doesn’t publish a list of approved IRA investments. It lists what’s prohibited, which is mainly life insurance and most collectibles, and everything else is generally allowed. With a checkbook control IRA, that can include:
Book a free call with a checkbook control IRA specialist
- Review your self-directed retirement options
- Learn about investing in alternative assets
- Get all of your questions answered
- Real estate, including residential, commercial, and raw land
- Private businesses and private placements
- Tax liens and tax deeds
- Hard money loans and private mortgages
- Gold and other IRS-approved precious metals
- Cryptocurrency
- Foreign currency, commercial paper, and promissory notes
- Livestock and farming operations (I’ve had clients invest in alpaca farms)
- Publicly traded stocks, ETFs, and mutual funds
Most large brokerage firms limit IRA investors to stocks, bonds, and funds because that’s what they sell. The rules themselves are much broader.
How to Set Up a Checkbook Control IRA
- Open a Self-Directed IRA. The account is held with a passive custodian. You can use a traditional IRA, a Roth IRA, or a SEP IRA.
- Fund the account. Move money in through a transfer from another IRA, a rollover from a former employer’s plan, or an annual contribution. A direct transfer or rollover is tax-free.
- Form the LLC. The LLC is formed with an operating agreement written for IRA ownership, which names the IRA as the member and you as the manager. The LLC also gets its own EIN.
- Open the LLC bank account. The account is opened in the LLC’s name at a bank of your choosing.
- Fund the LLC. At your direction, the custodian invests some or all of your IRA funds into the LLC in exchange for 100% of its membership interest.
- Invest. As manager, you make investments directly from the LLC’s account, and all income and gains return to that account.
At IRA Financial, our team handles the full setup, including the LLC formation, EIN, and operating agreement. Most accounts open within one to three business days after we receive your documents, and the full process, including funding and your first investment, usually takes about three to four weeks, depending on how long the incoming transfer takes.
What a Checkbook Control IRA Costs
At IRA Financial, a Checkbook IRA costs $999 to set up, which covers the LLC formation, EIN, and operating agreement, and then $495 a year. There are no fees based on how much your account holds or how many transactions you make. You’ll also pay your state’s LLC filing fee and any annual state LLC fees, which vary by state.
I built IRA Financial around a flat fee because I’ve never understood why an IRA owner should pay more just because their real estate went up in value. With a checkbook control IRA, your costs stay the same whether the account holds $50,000 or $5 million.
Your Responsibilities as LLC Manager
The control that makes this structure valuable also means no custodian is double-checking your transactions. The IRS prohibited transaction rules under Internal Revenue Code Section 4975 apply to everything the LLC does. As manager, you can’t:
- Buy property from, sell property to, or lend money to yourself, your spouse, your parents, your children and grandchildren, or entities they control
- Use any LLC-owned asset personally, including vacation properties
- Pay yourself a salary or fee for managing the LLC or working on its investments
- Personally guarantee a loan for the LLC
- Mix personal funds with LLC funds, or pay LLC expenses from your own account
A prohibited transaction can disqualify the entire IRA as of January 1 of the year it happened, which makes the full balance taxable. In Ellis v. Commissioner, 787 F.3d 1213 (8th Cir. 2015), an investor used an IRA-owned LLC to buy a used car business and then had the business pay him a salary. The court didn’t question the LLC structure itself. The problem was the salary, and it cost him his entire IRA. I cover more of these rulings in my summary of landmark prohibited transaction cases.
Good recordkeeping is part of the job. Keep a separate ledger for the LLC, save every invoice and closing statement, and send your custodian an updated value of the LLC’s assets each year so it can report the account’s fair market value on Form 5498.
Is a Checkbook Control IRA Right for You?
A checkbook control IRA makes the most sense if you plan to invest in real estate, make several alternative investments a year, or need to act quickly on deals. If you only plan to make one passive investment, such as a single private fund, a standard Self-Directed IRA may be all you need. If you’re self-employed with no full-time employees, a Solo 401(k) with checkbook control offers the same control plus higher contribution limits and an exemption from UDFI on leveraged real estate.
Final Thoughts
A checkbook control IRA gives you the freedom to invest your retirement funds the way you’d invest your own money, quickly and in the assets you know best. It’s been on solid legal ground since the Swanson decision, and thousands of investors use it to buy real estate, lend money, and back private companies. It also asks more of you than a traditional IRA does. If you understand the prohibited transaction rules and keep clean records, the structure lets you take full ownership of your retirement investing.
This content is for educational purposes only and does not constitute legal, tax, or investment advice. Consult a qualified professional before making any investment decisions.
Are IRA Custodian Fees Tax Deductible?
What are IRA Custodian Fees?
If you have an IRA, you may see IRA custodial fees. Essentially, an IRA custodial fee is an administrative fee you pay to the IRA custodian. This fee keeps your retirement account open. However, such fees are less common among Self-Directed IRAs. Additionally, if you have a Self-Directed IRA, your custodial fees may be tax-deductible.
Are your Self-Directed IRA Custodial Fees Tax-Deductible?
The Tax Cuts and Jobs Act of 2017 nearly doubled the standard deduction and eliminated or restricted many itemized deductions in 2018 through 2025. Accordingly, the ability to generate an itemized tax deduction for the payment of IRA fees is no longer available beginning in 2024.
The IRA Financial Solution
IRA Financial understands that because Self-Directed IRA fees are no longer tax deductible, making sure our self-directed IRA clients are not overpaying for their annual Self-Directed IRA custodian fees. To this end, IRA Financial has been fixated on making sure our Self-directed IRA fees are as low as possible and 100% flat.
IRA Financial has flat annual self-directed IRA custodian fees. We do not charge any asset valuation or transaction fees. Whether you have $25,000 or $250,000, you will pay the same one-time low flat annual fee. We strongly believe that since the account is a “self-directed” account and is managed by you, IRA Financial should not receive more fees simply because you were a successful investor. That seems almost unfair. We are the ONLY self-directed retirement provider that does not charge any check or inbound wire fees.
Custodial Fees For Your IRA
It is important to note that Self-Directed IRA Custodian fees are not considered part of the total IRA contribution for the year. On the other hand, IRS rules further provide that if you pay IRA administrative/management expenses directly from the IRA, this payment will not be considered a distribution from the IRA.
For example, let’s assume you contribute the maximum for someone under age 50 to a Self-Directed IRA in 2026, which is $7,500. Then, the IRA custodian deducts $125 from the account for quarterly custodial fees. The IRA custodian fee you pay will not be seen as a distribution. Additionally, it will not increase the IRA contribution to compensate for that amount.
Therefore, an IRA account owner has two choices:
- Pay custodian fees with the money in a retirement account (this is subtracted directly from the account without tax consequences).
- Pay the fee with outside/personal dollars, which is not subject to an itemized deduction.
Investment Management or Transaction Fees
The same predicament falls on a retirement account holder subject to investment management or transaction-related fees with their Self-Directed IRA. The IRS in a private letter ruling affirmed that “wrap fee”-style arrangements, such as ongoing asset under management and investment advisory fees can be paid with outside taxable dollars or paid using IRA funds.
Real Estate & Investment Fees
In the case of a real estate or other investment transaction that an IRA invests in, the IRS prohibited transaction rules under Internal Revenue Code Section 4975 requiring the IRA to pay the fees associated with the IRA investment. For example, real estate tax, property maintenance fees, or related service fees should always be paid using IRA funds. The use of funds to pay fees or expenses associated with an IRA investment from the IRA owner of any “disqualified person” in this context is not permitted. Pursuant to Internal Revenue Code Section 4975, a “disqualified person” is generally defined as the IRA holder and any of his or her lineal descendants and/or any entities controlled by such persons. Note – siblings are not considered “disqualified persons.”
Paying Self-Directed IRA Fees Using IRA Funds vs Personal Funds
In general, one can pay Self-Directed IRA custodian fees and similar investment advisory fees from retirement accounts. The primary benefit to paying the IRA custodian fees and management fees from a retirement account is the ability to pay it with pretax dollars. By definition, the retirement account is pretax. In contrast, paying fees with after-tax Roth funds is generally not the best option. Overall, even though one is no longer able to get an itemized tax deduction for the payment of IRA fees, it still makes tax sense to generally pay for IRA fees using personal funds. By paying fees out of personal funds, you are preserving the tax deferral or tax-free benefits of the IRA account. This allows the IRA to maximize its ongoing tax-deferred growth.
It’s almost always preferable to use personal funds (non-retirement funds) to pay the IRA custodian fee/investment management fee for a Roth IRA. The belief is that it is always better to pay with after-tax dollars from a taxable account than using future-tax-free growth from the Roth IRA itself.
Get in Touch
Do you still have questions about IRA custodial fees and management fees with a Self-Directed IRA that we didn't answer in this article? Please contact IRA Financial at 800-472-0646.
Invest in an S Corp with a Self-Directed IRA
The most popular reason millions of American IRA holders have turned to the Self-Directed IRA is to gain more control and investment options. The ability to gain investment diversification and invest in a wide variety of assets in a tax-deferred or tax-free manner, is very attractive. However, are you allowed to invest in an S corp with your IRA funds? Read more to find out.
- A Self-Directed IRA allows one to diversify their retirement portfolio
- S Corps are a type of business entity that is taxed at the shareholder level
- An IRA cannot directly invest in an S Corp, but there are some workarounds. The prohibition of an IRA from investing in an S Corporation is an S Corporation based on IRC Section 1361 rule and not an IRA prohibited transaction rule
Investments Allowed with a Self-Directed IRA
The Internal Revenue Code do not describe what an IRA can invest in, only what it cannot invest in. It boils down to three types of investments you can't do with IRA funds. Number one, you cannot invest in life insurance. Secondly, you cannot invest in collectibles, including art, stamps, and antiques. Lastly, you cannot invest in a transaction that includes a disqualified person.
To the last point, essentially, any investment made with IRA funds must "exclusively benefit" the IRA itself. A disqualified person, which includes you and your spouse, any lineal descendants and ascendants, their spouses, and any entities controlled by such, cannot benefit from the IRA-held investment.
Therefore, so long as no disqualified person is involved, and the investment is not prohibited by the IRS, you can do it. Investments include real estate, precious metals, and even S corps.
What is an S Corp?
S corps are corporations that elect to pass corporate income, losses, deductions, and credits through to their shareholders for federal tax purposes. Shareholders of S corps report the flow-through of income and losses on their personal tax returns, and are assessed tax at their individual income tax rates. This allows S corporations to avoid double taxation on the corporate income. S corporations are responsible for tax on certain built-in gains and passive income at the entity level.
C Corp vs. S Corp
A corporation (sometimes referred to as a C corporation) is an independent legal entity owned by shareholders. This means that the corporation itself, not the shareholders that own it, is held legally liable for the actions and debts the business incurs.
One of the major disadvantages of a C Corp is taxation. C Corps are required to pay federal, state, and in some cases, local taxes. When you form a corporation, you create a separate tax-paying entity. C Corps are known has having two layers of tax: (i) a corporate level, which is currently 21%, and (ii) a shareholder tax, which is subject to tax on corporate dividends received.
Whereas, an S corporation is treated as a pass-through entity, such as an LLC, for federal income tax purposes. All S corp items of income, loss, deductions "pass through" to the shareholders and reported on their federal income tax returns.
S Corp Requirements
To qualify for S corporation status, the corporation must meet the following requirements:
- Be a domestic corporation
- Have only allowable shareholders
- Have no more than 100 shareholders
- Have only one class of stock
- Not be an ineligible corporation (i.e. certain financial institutions, insurance companies, and domestic international sales corporations).
In sum, the S Corp have very specific shareholder restrictions. For example, corporations, foreigners, and only certain trusts can be shareholders of an S corp. Unfortunately, an IRA is not a permitted shareholder of an S corp. In addition, a single member LLC, owned by an IRA, is also not a permitted S corp shareholder since the LLC is a pass-through entity.
However, a 401(k) plan is technically a permitted trust that can be a shareholder of an S corp. Although, the issue with a 401(k) plan owning S corp stock is that any pass-through income exceeding $1,000 could trigger the UBTI tax, which has a maximum tax rate of 37%.
Unlike an S Corp, C Corps, LLCs, and partnerships do not generally have any shareholder restrictions.
How can a Self-Directed IRA Invest in an S Corp?
Now that we know that an IRA cannot be a shareholder of an S corp, what can an investor do who wants to use an IRA to buy S corp stock? Here are a few options:
Revoke the S Corporation Election
A C corp may revoke the S election. To revoke a sub-chapter S election/small business election that was made on Form 2553, submit a statement of revocation to the service center where you file your annual return. The statement would need to include certain information about the corporation.
If revoking effective the first day of the tax year, the revocation is due by the 16th day of the third month of the tax year. Whereas, if revoking effective any day other than the first day of the tax year, the revocation must be received by IRS by the requested effective date.
By revoking the S election, the corporation reverts back to a C Corp and the two layers of taxation.
Debt vs. Equity Investment
An IRA investor can elect to lend funds to the S corp versus making an equity investment. The downside of a loan investment is that the IRA will simply be a lender to the S corp and not a shareholder. Hence, the IRA will not share in any of the upside equity value of the corporation.
However, a loan with favorable rates could yield a decent return for your IRA. Of course, the profits will be limited.
Conclusion
The S corp shareholder limitation rules are often viewed as irrational as well as frustrating. The fact that an IRA can invest in a C Corp or an LLC, but not an S corp, often infuriates investors. Nevertheless, it is important to remember that these S corp shareholder restrictions are based on rules in the tax code and not IRA tax rules.
You do have options when it comes to investing in an S corp with a Self-Directed IRA, however, they are limited. Before investing, speak with a financial advisor to see if it's the right deal for you. Never settle when it comes to investing in your future!
Correcting a Prohibited Transaction
When using a Self-Directed IRA or Solo 401(k) plan to make alternative investments, you must pay attention to all the rules set forth by the IRS. Arguably, the most important of these rules are the prohibited transaction rules. While the IRS does not say what you are allowed to invest in with retirement funds, it does outline what you absolutely cannot invest in. These include life insurance, antiques, many collectibles, and certain coins. In addition to these items, you also may not take part in a transaction involving a disqualified person. Disqualified persons include you, your spouse, and all lineal ascendants and descendants and their spouses. Correcting a prohibited transaction is technical, but fairly easy to correct. You must do so in a timely matter, however.
What is a Prohibited Transaction?
The Prohibited Transaction Rules can be found in Internal Revenue Code 4975. There are three types of prohibited transactions: Direct/Indirect, Self-Dealing, and Conflict of Interest. These apply to both IRAs and 401(k) plans. They're in place so you don't get a personal advantage in addition to the tax benefits of the plan. Here's quick summary of each one:
- Direct/Indirect - This is a transaction between a disqualified person and his or her retirement account. For example, using your Self-Directed IRA to purchase a house that you then lease to your daughter Since your daughter is a lineal descendant, this is a prohibited transaction.
- Self-Dealing - You cannot personally gain by the investments made by your plan. Your retirement plan is already tax-advantaged, therefore you cannot also personally gain from it. An example is when you want to personally own a real estate property, but you use funds from your 401(k), in addition to personal funds, to make the purchase. Since this benefits you personally, it is prohibited. Here's another example: You invest in your son's business with your Self-Directed IRA. Since, your son is a disqualified person, this is not allowed.
- Conflict of Interest - This involves a disqualified person who is also a fiduciary and is connected to a transaction that involves the income or assets of the individual’s IRA. Here's an example: You take a loan from your Solo 401(k) plan and invest it in a business you manage and also have an ownership stake in. Since you are the fiduciary, there is a conflict of interest in the investment.
These are just a few examples of the prohibited transaction rules.
Penalties for Engaging in a Prohibited Transaction
Failure to abide by these laws come with serious consequences for your retirement plan. Typically, the penalty starts out at 15% for most retirement plans. However, Self-Directed IRAs are treated more harshly.
If you or your beneficiary of the IRA engages in a prohibited transaction, the IRA will lose its tax-exempt status. The entire fair market value (FMV) of the IRA will then be treated as taxable distribution and be subject to ordinary income tax. Furthermore, the IRA holder (or beneficiary) is subject to a 15% penalty, plus the 10% early distribution penalty if the IRA holder (or beneficiary) is under the age of 59 1/2.
If you have a Solo 401(k) and engage in a prohibited transaction, the penalty is 15% of the amount involved. The IRS allows for some time to pay this tax and fix the transaction. Failure to do so will lead to an additional 100% penalty of the amount involved.
Correcting a Prohibited Transaction
Basically, to correct a prohibited transaction within a retirement account, you must undo it as soon as reasonably possible. A frequent one that occurs is when you sell an investment held by your Self-Directed IRA and the funds go directly to you (or to a different IRA and custodian). Since they didn't first go to the original custodian, this constitutes a prohibited transaction. To correct this, you (or the new custodian) would need to send the funds back to the investment. In turn, the investment would then send them to the correct IRA and custodian. You may then choose what to do with the funds.
Correcting a prohibited transaction is not always that simple. The rules set forth by the IRS are quite complicated. For example, if real property was involved (say you sold a 401(k)-owned property to your father), you would first need to rescind the sale. If any income was earned using the property, it must also be returned to the plan.
Final Take
Navigating the complicated IRS Prohibited Transaction rules is quite difficult, even for experts. Self-directed retirement plans allow for numerous types of investment that can be made with just about anyone. However, when family is involved, you must tread lightly.
The content laid out here is just a "Cliff notes" version of all the nuances associated with these rules. It's best to deal with professionals, who know the law backwards and forwards, before engaging in a transaction that might not be allowed by the IRS. The last thing you want is to be hit with a huge penalty, on top of a huge tax bill if your Self-Directed IRA is deemed "distributed" because of a mistake. Correcting a prohibited transaction can be done, but help will generally be needed.
Contact Us
If you have any questions about the prohibited transaction rules, please contact us @ 800.472.0646!
How to Use a Self-Directed IRA to Invest in Forex
One of the primary reasons millions of Americans have turned to a Self-Directed IRA as the investment vehicle of choice for their retirement funds is the ability to have greater investment control. Gaining the ability to invest IRA funds into assets outside of equities is viewed as a great way to diversify one’s retirement savings as well as a hedge against rising prices and inflation. Forex, or foreign currency trading, is an alternative investment option that several Self-Directed IRA investors have explored.
- Investing in foreign currency has become popular among retirement savers
- Using a Self-Directed IRA LLC is the best way to invest in Forex
- Know the risks before you start investing
What is Forex?
Forex, also known as foreign exchange or FX trading, is the conversion of one currency into another. It is one of the most actively traded markets in the world, with an average daily trading volume of $5 trillion.
Forex is traded 24 hours a day, 5 days a week by banks, financial institutions, and individual traders worldwide. Unlike other financial markets, there is no centralized marketplace for Forex; currencies trade over the counter in whatever market is open at that time.
Trading Forex involves the buying of one currency and the simultaneous selling of another. In Forex, traders attempt to profit by buying and selling currencies by actively speculating on the direction currencies are likely to take in the future. For example, a Self-Directed IRA trader may buy Euros and sell U.S. dollars or may buy Canadian dollars and sell British pounds. Forex investing is somewhat risky because of the 24-hour-a-day, 5-day-a-week marketplace.
What is a Self-Directed IRA?
A Self-Directed IRA is not a term you will discover in the Internal Revenue Code. In essence, it is an IRA account in which the IRA custodian allows the IRA to be invested in alternative assets, such as real estate or Forex. A Self-Directed IRA follows the same tax rules as a traditional IRA. The sole distinction is that a Self-Directed IRA can invest in alternative assets.
Benefits of Forex Trading in a Self-Directed IRA
Diversification: Investing in foreign currencies can provide a unique opportunity. Unlike other investments, such as stocks and bonds, forex trading in an IRA can help diversify your retirement and better prepare you for a market downturn.
Ease of Trading: Since Forex trading is international, you can trade Forex in your IRA 24 hours a day, five days per week.
Transaction Costs: Forex trading tends to have lower transaction costs. However, these costs may vary based on the chosen provider.
Profits: An individual who understands Forex trading will know that there are potential profits that flow back to your IRA when the international markets fluctuate.
Taxes: With a Self-Directed IRA you can avoid paying taxes on your gains. Since all trading is done within your IRA, your profits flow back to the IRA tax-free!
Self-Directed IRA Forex Options
There are two ways to use a Self-Directed IRA to invest in Forex.
The Self-Directed IRA
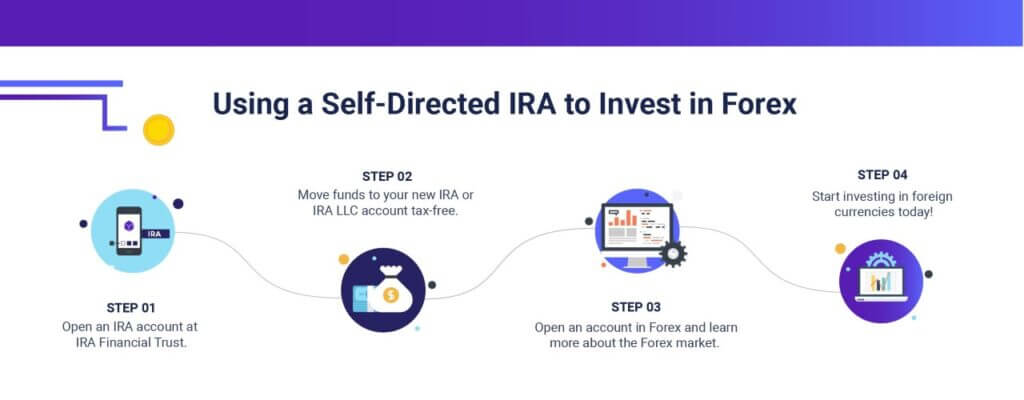
A Self-Directed IRA offers an IRA investor more investment options than stocks sold at a traditional financial institution. With a Self-Directed IRA, a special IRA custodian, such as IRA Financial, will serve as the custodian of the IRA.
Unlike a typical financial institution, most IRA custodians generate fees simply by opening and maintaining IRA accounts and do not offer any investment products or platforms. In the case of a Self-Directed IRA, the funds are generally held with the IRA custodian, and at the IRA holder’s sole direction, the IRA custodian will then invest those funds into alternative asset investments, such as foreign currency.
Self-Directed IRA LLC
The Self-Directed IRA LLC with “checkbook control” has quickly become the most popular vehicle for investors looking to make alternative assets investments where the IRA owner is seeking a high degree of control.
Under the Checkbook IRA LLC set-up, a limited liability company (“LLC”) is established, which is funded and owned by the IRA, and managed by the IRA owner. The Checkbook IRA LLC structure allows the investor to act quickly when the right investment opportunity presents itself cost-effectively and without delay.
The Checkbook IRA LLC also offers a greater degree of privacy than the standard Self-Directed IRA since the IRA investment is made in the name of the LLC versus in the name of the IRA. In addition, using an LLC owned by the IRA provides limited liability protection to the IRA owner on all IRA assets owned outside of the LLC.
Most foreign currency exchange institutions will not allow an IRA to be the owner of the account directly. Hence, the use of a Self-Directed IRA LLC is typically the most common vehicle used to invest in foreign currency.
Tips to Use a Self-Directed IRA to Invest in Forex
- Do your research on the Forex company you will be using
- Understand that the Forex market is 24 hours and 5 days a week
- Forex investing can be highly profitable but also extremely volatile and risky
- You will likely need to establish a Self-Directed IRA LLC to invest in foreign currency
- All gains from the Forex investments will go back to the IRA without tax
- If you use margin to buy foreign currency, the loan cannot be personally guaranteed by the IRA owner. In addition, the use of margin could trigger the UBTI tax.
Conclusion
Using a Self-Directed IRA to invest in foreign currency investments could help better diversify your IRA savings, as well as allow you to generate tax-deferred (or tax-free with a Roth IRA) gains. Forex investments are risky and volatile, and one should do his or her research before investing retirement funds in foreign currency.
