

How a Self-Directed IRA LLC Acts as Your Private Family Office
For decades, the term "family office" was reserved for the ultra-wealthy. It represented a private firm dedicated entirely to managing the investments, tax strategy, and legacy of a single high-net-worth family. While most Americans were choosing between a handful of mutual funds at their local bank, wealthy families were quietly buying private companies, commercial real estate, and stakes in emerging technologies.
What most people do not realize is that the structural advantages of a family office are no longer exclusive to billionaires. Through a Self-Directed IRA with Checkbook Control, also known as a Self-Directed IRA LLC, individual investors can access the same investment flexibility, the same speed of execution, and the same breadth of asset classes that family offices have used for generations, all within a tax-advantaged retirement account.
What a Family Office Actually Does
A family office is essentially a private wealth management entity that handles everything: investment strategy, tax planning, estate management, and long-term legacy planning. The defining characteristic is unrestricted access. Family offices do not limit themselves to publicly traded stocks and bonds. They invest in private businesses, real estate, physical assets like gold, and private credit arrangements. They look for opportunities in places that retail investors typically cannot reach.
Historically, you needed between $50 million and $100 million in assets to justify the cost of running a family office. The legal infrastructure, staffing, and compliance overhead made it impractical for anyone below that threshold. That calculus has changed.
What a Self-Directed IRA Actually Is
Most people think of an IRA as a product you purchase from a brokerage like Schwab or Fidelity. It is not. An IRA is a tax status granted by the IRS. The account itself can hold virtually any asset permitted under the tax code.
A Self-Directed IRA is simply an IRA where the custodian allows you to invest across the full universe of legally permitted assets rather than limiting you to whatever is available on their platform. Through a true Self-Directed IRA, your retirement funds can be invested in residential and commercial real estate, private equity, private credit through promissory notes, digital assets like Bitcoin and Ethereum, and physical precious metals.
This is the foundation of the family office model applied to retirement investing. It moves your wealth beyond publicly traded securities and into assets you understand and can evaluate on your own terms.
Checkbook Control: How It Works
If the Self-Directed IRA is the foundation, Checkbook Control is what makes it fully functional as a family office structure. Technically known as the IRA LLC structure, it is the mechanism that shifts you from a passive account holder to an active decision-maker.
The structure works in four steps. First, you open a Self-Directed IRA with a qualified custodian. Your IRA then purchases 100% of the membership interest in a newly formed LLC. You are appointed as the manager of that LLC. And your IRA funds are wired into a dedicated bank account held in the name of the LLC.
The practical result is significant. When you want to make an investment, you do not need to contact your custodian, submit paperwork, and wait for approval. You write a check or send a wire directly from your LLC bank account. Investment decisions happen in real time, which matters enormously in private markets where the best opportunities move quickly.
Is This Legal?
Some advisors describe the Checkbook IRA structure as a gray area. It is not. The legality was settled in the landmark Tax Court case Swanson v. Commissioner in 1996.
The IRS argued that an investor could not serve as manager of an LLC owned by their IRA without triggering a prohibited transaction. The Tax Court disagreed, ruling clearly that a newly formed LLC is not a disqualified person and that the account owner can manage the entity without violating IRS rules.
The reason this structure is not more widely known has nothing to do with legality. It has to do with economics. Traditional custodians and brokerages generate revenue through transaction fees and asset-based charges. A Checkbook IRA eliminates most of those fees, which means it was never in their interest to promote it.
Book a free call with a self-directed retirement specialist
- Review your self-directed retirement options
- Learn about investing in alternative assets
- Get all of your questions answered
The Practical Advantages
Running retirement assets through a Checkbook IRA LLC provides three meaningful advantages over a standard brokerage IRA.
The first is speed. Private market opportunities do not wait for compliance departments. A distressed property at auction, a private equity round closing on a Friday, a time-sensitive lending opportunity: these require the ability to act immediately. With Checkbook Control, you can move as quickly as any other buyer in the market.
The second is cost efficiency. Traditional Self-Directed IRA custodians often charge per-asset or per-transaction fees. If you are managing multiple rental properties and several private loans, those fees compound quickly and reduce your overall return. The LLC structure typically involves a single flat custodian fee, with all transactions within the LLC incurring no additional charges.
The third is investment integration. Through a single LLC, you can hold both traditional and alternative assets together. A portion of the account can be invested in stocks and ETFs through a linked brokerage, while the same LLC holds real estate, private equity, or digital assets. Everything is managed from one unified structure.
Two Investors, One Opportunity
Consider how two investors approach the same real estate opportunity in 2026.
The first investor uses a standard brokerage IRA. They identify a local rental property priced at $200,000 that fits their investment criteria. Their brokerage does not offer real estate as an investment option, so the opportunity passes. Their retirement account remains entirely in publicly traded securities.
The second investor uses a Self-Directed IRA with Checkbook Control. They write a check for the down payment directly from their LLC bank account, secure a non-recourse loan for the balance, and close on the property. Each month, the rental income is deposited directly into the LLC. When the property is eventually sold at a gain, and the account is structured as a Roth IRA, both the rental income and the capital gain are completely tax free.
Same opportunity. Very different outcomes.
Why I Built IRA Financial Around This Structure
I spent years as a tax attorney before founding IRA Financial, and what I kept seeing was a gap between what the tax code actually permits and what most Americans were being offered by their financial institutions.
The Checkbook IRA structure is not a loophole or a workaround. It is a straightforward application of settled tax law that gives individual investors the same structural tools that wealthy families have used for decades. The reason most people do not know about it is not complexity. It is that the financial industry has never had a strong incentive to explain it.
At IRA Financial, we provide the legal documentation, state filings, compliance infrastructure, and ongoing support that make this structure work correctly. Getting the setup right matters, and having the right team behind it matters just as much.
Final Thoughts
A Self-Directed IRA LLC does not just expand your investment options. It fundamentally changes your relationship with your retirement account. Instead of choosing from a limited menu of products curated by a financial institution, you are making direct investment decisions across a broad range of asset classes, with the full tax advantages of a retirement account intact.
The family office model has always been about control, flexibility, and access. For the first time, those advantages are available to investors at every level, not just those with eight-figure portfolios.
If you want to understand whether this structure makes sense for your situation, IRA Financial offers free consultations with retirement specialists who can walk you through the setup and help you evaluate your options.

What is a Self-Directed IRA Custodian?
The Self-Directed IRA custodian is one of the most important decisions you will make when starting a plan. Not all custodians are the same. A lot depends on what you want to invest in, how hands-on you want to be, and how much you want to spend. Different custodians offer different services, and fee structures vary based on the type of Self-Directed IRA you choose.
Key Takeaways
- Not all custodians allow the same types of investments. If you want to invest in real estate, crypto, or other alternatives, you’ll need a specialized Self-Directed IRA custodian.
- With a Self-Directed IRA, you make the investment decisions. That means you also need to do your research and follow IRS rules to avoid penalties.
- Look for a custodian with clear, flat fees and proven experience. Avoid custodians that charge based on your account value or offer limited support.
Understanding Self-Directed IRAs
A Self-Directed IRA (SDIRA) is a type of individual retirement account (IRA) that allows the account owner to invest in a broader array of assets compared to traditional IRAs. SDIRAs are designed for savvy investors who want to diversify their retirement portfolio with alternative investments, such as real estate, precious metals, and private placements. With a Self-Directed IRA, the account owner has direct control over the investments and can make decisions on how to manage the account.
SDIRAs are available as either traditional or Roth IRAs, and they offer the same tax benefits as "regular" IRAs. However, SDIRAs require greater initiative and due diligence by the account owner, as they are responsible for managing the investments and ensuring compliance with IRS rules.
What is an IRA Custodian?
A custodian is a financial institution that holds and safeguards assets on behalf of an individual or institution. In traditional banking, large institutions act as custodians for pension funds and asset managers. In the retirement space, custodians are required for all tax-advantaged accounts like IRAs.
Under Internal Revenue Code Section 408, you must set up an IRA at a bank, authorized financial institution, or state-regulated trust company. The custodian holds the account's investments for safekeeping, ensures the plan follows all IRS rules, and maintains the tax advantages of the account.
Without a custodian, individuals could potentially misuse retirement funds without proper reporting. The custodian provides the structure, reporting, and oversight that preserves the tax-deferred or tax-free status of the account. For example, if you invest IRA funds into real estate, the property must be titled in the name of the IRA, not your personal name. The custodian ensures the purchase is structured correctly and that all income and expenses flow through the IRA.
Custodian vs. Trustee
The terms custodian and trustee are often used interchangeably, especially in the IRA context. Technically, both serve as fiduciaries who hold assets for the benefit of another party. In practical terms, for most retirement accounts, the difference is minimal from the investor's perspective. What matters more is whether the institution allows for flexibility and self-direction.
What Does a Custodian Actually Do?
A custodian's responsibilities go far beyond simply holding assets. They serve as the administrative backbone of the account.
- Safekeeping of assets: The custodian maintains custody of financial assets, whether publicly traded securities or alternative investments. For retirement accounts, this ensures assets remain properly titled in the name of the IRA.
- Recordkeeping and reporting: Custodians track transactions, contributions, distributions, and asset values. They are responsible for issuing IRS forms such as Form 5498 for IRA contributions and Form 1099-R for distributions.
- Transaction processing: When an investor wants to buy or sell an asset inside a retirement account, the custodian processes the transaction according to the account holder's direction. In a self-directed structure, the investor makes the investment decision and the custodian executes it administratively.
- Compliance oversight: Custodians ensure transactions are processed within regulatory guidelines and help maintain the tax-advantaged status of the account by following IRS requirements. They do not provide investment advice.
- Asset valuation: Custodians maintain records of fair market value reporting, which is required annually for retirement accounts.
Why Do You Need a Special Custodian?
Not all Self-Directed IRA custodians are the same. You can go to virtually any bank or financial institution to open an IRA, but most traditional custodians will limit what you can invest in. Many only allow stocks and mutual funds. That is not because alternative investments are prohibited. It is because traditional institutions make their money by selling you financial products or holding your cash. They have no incentive to offer alternatives.
Many investors don't realize they have the legal ability to diversify beyond Wall Street products inside their retirement accounts. A specialized Self-Directed IRA custodian, such as IRA Financial, makes that possible by allowing investments in real estate, precious metals, cryptocurrency, hedge funds, and more.
Self-Directed IRA custodians make their money by setting up and administering the plan, not by selling you products. They do not provide investment advice. They maintain the plan and give you the freedom to invest in what you choose. Of course, you should always consult with a financial advisor to ensure your investments fit your personal goals.
Traditional Custodians vs. Self-Directed Custodians
Traditional custodians limit investments to publicly traded securities. A self-directed custodian allows investors to allocate retirement funds into alternative assets. The custodian does not recommend investments. They administer the account and process transactions based on your instructions.
https://youtu.be/iDuZsbmg9TQ
What a Custodian Does Not Do
It is equally important to understand what a custodian does not do.
A custodian does not perform due diligence on your investment, guarantee performance, or evaluate whether a deal is a good one. That responsibility falls entirely on you as the investor. This is especially true in self-directed accounts. With greater freedom comes greater responsibility. Investors must understand prohibited transaction rules, disqualified persons, and other IRS regulations before moving forward with any investment.
Custodian Fees and Services
When selecting a Self-Directed IRA custodian, understanding the fee structure is essential. Fees can vary widely across providers.
Common fees to be aware of include:
- Setup fees: Charged when opening a new Self-Directed IRA account
- Annual fees: Charged to maintain the account each year
- Transaction fees: Charged for each transaction such as buying or selling an investment
- Asset-based fees: Some custodians charge a percentage of your account value, meaning your fees grow as your investments grow
At IRA Financial, we believe you should never pay asset valuation fees. Successful investments should not result in higher fees. There should be one flat fee to maintain the plan regardless of account balance, with no minimum balance requirement. Self-directed plans are not just for the wealthy, and the fee structure should reflect that.
Risks and Challenges of Self-Directed IRAs
Self-Directed IRAs offer the potential for higher returns and greater diversification, but they also come with unique risks worth understanding before getting started.
- Investment risk: Alternative assets can be more volatile or complex than traditional investments, and performance is never guaranteed.
- Lack of liquidity: Some alternative investments such as real estate or private placements may not be easily liquidated when needed.
- Regulatory risk: Self-Directed IRAs are subject to IRS rules, and non-compliance can result in penalties, fines, or full account disqualification.
- Fraud risk: Self-Directed IRAs can be vulnerable to fraudulent schemes. Working with a reputable custodian and conducting thorough due diligence on every investment is essential.
Book a free call with a self-directed retirement specialist
- Review your self-directed retirement options
- Learn about investing in alternative assets
- Get all of your questions answered
Choosing the Best Self-Directed IRA Custodian
Choosing a custodian involves several important factors. Here is what to look for.
RITA membership: The first question to ask any custodian is whether they are a member of the Retirement Industry Trust Association (RITA). RITA is responsible for the continuing education of regulated Self-Directed IRA custodians. The best custodians in the industry are members.
Expertise: The custodian you choose should have deep experience in self-directed plans, including checkbook control. Checkbook control gives you the freedom to make any IRS-approved investment at any time without waiting for custodian approval. Custodian control is an alternative that still allows alternative investments, but requires custodian sign-off before each transaction, which can cause delays.
Fee structure: Look for flat, transparent fees. Avoid custodians that charge based on account value or layer in hidden fees for common services.
Experience with alternative assets: If you plan to invest in real estate, private equity, or other non-traditional assets, confirm that the custodian has specific experience handling those asset types.
Responsive customer service and efficient transaction processing: The right custodian should make administration smooth without interfering with your investment strategy.
Putting it All Together
Choosing a Self-Directed IRA custodian should not be taken lightly. Cost alone does not tell you anything about service, expertise, or experience. Do your homework before signing up, work with a qualified financial planner, and educate yourself on the rules before committing to a structure.
The custodian you choose can either limit your investment universe or open the door to much broader opportunities. Make sure you choose one that aligns with your long-term strategy and gives you the flexibility to invest the way you want.
If you have any questions, IRA Financial's team is available to help at 800.472.1043.
Frequently Asked Questions
Why do you need a specialized custodian?
Banks and large financial firms limit investments to stocks and mutual funds. Specialized custodians allow real estate, private equity, and other alternative assets. They charge fees for account setup and maintenance rather than selling financial products.
What custodian fees should I watch for?
Setup fees are charged when opening the account. Annual fees cover ongoing account maintenance. Transaction fees apply to buying and selling investments. Some custodians also charge based on account value, flat fees are generally the better option as your balance grows.
What are the risks and challenges of Self-Directed IRAs?
Investment risk means some alternative assets can be volatile. Liquidity issues can arise with real estate and private placements that are harder to sell quickly. Regulatory compliance is the account holder's responsibility, and breaking IRS rules can result in penalties. Investors must also vet investment opportunities carefully to avoid fraud.
What is the difference between a custodian and a trustee?
Both terms refer to a fiduciary who holds assets for the benefit of another party. In practice, for most retirement accounts, the difference is minimal from the investor's perspective. What matters most is whether the institution supports self-direction and alternative investments.
What does a custodian not do?
A custodian does not perform due diligence on investments, guarantee returns, or evaluate whether a deal is worth pursuing. That responsibility rests entirely with the account holder, which is why working with experienced advisors alongside your custodian is important.
How to Minimize the Cost of Your Self-Directed Roth IRA Investment
When most people think about building wealth inside a Self-Directed Roth IRA, they focus on what to invest in. Real estate. Private equity. Startups. Crypto. That part of the conversation gets a lot of attention.
What gets far less attention is something I think matters just as much: what you pay to get in.
In a Self-Directed Roth IRA, all future growth on your investments can be completely tax free, provided the account has been open at least five years and you are age 59 and a half or older when you take distributions. That means the lower the value at which an asset enters your Roth IRA, the greater the amount of future appreciation that escapes taxation entirely. Getting assets in at the lowest defensible valuation is not a loophole. It is a legitimate and powerful strategy that sophisticated investors use, and one that I think far too few people understand.
What is a Self-Directed Roth IRA?
A Self-Directed Roth IRA works exactly like a standard Roth IRA from a tax perspective. Contributions are made with after-tax dollars, the account grows tax deferred, and qualified distributions in retirement are completely tax free.
The difference is in what you can invest in. A standard Roth IRA at a brokerage limits you to whatever is on their platform, typically stocks, bonds, and mutual funds. A Self-Directed Roth IRA allows you to invest across a much broader universe of assets, including private companies, real estate, private funds, cryptocurrency, promissory notes and private lending, and LLC or partnership interests.
This is where the real opportunity lies. The ability to invest in high-growth assets before they are widely known or fully valued, and to do it inside a tax-free structure, is one of the most powerful wealth-building combinations available under the tax code.
Prohibited Investments
The IRS does not provide a list of approved IRA investments. Instead it defines what is not allowed. Under the Internal Revenue Code, prohibited investments include life insurance, certain collectibles under IRC Section 408(m), and any transaction that falls under the prohibited transaction rules of IRC Section 4975.
The prohibited transaction rules are the most important compliance consideration. They generally cover self-dealing, personal use of IRA assets, and transactions with disqualified persons. Disqualified persons include you, your spouse, your parents and children, and entities you control.
The core principle is straightforward: your IRA must operate independently from you. As long as you are investing at arm's length and not personally benefiting from the asset while it sits inside the account, you are operating within the rules.
Book a free call with a self-directed retirement specialist
- Review your self-directed retirement options
- Learn about investing in alternative assets
- Get all of your questions answered
How Valuation Works for Private Assets
For publicly traded assets, valuation is simple. The market price is the market price.
For private assets, it is more nuanced, and this is where real planning opportunities exist.
Fair market value is defined as what a willing buyer would pay a willing seller, both having reasonable knowledge of the relevant facts. When you purchase a private asset, the price you pay is generally the starting point for establishing fair market value. But that is only the beginning of the analysis, and understanding what can legitimately reduce that value is where the strategy becomes meaningful.
The Case for Discounted Valuations
Private investments often justify valuation discounts because of real economic limitations that affect what a rational buyer would actually pay. These are not tax tricks. They are recognized valuation principles grounded in decades of tax law, primarily developed in the context of estate and gift tax planning.
The two most common discounts are the lack of marketability discount and the minority interest discount.
A lack of marketability discount applies when a private asset cannot be easily sold. There is no active market, no ready buyer, and transferring the interest may be subject to restrictions. That illiquidity has real economic value, and it reduces what a willing buyer would pay.
A minority interest discount applies when your IRA owns a small stake in a private company or partnership without any meaningful control over decisions, distributions, or the timing of a sale. Owning 10 percent of a business is fundamentally different from owning 100 percent, and the value of that minority interest should reflect that reality.
In the right context, and when supported by a qualified appraisal and real economic conditions, valuation discounts for private investments can reasonably range between 10 and 40 percent. A minority interest in a private company with transfer restrictions might justify a combined discount of 20 to 35 percent. A highly illiquid private fund interest could fall toward the higher end of that range. A more structured investment with some liquidity provisions might fall closer to 10 to 20 percent.
These are not automatic. They must reflect real conditions, be supported by data, and be defended through independent valuation. But when those conditions are met, they are entirely legitimate.
Where These Discounts Come From
I want to spend a moment on the history here because I think it helps investors understand why these discounts are valid rather than aggressive.
Valuation discounts have been used in estate and gift tax planning for decades. When families transfer interests in closely held businesses or real estate partnerships, the IRS requires those interests to be valued at fair market value. And courts have consistently recognized that a minority interest in a private entity, one where the holder cannot control decisions, force a sale, or easily transfer their stake, is worth less than its proportional share of the whole.
Family Limited Partnerships became one of the most common vehicles for applying these principles. A family would place assets into a partnership structure, with senior members retaining control and transferring minority interests to children or other family members. Because those minority interests lacked control and marketability, they could be valued at a discount, allowing families to transfer wealth more efficiently while reflecting the true economic value of what was being transferred.
Over time the IRS challenged structures that appeared to exist solely for tax reduction without any real business purpose. Courts responded by establishing a consistent framework: discounts are allowed when they reflect real economic conditions, but they will be challenged when they are artificial or exaggerated.
That same framework now applies to Self-Directed Roth IRA investments. When your IRA invests in a private company, a real estate deal, or a partnership interest, the value of that interest must reflect control, liquidity, transfer restrictions, and market realities. When it does, discounts in the 10 to 40 percent range are well-supported by law and consistent with what courts have historically accepted.
What the IRS Looks For
The IRS does not oppose valuation discounts in principle. Courts have consistently recognized them as valid when they reflect real economic conditions. What the IRS scrutinizes is whether a discount is being applied in a way that is genuine and justified, or simply used to artificially manufacture a lower number.
In practice the IRS focuses on three things:
- Whether the structure has a real business purpose beyond tax reduction.
- Whether the discount is supported by market data and comparable transactions rather than the taxpayer's own judgment.
- Whether the valuation was conducted by an independent qualified appraiser.
The question the IRS will always ask is simple: does this valuation reflect what a real buyer would actually pay? If the answer is yes, and the position is supported by data and independent analysis, it is on solid ground. If the structure appears designed only to create a lower number without real economic substance, that is when problems arise.
The Tax Court has consistently upheld properly supported discounts. In Holman v. Commissioner, the court allowed meaningful discounts when properly supported. Estate of Warne v. Commissioner confirmed that discounts can apply even to majority interests under the right conditions. Lappo v. Commissioner accepted significant discounts based on expert analysis. And Giustina v. Commissioner supported valuation reductions tied to liquidity and control limitations.
The pattern across all of these cases is consistent: substance over form. Real limitations on control and liquidity justify real discounts. The position just has to be defensible.
Why the Appraisal Matters More Than the Price
This is one of the most important practical points I can make on this topic.
The price you pay for an asset establishes the starting point. The appraisal is what protects you.
If the IRS ever challenges your valuation, they will not simply look at what you paid. They will rely heavily on expert analysis. A well-supported independent appraisal, one that documents the economic conditions, the discount methodology, and the comparable transactions, often carries more weight than the transaction price itself.
For a Self-Directed Roth IRA investment, this matters enormously. A qualified appraisal is not just a formality. It is the foundation of a defensible position. Skipping it to save money on the front end is a false economy.
Why Entry Value Is Everything
Here is the simplest way I know to explain why this strategy is so powerful.
Two investors end up with the same private company investment worth $1 million at exit.
The first investor got in at $300,000.
The second investor, using properly supported valuation discounts, got in at $100,000.
Both made money. But the second investor was able to shelter significantly more of that gain inside a tax-free Roth IRA.
On the first investor's position, $700,000 of growth escapes taxation.
On the second investor's position, $900,000 escapes taxation.
Same investment, same outcome, very different tax result.
Over a career of investing, that difference compounds in a way that is genuinely extraordinary. And it is entirely legal when done correctly.
Final Thoughts
A Self-Directed Roth IRA is already one of the most powerful wealth-building tools available under the tax code. But its real advantage is not just tax-free growth. It is the combination of tax-free growth and the ability to invest in high-growth private assets at defensible valuations before the market fully recognizes their potential.
Getting the valuation right matters. It requires a real investment with genuine economic limitations, a properly documented analysis, and a qualified independent appraisal. When those pieces are in place, the strategy is well-supported by decades of tax law and consistent with what courts have repeatedly upheld.
In my experience, this is one of the areas where working with the right team makes the biggest difference. The strategy is not complicated in concept, but the execution has to be done correctly. IRA Financial works with clients on every aspect of this process, from structuring the investment to ensuring the valuation is properly documented and defensible.
If you want to understand how this approach might apply to your specific situation, we are happy to walk you through it.
The New Era of 401(k) Investing: What the DOL's Alternative Asset Safe Harbor Really Means
For decades, there has been a structural imbalance in how Americans invest for retirement.
Large institutional investors, pension funds, endowments, and sovereign wealth funds, have long relied on private equity, real estate, infrastructure, and other alternative assets to drive returns and manage risk. Meanwhile, the average American saving through a 401(k) plan has been largely confined to a menu of mutual funds built around public stocks and bonds.
That divide has not existed because alternative investments lack merit. It has existed because of regulation, operational complexity, and fiduciary risk.
In March 2026, the Department of Labor took a meaningful step toward closing that gap by issuing a proposed rule designed to expand access to alternative assets within 401(k) plans. The proposal, driven by Executive Order 14330, acknowledges something that many in the industry have long understood: alternative assets can improve diversification and potentially enhance long-term, risk-adjusted returns for retirement savers.
But the real significance of the rule is not simply that it allows alternatives. It is that it attempts to answer the question that has held the market back for years: how can a fiduciary include alternative investments in a 401(k) plan without taking on unacceptable legal risk?
This is a question I have been asked by plan sponsors, advisors, and individual investors for years. The fact that the Department of Labor is finally addressing it directly is worth paying attention to.
From Fear to Framework
Historically, fiduciaries have operated in an environment where the rules around alternative assets were not entirely clear. ERISA requires that fiduciaries act with care, skill, prudence, and diligence, but applying that standard to illiquid or complex investments has always been challenging. The result has been predictable: when in doubt, avoid anything that could invite scrutiny.
The Department of Labor's proposal attempts to change that dynamic by shifting the focus away from outcomes and toward process.
In plain terms, the rule says that if you follow a thoughtful, well-documented process, your decision should be considered prudent, even if the investment itself is complex or does not ultimately outperform. That is a meaningful shift in how fiduciary responsibility is evaluated, and it opens the door to a much broader conversation about what belongs in a retirement plan.
https://youtu.be/FEDG_mk2-ak?si=Pd0FYdR9L8ZO1EC6
What the Safe Harbor Actually Requires
Rather than prescribing specific investments, the safe harbor outlines how fiduciaries should evaluate any investment they consider including in a 401(k) plan.
The framework requires fiduciaries to evaluate expected performance on a risk-adjusted basis rather than simply chasing returns. They must analyze fees in the context of value, recognizing that higher-cost investments can be justified if they deliver meaningful diversification or downside protection. They must ensure sufficient liquidity for participant needs, adopt reliable valuation processes even for private assets, identify meaningful benchmarks for comparison, and fully understand the complexity of the investment or engage qualified experts who do.
When this type of disciplined, well-documented process is followed, the safe harbor provides a presumption that the fiduciary has satisfied ERISA's duty of prudence.
The key insight here is that it is not about what you pick. It is about how you pick it. For anyone who has spent time working within ERISA, that is a genuinely significant change in emphasis.
Why This Matters for Alternative Assets
This framework directly addresses the reasons alternative investments have historically been excluded from 401(k) plans.
Private equity may involve higher fees and longer investment horizons, but it also offers the potential for enhanced long-term returns. Real estate may be less liquid, but it can provide income stability and inflation protection. Under the new framework, fiduciaries are empowered to weigh these trade-offs in a structured, defensible way rather than defaulting to exclusion out of caution.
That represents a real philosophical shift, and one that is long overdue.
What Will Actually Happen in the Short Term
Despite the flexibility the safe harbor provides, adoption will be gradual. Large employers will remain cautious, primarily due to litigation concerns. Rather than offering participants direct access to private investments, most plans will introduce alternatives through diversified vehicles such as target date funds or multi-asset funds.
A target date fund, for example, might allocate 10 to 15 percent of its portfolio to private equity or real estate. Participants gain exposure to alternative assets without needing to select or manage those investments directly, and fiduciaries can satisfy safe harbor requirements while maintaining operational simplicity.
This is the realistic near-term outcome. Meaningful progress, but measured and institutional in nature.
Why Smaller or Direct Deals Won't Make It into Most 401(k) Plans
While the rule expands flexibility, it does not eliminate practical constraints. Smaller or localized investments, such as a single real estate deal or a fundless sponsor transaction, are unlikely to appear in most 401(k) plans. These investments often lack clear benchmarks, present liquidity challenges, and require complex valuation processes. Even if the investment itself is compelling, the fiduciary burden of analyzing and defending it under ERISA is simply too high for most plan sponsors.
There may be an emerging opportunity at the smaller plan level. Closely held businesses or community-based companies may be more willing to explore curated, local investment opportunities where the employer has deep familiarity with the asset or sponsor. A regional real estate project or a local private business investment that the employer understands well could, in certain cases, be thoughtfully incorporated into a plan.
But even for smaller plans, the same core fiduciary principles apply. The investment would still need to satisfy the safe harbor framework, meaning reasonable benchmarking, defensible valuation, appropriate liquidity considerations, and a well-documented process. Smaller plans may have more flexibility and a higher tolerance for complexity than large institutional employers, but this is not a free pass. It is an opportunity that still requires discipline.
The Reality of Litigation Risk
The safe harbor provides guidance, but it does not eliminate litigation risk. Large 401(k) plans remain prime targets for lawsuits, and even weak claims can be expensive to defend. Courts have historically allowed these cases to proceed beyond early dismissal, which creates significant pressure on employers regardless of the merits.
As a result, large companies will continue to move cautiously. Smaller companies, facing less litigation exposure, may be more willing to move forward and will likely lead the way in early adoption.
Where Self-Directed IRAs Still Stand Apart
While this rule expands access to alternatives within 401(k) plans, it does not eliminate the advantages of a Self-Directed IRA. And I want to be direct about this, because I think it is an important distinction that often gets lost in the excitement around regulatory changes like this one.
A Self-Directed IRA allows investors to directly select and control their investments, including private equity, real estate, and other non-public opportunities. It operates entirely outside the employer-driven fiduciary framework that governs 401(k) plans.
In a 401(k), the investment menu is ultimately controlled by the plan sponsor and its fiduciaries. Even with the new safe harbor, every investment must be vetted, documented, benchmarked, and defensible under ERISA. That naturally limits what can be offered and tends to favor broadly diversified, institutional-style products over specific or niche opportunities.
A Self-Directed IRA works differently. You, not your employer, are making the investment decisions. There is no plan committee deciding what is appropriate for a broad group of employees. There is no requirement to fit an investment into a standardized menu or ensure it works for thousands of participants with different needs. The IRS rules focus primarily on what is not permitted, such as prohibited transactions and certain collectibles, rather than prescribing what must be offered.
This creates a fundamentally different investment experience. If you identify a compelling private equity opportunity, a local real estate deal, or a startup investment, a Self-Directed IRA allows you to act on it directly. You are not constrained by liquidity requirements designed for daily trading, nor are you limited to investments that can be easily benchmarked against public indices.
The difference in precision matters too. In a 401(k), you may gain indirect exposure to private markets through a fund that allocates 10 to 15 percent to alternatives. In a Self-Directed IRA, you can choose to allocate a much larger portion of your retirement capital to a specific strategy or deal that you understand and believe in.
For investors who are already evaluating alternatives outside of their retirement accounts, the Self-Directed IRA is the most direct way to bring that same discipline and conviction into a tax-advantaged structure.
An Important Reminder: This Is Still a Proposal
It is worth being clear that this framework is not yet final. The Department of Labor has issued this as a proposed rule and is actively seeking input from the public, industry participants, fiduciaries, and other stakeholders. There is a 60-day comment period from the date the proposal is published in the Federal Register, and the framework we see today could evolve meaningfully before it is finalized.
Industry feedback will likely focus on how to practically implement liquidity requirements, how to define meaningful benchmarks for private assets, the extent to which the safe harbor truly mitigates litigation risk, and the operational challenges facing plan sponsors and recordkeepers. This is a collaborative process, and the final rule may look different from what has been proposed.
Progress, Not Perfection
The Department of Labor's proposal represents a meaningful evolution in retirement policy. It reflects a growing recognition that limiting retirement investors to public markets may no longer be sufficient, and it creates a framework that allows fiduciaries to thoughtfully incorporate alternative assets into 401(k) plans.
At the same time, it does not eliminate the structural realities of plan administration. Liquidity, valuation, complexity, and litigation risk will continue to shape how alternative assets are offered. In the short term, change will be measured. In the long term, the impact could be significant.
But the most important shift may be the simplest one. The conversation has changed. The question is no longer whether alternative assets belong in retirement plans. The question is how to include them responsibly. And that is exactly what this proposal begins to answer.
For investors who do not want to wait for the 401(k) world to catch up, the Self-Directed IRA remains the most direct and flexible path available today.
How a Self-Directed HSA Can Double as a Stealth Retirement Account
A Health Savings Account (HSA) is widely known for its role in helping people cover medical expenses. But for high earners who are already maxing out traditional retirement accounts, it can be something more: one of the most tax-efficient long-term investment vehicles in the entire tax code.
Thanks to its triple tax advantage, no required minimum distributions, and post-65 withdrawal flexibility, an HSA can quietly function as a stealth retirement account. And when paired with a self-directed structure, investors can move beyond basic index funds and allocate into stocks, real estate, private funds, and other alternative assets, extending the account's long-term wealth-building potential significantly.
Why HSAs Act Like "Super IRAs" for High Earners
HSAs offer a combination of tax features that no other account matches. Here is what makes them so powerful:
- Tax-free contributions: Contributions reduce taxable income. Salary-reduction contributions can also avoid payroll taxes.
- Tax-free growth: Invested balances compound without capital gains or dividend tax drag.
- Tax-free withdrawals for qualified medical expenses: Money used for qualified medical costs comes out completely tax-free.
- No required minimum distributions (RMDs): Unlike Traditional IRAs, HSA balances can remain invested indefinitely. There is no age at which the IRS forces you to start drawing down the account.
- Post-65 flexibility: After age 65, withdrawals for non-medical purposes are penalty-free and taxed as ordinary income, while medical withdrawals remain tax-free entirely.
For high earners who have already maxed out their 401(k) and IRA options, the HSA becomes an additional long-horizon compounding engine with some of the most favorable tax treatment available anywhere in the code.
The Stealth IRA Strategy: How Delayed Reimbursement Multiplies Wealth
The most efficient way to use an HSA as a retirement vehicle is straightforward, but most people never do it.
- Contribute the maximum each year
- Invest contributions for long-term growth
- Pay medical expenses out of pocket instead of using HSA funds
- Save all receipts
- Reimburse yourself tax-free later, even decades later
There is no IRS-imposed deadline for reimbursement as long as the expenses occurred after the HSA was opened and your documentation is maintained. That means your HSA can function as a tax-free compounding reservoir for years, with future reimbursements serving as flexible, tax-free withdrawals whenever you need them.
The longer you let the account grow untouched, the more powerful this strategy becomes.
What a Self-Directed HSA Adds to the Equation
A traditional HSA typically offers only cash or a limited menu of mutual funds. A Self-Directed HSA expands your investment choices significantly.
Investable asset classes may include:
- Real estate (direct ownership or syndications)
- Private equity and private credit
- Venture capital funds
- Precious metals
- Cryptocurrency
- Stocks, ETFs, and bonds
Custodians such as IRA Financial support these structures and maintain compliance frameworks that allow HSAs to hold alternative investments alongside publicly traded securities.
Book a free call with a self-directed retirement specialist
- Review your self-directed retirement options
- Learn about investing in alternative assets
- Get all of your questions answered
Investing in Stocks and Alternative Assets Through a Self-Directed HSA
One of the most underappreciated aspects of a Self-Directed HSA is the ability to hold both traditional securities and alternative assets within the same account. Most investors think of these two worlds as separate, stocks and ETFs in one place, alternatives like real estate and private equity in another. A Self-Directed HSA removes that boundary.
Through IRA Financial's platform, HSA holders can invest in publicly traded stocks, ETFs, and bonds alongside alternative assets like real estate, private equity, and cryptocurrency, all within a single tax-advantaged account. That means every trade, whether a stock rebalance or a private fund investment, happens inside the HSA's tax-free wrapper.
For high earners, the practical benefits are meaningful:
- Consolidated portfolio management: Your entire HSA allocation, across both public and private markets, is visible and manageable in one place rather than spread across multiple platforms
- Tax-free compounding across asset classes: Stock trades, dividends, and alternative asset gains all compound without annual tax drag
- Flexible rebalancing: You can shift between stocks, ETFs, and alternatives as your investment thesis evolves without triggering taxable events
- Alignment with broader strategy: Investors who already hold alternatives in their IRA or Solo 401(k) can extend that same strategy into their HSA rather than keeping it siloed in index funds
This capability matters most for investors who are actively managing a diversified portfolio and want every tax-advantaged account working as hard as possible. An HSA that holds only a target-date fund is leaving significant long-term value on the table.
One capability that sets IRA Financial's platform apart is the ability to use a dedicated HSA debit card to pay medical expenses directly from the same account where your investments live. Most HSA providers force a choice: keep cash available for medical expenses in one place and invest separately elsewhere. With IRA Financial, stocks, alternative assets, and day-to-day medical spending all exist within a single account under one low flat annual fee. That combination does not exist anywhere else in the marketplace.
Critical Compliance Considerations: UBIT, UDFI, and Prohibited Transactions
A Self-Directed HSA offers more flexibility, but also more responsibility. There are a few compliance areas every investor needs to understand before moving forward.
Unrelated Business Income Tax (UBIT)
HSAs may owe UBIT when investing in operating businesses via partnerships or LLCs, or in leveraged real estate, which can trigger a related charge called UDFI. Because UBIT is taxed at steep trust tax rates, failing to anticipate it can materially reduce your returns on otherwise attractive investments.
Prohibited Transactions
HSAs are subject to the same self-directed account rules as IRAs. Prohibited transactions include self-dealing, personal use of HSA assets, and transactions with disqualified persons such as a spouse, children, parents, or controlled entities. A single violation can disqualify the entire account, so getting this right matters.
The bottom line: self-directed investing inside an HSA is extremely powerful, but it must be executed carefully and with professional guidance.
Where the HSA Fits in a High-Earner Tax Strategy
A commonly used priority order for maximizing tax-advantaged savings looks like this:
- 401(k) employer match
- HSA contributions (self-directed optional)
- Backdoor Roth IRA
- Mega Backdoor Roth (if available)
- Additional 401(k) contributions
- Taxable brokerage investing
HSAs rank near the top because they combine triple tax advantages, Roth-like tax-free withdrawals for medical expenses, IRA-like flexibility after age 65, and no RMDs. For high earners with strong cash flow, that combination makes the HSA one of the most efficient savings vehicles available anywhere in the tax code.
When a Self-Directed HSA Is Not the Right Fit
A Self-Directed HSA is not the right tool for everyone. It may not be appropriate if:
- You have high or unpredictable annual medical expenses
- You cannot comfortably pay medical costs out of pocket
- You are unfamiliar with UBIT or prohibited transaction rules
- Your investing activity frequently involves related parties or controlled entities
- You prefer simpler, set-and-forget investment management
In these cases, a traditional HSA invested in low-cost index funds may be the better fit. The self-directed structure rewards investors who are already comfortable managing alternative assets and staying on top of compliance requirements.
A Practical Annual Workflow for HSA Optimization
Beginning of the year
- Confirm HDHP eligibility
- Max out your HSA contributions
Quarterly
- Invest new contributions
- Archive receipts for potential future reimbursement
Annually
- Review investment allocation
- Assess UBIT exposure and compliance
- Evaluate new alternative asset opportunities if self-directed
Long-term
- Maintain digital receipt records
- Reimburse only when strategically advantageous
- Integrate the HSA into retirement income modeling
Final Thoughts
A Self-Directed HSA is one of the most underutilized wealth-building tools available, especially for high earners. When paired with long-term investing and the delayed reimbursement strategy, it functions not just as a healthcare reserve but as a stealth retirement account with unmatched tax efficiency.
For investors comfortable navigating alternative assets and compliance rules, the Self-Directed HSA unlocks a uniquely flexible, tax-advantaged growth engine within a part of the tax code originally designed for healthcare spending. And with the ability to hold both stocks and alternatives inside the same account, every dollar in the HSA can be put to work in a way that aligns with your broader investment strategy.
Top Retirement Accounts for High-Net-Worth Individuals
Choosing the right retirement account isn't just a box to check. For high-net-worth individuals, typically those with $1 million or more in investable assets outside of a primary residence, it's one of the most important structural decisions you can make. Because at that level of wealth, how your account is set up matters just as much as what you invest in.
If you've spent years building significant assets, you already know that tax efficiency, flexibility, and control aren't nice-to-haves. They're the difference between a retirement strategy that works hard for you and one that quietly holds you back.
Key Takeaway
- Top retirement account providers and custodians worth considering for affluent investors
- A close look at fees and offerings
- Reputation breakdown for each provider
- What makes each one a fit depending on your goals
What This Is and Who Is It For?
A retirement account is a tax-advantaged account designed to help you save for retirement. But not all retirement accounts are built the same, and for high-net-worth investors (HNWIs) the standard options often fall short.
Here's why HNWIs have different needs:
- Tax efficiency. When you're managing a large portfolio, reducing lifetime tax drag isn't a minor optimization. It's a major strategic priority.
- Access to alternative investments. Real estate, private equity, crypto, precious metals; these are the asset classes that sophisticated investors want in their corner, and most traditional IRAs don't allow them.
- Customization. Advanced estate planning, strategic asset allocation, and account structures that align with a broader wealth strategy aren't features most off-the-shelf retirement accounts offer.
The good news is that the right custodian can change all of this. Small structural advantages compound meaningfully over time when you're dealing with larger balances.
What to Look for Before You Choose
Before committing to any provider, it's worth slowing down and evaluating a few key factors.
- Fees and transparency. Some custodians charge asset-based fees that scale with your balance, which can get expensive fast. Flat-fee models tend to be more cost-efficient for larger portfolios, and they're easier to plan around.
- Investment scope. Traditional brokerage IRAs cover stocks, bonds, and ETFs. Self-Directed IRAs open the door to alternative assets, but they come with more responsibility. You need to understand IRS rules, prohibited transactions, and how to keep your account structured properly.
- Support and advisory services. High-net-worth clients benefit from custodians who actually know their situation. Dedicated support, compliance guidance, and access to planning resources aren't luxuries at this level, they're part of what you're paying for.
- Regulatory risk. Not all alternative investments are SEC-regulated. Illiquidity, valuation complexity, and fraud exposure are real considerations. Working with a custodian that has strong in-house compliance makes a meaningful difference here.
Top Retirement Accounts for High-Net-Worth Investors
Listed in no particular order.
1. IRA Financial
If you want control, flexibility, and a fee structure that doesn't penalize you for being successful, IRA Financial is worth serious consideration.
IRA Financial operates on a flat, transparent fee model; no asset-based fees that grow as your account does. That alone sets it apart from most custodians when you're managing a large balance.
Beyond fees, IRA Financial supports one of the broadest investment menus available: real estate, private equity, cryptocurrency, precious metals, private credit, and more, all within a tax-advantaged account.
And now, with the IRA Financial Unified Platform powered by Interactive Brokers (IBKR), clients can do something no other Self-Directed IRA custodian currently offers the ability to hold traditional investments such as stocks, ETFs, bonds, mutual funds, alongside their alternative assets, for one flat fee. Real-time trading, an add-on of $100 annually, and a unified view of your entire retirement portfolio. For high-net-worth investors who want both worlds without the complexity of managing separate accounts, this is a significant development.
Account options include Traditional IRA, Roth IRA, Self-Directed IRA, Checkbook IRA, IRA Financial's Crypto IRA, and Solo 401(k).
Best for: High-net-worth investors who want total control, alternative asset access, real-time trading, and predictable costs, all in one place.
2. Fidelity
Fidelity is one of the most established names in retirement investing, and for good reason. $0 IRA maintenance fees, commission-free trading on a wide range of investments, and an extensive product line make it a strong choice for investors who are primarily focused on traditional assets.
For high-net-worth clients, Fidelity's private wealth management services offer personalized planning support, though some tiers require minimum asset levels to access. Research tools, estate planning resources, and a well-built digital platform round out a solid offering.
Best for: Investors focused on traditional markets who want institutional-grade wealth management support.
3. Vanguard
Vanguard built its reputation on one thing: keeping costs low. Industry-low expense ratios and a long track record of long-term performance have made it a go-to for buy-and-hold investors who want to maximize returns by minimizing fees.
IRA options include Traditional, Roth, SEP, and SIMPLE accounts. Vanguard's investor-owned structure, meaning the funds own the company, not outside shareholders, is a genuinely unusual feature that aligns incentives well for long-term clients.
Best for: Long-term, buy-and-hold investors who prioritize low costs and simplicity over flexibility.
4. Charles Schwab
Charles Schwab offers a well-rounded platform with no minimum IRA balance and no maintenance fees. The combination of a strong brokerage offering, Schwab Intelligent Portfolios for automated investing, and access to managed accounts and full-service financial planning makes it a versatile choice.
Customer service is consistently well-regarded, and Schwab's digital tools are among the better ones available from a traditional custodian.
Best for: Investors who want a dependable, full-service traditional IRA platform with strong advisory options.
5. Rocket Dollar
Rocket Dollar is a newer player in the self-directed space, built for investors who want to move beyond traditional markets without a complicated setup. The platform supports real estate, startups, private placements, crypto, and more, with optional checkbook control for faster investment execution.
Pricing is straightforward and accessible, which makes it a reasonable entry point for investors newer to self-direction.
Best for: Investors exploring self-directed options for the first time, or those who want checkbook control with a simpler setup.
Book a free call with a self-directed retirement specialist
- Review your self-directed retirement options
- Learn about investing in alternative assets
- Get all of your questions answered
Final Thoughts
The right retirement account structure can shape your financial future for decades. It's not just about the investments you hold; it's about how they're taxed, how they're protected, and how much flexibility you have to respond to changing markets and life circumstances.
For most high-net-worth investors, the question isn't whether to optimize your retirement structure. It's whether you're already doing it.
If you're drawn to traditional brokerage IRAs through firms like Fidelity, Vanguard, or Schwab, the options are strong. If you want the flexibility, control, and investment breadth that self-direction offers, IRA Financial, and particularly the new Unified Platform, represents one of the most complete options available today.
Either way, take the time to align your account structure with your actual goals. At this level, the details compound.
Ready to take the next step? Schedule a free consultation to explore how IRA Financial can help you take control of your retirement strategy.
Frequently Asked Questions
What is the difference between a traditional IRA and a Self-Directed IRA?
Traditional IRAs, offered by custodians like Fidelity or Vanguard, limit you to stocks, bonds, ETFs, and mutual funds. Self-Directed IRAs expand that universe to include real estate, cryptocurrency, private equity, and more, but they require a solid understanding of IRS rules and careful compliance management.
Are retirement accounts safe for alternative investments?
They can be. But alternative assets are generally less regulated and more complex than traditional investments. Working with a custodian that provides in-house compliance guidance makes a real difference in managing that complexity.
Do high-net-worth investors need a financial advisor?
Not necessarily, but many benefit from professional planning support; particularly around tax strategy, required minimum distributions, estate planning, and managing portfolios that span multiple asset classes. The right custodian can also fill some of that role.
Can I roll over an existing retirement account?
Yes. Most 401(k) plans and IRAs can be rolled over into a new account. Before initiating a rollover, understand any fees involved, the timing requirements, and any potential tax implications. A qualified advisor or your new custodian can walk you through the process.
This article is provided for informational purposes only and does not constitute investment, tax, or legal advice. Rankings and opinions reflect the views of IRA Financial based on internal research and publicly available information at the time of publication. Readers should independently evaluate all options and consult with qualified advisors prior to making financial decisions.
Can You Trade Stocks Inside a Self-Directed IRA?
If you invest in alternative assets through a Self-Directed IRA, real estate, cryptocurrency, private equity, you've probably had to maintain a separate brokerage account for stocks and ETFs. The two worlds haven't traditionally intersected.
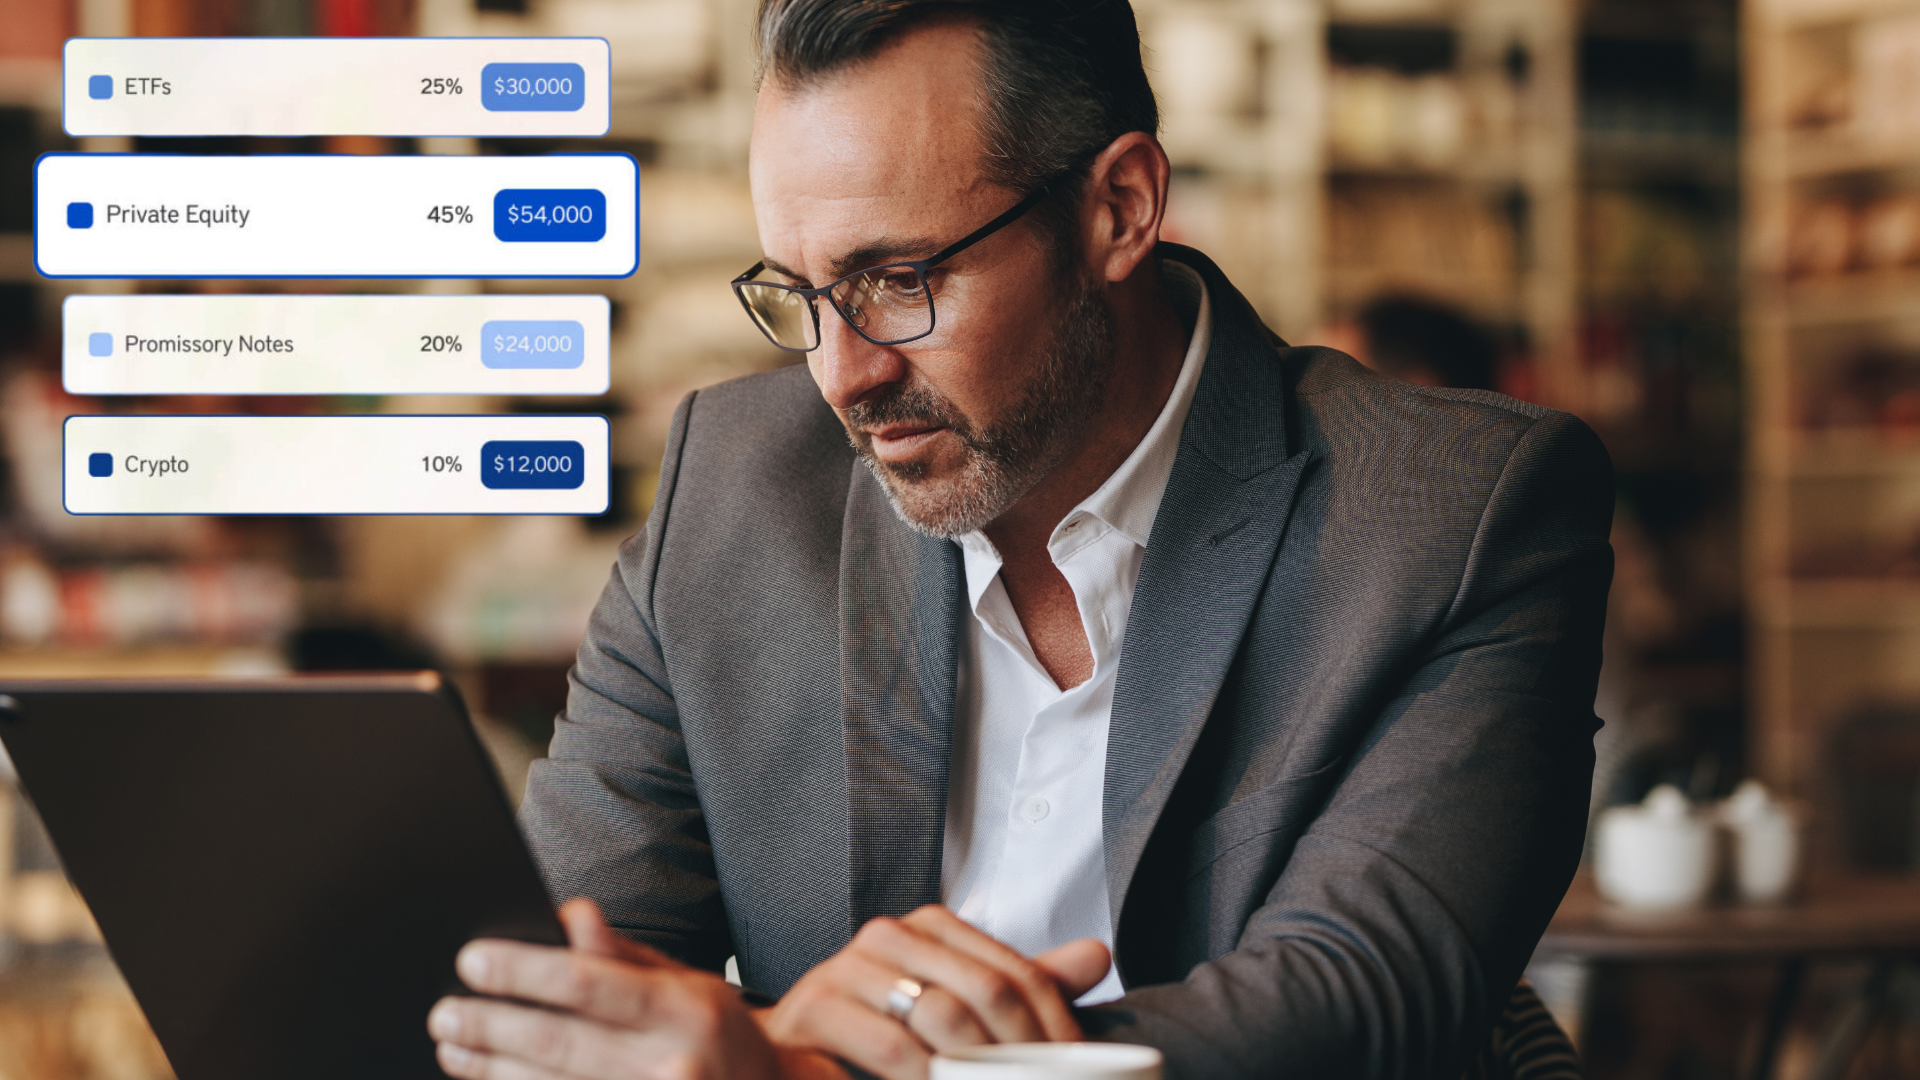
That's changed. IRA Financial has integrated real-time stock trading directly into its self-directed retirement platform, powered by Interactive Brokers (IBKR). Self-Directed IRA, Checkbook IRA, and Solo 401(k) holders can now trade stocks, ETFs, mutual funds, bonds, options, and currencies in real time, inside the same account they use for alternative investments.
Key Takeaways
-
- What assets you can trade in real time
- Which account types are eligible
- How tax treatment works inside an IRA
- Pricing
- How to get started
What Assets Can You Trade in Real Time?
Through IRA Financial's new unified platform powered by Interactive Brokers, account holders can trade the following asset classes in real time:
- Stocks: Buy and sell U.S.-listed and international equities at market prices during trading hours.
- ETFs (Exchange-Traded Funds): Access thousands of exchange-traded funds, including index funds, sector ETFs, and thematic funds. U.S.-listed ETFs trade with $0 commissions.
- Mutual Funds: Invest in a wide range of mutual funds for long-term, professionally managed exposure.
- Bonds: Add U.S. Treasuries, corporate bonds, and municipal bonds for fixed-income exposure within your retirement account.
- Options: Trade options contracts for hedging strategies or more targeted market positioning.
- Currency / Forex: Access global foreign exchange markets, including major and minor currency pairs.
All trading is executed through Interactive Brokers under IBKR Lite pricing: $0 commissions on U.S.-listed stocks and ETFs, with competitive rates on all other asset classes.
These can be held alongside alternative investments, real estate, cryptocurrency, private equity, precious metals, and private loans, within the same retirement account.
Which Account Types Are Eligible?
Real-time stock trading is available across IRA Financial's main account structures. Here's how each one works and who it's designed for.
Self-Directed IRA (Traditional or Roth)
A Self-Directed IRA works like a standard IRA in terms of contribution limits and tax treatment, but it allows a much broader range of investments than a typical brokerage IRA. With the IBKR integration, that now includes real-time stock and ETF trading alongside any alternative assets you hold. Both Traditional (pre-tax) and Roth (after-tax) structures are eligible.
Checkbook IRA (IRA LLC)
A Checkbook IRA involves your IRA owning a specially formed LLC, which gives you direct investment authority, sometimes called checkbook control. You can direct that LLC to invest in publicly traded securities through Interactive Brokers without requiring custodian approval for each transaction. This structure is popular among investors who want maximum speed and flexibility.
Solo 401(k)
The Solo 401(k) is designed for self-employed individuals and small business owners with no full-time W-2 employees other than a spouse. It carries significantly higher annual contribution limits than an IRA, up to $70,000 in 2025 depending on your income and structure and now supports real-time trading through Interactive Brokers alongside alternative asset investments.
Benefits of a Unified Platform
For most investors, alternative assets and publicly traded securities have lived in separate accounts, often at separate institutions. That separation has real consequences:
- You can't easily rebalance between asset classes when they're in different places
- Tracking your total retirement portfolio requires logging into multiple platforms
- Tax treatment is handled differently across accounts, adding complexity
- Capital sitting in one account can't quickly move to an opportunity in another
When everything is in one account, portfolio management becomes more straightforward. You can see your total retirement allocation across real estate, crypto, stocks, and bonds in one place, and make decisions about rebalancing or reallocating with the full picture in front of you.
Diversification Across Uncorrelated Assets
Holding both alternative assets and publicly traded securities in the same account makes it easier to maintain a diversified retirement portfolio. Real estate and private equity tend to move independently of stock markets. Bonds can offset volatility in equity-heavy portfolios. Having all of these available within one account structure removes the friction of managing diversification across multiple platforms.
Tax Treatment Applies to All Investments Equally
Every trade you make, whether a stock, an ETF, or an options contract, happens within the tax-advantaged wrapper of your IRA or Solo 401(k). In a Traditional IRA, gains are tax-deferred until withdrawal. In a Roth IRA, qualified gains are tax-free. For active traders, that tax treatment on stock trades alone can represent meaningful savings over time compared to trading in a taxable brokerage account.
Important note on UBIT: In most cases, trading publicly listed stocks and ETFs within an IRA does not trigger Unrelated Business Income Tax (UBIT). However, certain strategies, such as using margin or trading certain partnership interests, may have different tax implications. IRA Financial's compliance team can help you understand the rules that apply to your specific situation.
Book a free call with a self-directed retirement specialist
- Review your self-directed retirement options
- Learn about investing in alternative assets
- Get all of your questions answered
How Does Compliance Work for Stock Trading Inside an IRA?
Self-Directed retirement accounts come with a set of IRS rules that don't apply to standard brokerage IRAs. The most important is the prohibited transaction rules under IRC Section 4975, which restrict certain transactions between your IRA and disqualified persons, including yourself, your spouse, and certain family members.
For stock trading specifically, most standard trades in publicly listed securities are straightforward and don't raise prohibited transaction concerns. Some situations can get more complicated, for example if you're trading securities in a company, you also have a personal ownership interest in, or if you're using leverage strategies that could trigger UBIT.
IRA Financial has a dedicated in-house compliance team that specializes in self-directed retirement accounts. Unlike custodians who process transactions without evaluating them for IRS compliance, IRA Financial's team:
- Reviews investment structures and can flag potential prohibited transaction issues before they occur
- Provides guidance on contribution limits, required minimum distributions (RMDs), and reporting requirements
- Maintains plan documents and keeps accounts in good standing with IRS requirements
- Is available to answer compliance questions specific to your account and investment strategy
This matters more as your investment activity becomes more complex. A portfolio that holds a rental property, Bitcoin, and actively traded stocks has more moving parts than one that holds only index funds, and having compliance support built into the platform reduces the risk of inadvertent rule violations.
What Does It Cost?
Understanding the fee structure matters for evaluating any retirement account platform. Here's how IRA Financial's pricing works:
| Fee Type | Details |
|---|---|
| IRA Financial Annual Fee | Flat annual fee regardless of account balance or number of investments. Your fee stays the same whether your account holds $50,000 or $2,000,000. |
| Stock & ETF Trading (U.S.-listed) | $0 commission through Interactive Brokers (IBKR Lite pricing). |
| Other Asset Classes | Options, bonds, forex, and mutual funds are priced at competitive IBKR Lite rates. |
| No AUM Fee | IRA Financial does not charge a percentage of assets under management. There is no fee that scales with your account balance. |
The flat fee structure is worth understanding in context. Many investment platforms, including some IRA custodians, charge fees as a percentage of assets. On a $500,000 account, a 1% annual AUM fee equals $5,000 per year. On a flat-fee model, that cost doesn't grow as your account grows.
That said, every investor's situation is different, and the right account structure depends on your investment goals, contribution timeline, and how actively you plan to trade. IRA Financial's team can walk through the fee structure in detail during a free consultation.
How to Open an Account and Enable Stock Trading
The setup process involves a few distinct steps. IRA Financial has created two video guides that walk through the process in detail.
How to Open Your IRA Financial Account
Covers choosing the right account type, completing your application, and funding your account.
Watch: How to Open Your IRA Financial Account
How to Invest via Interactive Brokers Inside Your IRA
Covers connecting your IRA Financial account to Interactive Brokers, navigating the trading platform, and executing your first trade.
Watch: How to Trade Stocks via Interactive Brokers Inside Your IRA
The general process looks like this:
- Choose your account structure
Decide between a Self-Directed IRA (Traditional or Roth), Checkbook IRA, or Solo 401(k) based on your employment situation, tax strategy, and investment goals. If you're unsure which structure fits, IRA Financial's team can help you evaluate the options. - Complete your application
The online application collects the information needed to establish your account. Most accounts can be opened and funded within a few days. - Fund your account
You can roll over funds from an existing IRA or 401(k), make a new annual contribution (subject to IRS limits), or transfer assets from another custodian. IRA Financial handles the transfer paperwork. - Enable Interactive Brokers access
Once your account is active, connect to Interactive Brokers through your IRA Financial dashboard. No separate brokerage application is required. - Begin trading
Use the Interactive Brokers platform to research, analyze, and execute trades within your retirement account.
Is This the Right Fit for You?
Real-time stock trading within a Self-Directed IRA makes the most sense for investors who:
- Already hold or plan to hold alternative assets (real estate, crypto, private equity) in a self-directed retirement account
- Want to consolidate their retirement portfolio, alternatives and traditional securities, into a single tax-advantaged account
- Are actively managing their own investments and want direct control over trade execution
- Are sensitive to trading costs and want to minimize commissions on stock and ETF trades
- Want compliance support built into the platform rather than navigating IRS rules independently
It's worth noting that a Self-Directed IRA involves more complexity than a standard brokerage IRA. IRS rules around prohibited transactions, contribution limits, and required minimum distributions apply, and the responsibility for staying compliant ultimately rests with the account holder. That's the trade-off for the expanded investment flexibility.
If you have questions about whether this structure fits your situation, IRA Financial offers free consultations with its team. They can walk through your current account setup, investment goals, and the steps involved in getting started.
Ready to Get Started?
Speak with an IRA Financial specialist to learn which account structure is right for you and how to enable stock trading access.
Call us at 1-800-472-0646
Open an Account | Schedule a Free Consultation
FAQs About Stock Trading in a Self-Directed IRA
Can I trade stocks inside a Self-Directed IRA?
Yes. IRA Financial's platform now supports real-time trading of stocks, ETFs, mutual funds, bonds, options, and currency/forex directly within a Self-Directed IRA, Checkbook IRA, or Solo 401(k), executed through Interactive Brokers.
Do I need a separate brokerage account to trade stocks?
No. The Interactive Brokers integration is built directly into your IRA Financial account. You don't need to open or separately fund a brokerage account, trading access is enabled through your existing IRA Financial account setup.
Are there trading commissions?
U.S.-listed stocks and ETFs trade with $0 commissions under IBKR Lite pricing. Other asset classes, options, bonds, mutual funds, and forex, are priced at standard IBKR Lite rates, which are competitive with major retail brokerage platforms.
Can I hold real estate and stocks in the same IRA?
Yes. A Self-Directed IRA can hold both alternative assets (real estate, crypto, private equity, precious metals) and publicly traded securities (stocks, ETFs, bonds) simultaneously. The account structure determines what's possible. IRA Financial's team can help you understand which structure fits your investment mix.
How does trading stocks in an IRA affect my taxes?
Trades executed within a Traditional IRA grow tax-deferred, and you pay ordinary income tax when you take distributions. Trades within a Roth IRA grow tax-free, provided you meet the qualifying distribution requirements. In either case, you don't pay capital gains tax on individual trades in the year they occur. Note that certain strategies such as margin trading or trading certain partnerships can trigger UBIT. Consult a tax professional for guidance specific to your situation.
What is IBKR Lite and why does it matter?
IBKR Lite is Interactive Brokers' retail pricing tier. It offers $0 commissions on U.S.-listed stocks and ETFs, with competitive pricing on other asset classes. For IRA investors who plan to trade actively, the elimination of per-trade commissions can meaningfully reduce costs over time.
Is this available for Roth IRAs?
Yes. Real-time stock trading is available for both Traditional and Roth IRA structures, as well as Solo 401(k) plans.
What if I want to trade options or forex in my IRA?
Options and currency/forex trading are available through the Interactive Brokers integration at standard IBKR Lite rates. These strategies may carry additional complexity from a compliance standpoint. IRA Financial's team can help you understand the applicable rules before you begin.
Disclaimer:
IRA Financial does not provide investment, tax, or legal advice. The information in this article is for educational purposes only. All investment decisions are made solely by the account holder. Trading securities involves risk, including possible loss of principal. Self-Directed retirement accounts are subject to IRS rules and regulations, including prohibited transaction rules under IRC Section 4975. Please consult with a qualified financial advisor, tax professional, or legal counsel before making investment decisions. Past performance is not indicative of future results.
The Smartest Thing You Can Do with Your Tax Refund
Every year, millions of Americans receive a tax refund and treat it like a bonus. A vacation. A new piece of furniture. A few months of caught-up bills. And while none of those things are wrong, they all have one thing in common: the money is gone, and it does not come back.
Here is the reality. Your tax refund is not a gift from the government. It is your own money that you overpaid throughout the year, returned to you without interest. The question is not whether to enjoy it. The question is whether you are going to let it disappear or put it to work.
I have spent 25 years helping people build wealth through tax-advantaged accounts, and one of the most consistent patterns I see is this: the people who treat their tax refund as capital rather than cash are the ones who end up significantly ahead. The difference is not dramatic in any single year. But compounded over decades, it is enormous.
The IRS issues more than $300 billion in refunds every year, with the average refund falling between $2,800 and $3,500. That is a meaningful lump sum for most households. Here is how to make it count.
The Most Powerful Place to Put It
If there is one account, I would point almost every American toward with their tax refund, it is the Self-Directed Roth IRA. I have said it before and I will keep saying it: the Roth IRA is the best legal tax shelter available to everyday Americans, and most people are not using it to its full potential.
A Roth IRA is funded with after-tax dollars, meaning you do not get a deduction when you contribute. But in exchange, the money grows completely tax free, and qualified withdrawals in retirement are also tax free. No income tax. No capital gains tax. No required minimum distributions during your lifetime.
For 2026, the contribution limit is $7,500, or $8,600 if you are age 50 or older. Income phase-outs begin at approximately $168,000 for single filers and $252,000 for married filing jointly. If your income exceeds those thresholds, the backdoor Roth IRA strategy allows you to contribute regardless of income by making a nondeductible traditional IRA contribution and converting it to Roth. It is one of the most widely used and effective strategies for high earners, and it remains fully available in 2026.
Here is what the numbers look like in practice. If you invest $3,000 annually starting at age 30 and continue through age 70 at an 8% average annual return, you end up with approximately $840,000. Every dollar of that is tax free. The same investment in a taxable account, subject to capital gains taxes along the way, would produce significantly less. The Roth does not just grow your money. It protects it from the one thing that quietly erodes wealth over time: taxes.
Immediate Tax Relief with Long-Term Growth
If you prefer a tax benefit today rather than in retirement, or if your situation makes a Roth less appealing, a traditional IRA is a strong alternative.
Contributions to a traditional IRA may be tax deductible, which means you reduce your taxable income in the year you contribute. The funds grow tax deferred, and you pay ordinary income tax when you withdraw in retirement. The contribution limits are the same as the Roth: $7,500 for 2026, or $8,600 if you are 50 or older.
The deductibility of your contribution depends on whether you have access to a workplace retirement plan. If you have no 401(k), a full deduction is generally available regardless of income. If you do have a 401(k), the deduction phases out at $91,000 for single filers and $149,000 for married filers covered by a workplace plan. If you are not covered by a plan but your spouse is, the phase-out begins at $252,000.
The traditional IRA is particularly well suited for people who expect to be in a lower tax bracket in retirement than they are today, or for those who want to reduce their tax bill right now and will decide later how to manage the tax on the back end. Required minimum distributions begin at age 73, and early withdrawals before age 59 and a half may trigger taxes and penalties, so this account works best as a genuine long-term savings vehicle.
Investing in Your Child's Future
If you have children, your tax refund can do double duty by funding their education while also growing tax free.
A Coverdell Education Savings Account allows you to contribute up to $2,000 per year per child, and the money grows tax free and can be withdrawn tax free for qualified education expenses. That includes K through 12 tuition, college costs, books, supplies, and more. Contribution eligibility phases out at $110,000 for single filers and $220,000 for married filers.
What makes the Coverdell particularly interesting is that it can be self-directed, meaning you are not limited to a standard menu of mutual funds. You can invest in stocks, ETFs, real estate, private businesses, and other alternative assets, which gives you the ability to tailor the account to your strategy and risk tolerance in ways that most education savings plans do not allow.
The $2,000 annual limit may not seem like much, but compounding makes it meaningful over time. A parent who contributes $2,000 per year for 30 years at an 8% average return and then lets the account grow for another 35 years would end up with over $1 million in tax-free education funds. Even on a shorter horizon, $2,000 per year for 30 years at 8% grows to roughly $245,000, which can cover a substantial portion of education costs without touching a dollar of taxable income.
The Most Tax-Advantaged Account Most People Ignore
If you are eligible, the Health Savings Account is arguably the most tax-efficient account in the entire tax code. I say arguably because the Roth IRA is my personal favorite, but the HSA has an advantage that no other account can match: it is triple tax advantaged.
Contributions are tax deductible. Growth is tax free. And withdrawals for qualified medical expenses are also tax free. No other account gives you all three.
For 2026, the contribution limit is $4,400 for individuals and $8,750 for families, with an additional $1,000 catch-up for those age 55 and older. To be eligible, you must be enrolled in a high deductible health plan.
The strategy I recommend to clients who can afford it is to pay medical expenses out of pocket and leave the HSA invested for as long as possible. At age 65, you can withdraw funds for any purpose. If used for medical expenses, the withdrawal is completely tax free. If used for anything else, it is taxed like a traditional IRA distribution, which is still a favorable outcome. Given that healthcare is one of the largest expenses in retirement, an HSA that has been growing for decades can be one of the most valuable assets you have.
Using Your Refund to Unlock Free Money
This strategy is a little different from the others, but it is one of the most powerful options available to employees with access to an employer match.
Rather than depositing your refund directly into a 401(k), you use it to cover everyday living expenses, which allows you to increase your payroll contributions without reducing your take-home pay. The net effect is that more of your income goes into a tax-advantaged account without changing how you live day to day.
For 2026, the employee deferral limit is $24,500, with an $8,000 catch-up for those 50 and older, and an $11,250 enhanced catch-up for those between ages 60 and 63. Combined with employer contributions, total plan additions can reach $72,000, $80,000 for those over 50, and $83,250 for those in the 60 to 63 age range.
If your employer offers a match, increasing your contributions can unlock dollars that are essentially free money. Here is a simple example. You earn $100,000 and your employer matches 100% of the first 3% of salary, which equals $3,000. If you are not contributing enough to capture the full match, you are leaving $3,000 of free money on the table every year. Use your refund to cover your expenses and increase your payroll contribution enough to capture the full match, and that $3,000 employer contribution doubles your effective return before the money is even invested.
If that additional $6,000 grows at 8% annually over 30 years, it becomes roughly $60,000. That is the difference between spending your refund and deploying it strategically.
401(k) contributions can be made on a pretax or Roth basis, and the plan also includes a loan feature that allows you to borrow the lesser of $50,000 or 50% of your account balance without triggering taxes or penalties, provided the loan is repaid on schedule.
Book a free call with a self-directed retirement specialist
- Review your self-directed retirement options
- Learn about investing in alternative assets
- Get all of your questions answered
Making the Decision
Your tax refund is not extra money. It is capital that is briefly in your hands, and what you do with it in the next few weeks will either compound in your favor for decades or disappear without a trace.
The right account depends on your situation. If you want tax-free retirement income and you qualify, the Roth IRA is where I would start. If you want an immediate tax deduction, the traditional IRA is worth considering. If you have children, the Coverdell ESA can turn a modest annual contribution into a meaningful education fund. If you have a high-deductible health plan, the HSA is one of the most efficient accounts available. And if your employer offers a match, you are not fully capturing, increasing your 401(k) contribution is one of the few genuinely risk-free returns in investing.
You do not have to choose just one. A $3,500 refund could fund a Roth IRA contribution, top off an HSA, and still leave room to increase a payroll contribution. The point is to treat it as a decision rather than a windfall.
Wealth is not built in one dramatic moment. It is built through consistent, intentional decisions made year after year.
Your tax refund is one of those decisions.
Make it count.
How to Add Cryptocurrency to Your Retirement Account: A Step‑by‑Step Guide
Cryptocurrency has moved from the fringes of investing to a mainstream asset class. Yet most retirement savers still have no exposure to it, not because it is off limits, but because they do not know it is an option. A Self-Directed IRA or Solo 401(k) lets you hold digital assets inside a tax-advantaged account, the same way you would hold stocks or real estate.
Key Takeaways:
- Account types and definitions
- Funding mechanics and timelines
- Trading and custody via dedicated platforms
- IRS tax rules and compliance
- SDIRA LLC checkbook control and how it works
- A feature comparison framework to evaluate providers
The focus is practical: what to do, why it matters, and how to verify each step so you can confidently hold Bitcoin, Ethereum, and other tokens inside a retirement account.
What Is a Crypto IRA and How Does It Work for Retirement Investing?
A Crypto IRA is a self-directed retirement account that holds cryptocurrencies while keeping the tax advantages of an IRA or Solo 401(k). Ownership is structured through a qualified custodian or a Self-Directed IRA LLC that holds title to the assets. Trades happen either with custodian-managed custody or directly using checkbook control.
That structure lets gains compound tax-deferred or, in the case of a Roth, tax-free inside the retirement wrapper. The main benefit is access to crypto's upside without triggering capital gains tax along the way. That said, volatility and custody risk are real considerations that every investor should understand before getting started.
The table below summarizes common retirement account types so you can align features with your tax objectives and contribution flexibility.
| Account Type | Tax Treatment | Typical Use Case |
| Traditional IRA | Tax-deferred growth; distributions taxed as ordinary income | Investors seeking current-year deductions and tax-deferred compounding |
| Roth IRA | Tax-free growth; qualified withdrawals are tax-free | Long-term growth investors expecting higher tax rates later |
| SEP IRA | Tax-deferred for employer or self-employed contributions | Small business owners needing flexible employer contributions |
| Solo 401(k) | Tax-deferred or Roth options; higher contribution limits | Self-employed individuals looking to maximize retirement savings |
What Are Self-Directed Crypto IRAs and Their Benefits?
Self-Directed Crypto IRAs widen investment choice beyond stocks and mutual funds by allowing approved alternative assets. With a Self-Directed IRA you either appoint a qualified custodian to hold digital assets or set up an SDIRA LLC so the account can act through a manager-controlled bank account.
The benefits are real: portfolio diversification, access to tokenized and private investments, and direct exposure to crypto price movements inside a tax-advantaged account. The tradeoffs are also worth understanding. Custody is more complex than a standard brokerage, certain strategies can trigger UBIT, and recordkeeping demands are heavier. Those factors drive the decision between custodian custody and SDIRA LLC checkbook control.
How Do Roth Crypto IRAs and Traditional Crypto IRAs Differ?
Roth and Traditional Crypto IRAs use the same custody mechanics but differ in tax treatment and withdrawal rules, which has a meaningful impact on long-term planning.
Roth Crypto IRAs accept after-tax contributions and offer tax-free qualified distributions. If you expect large long-term gains from crypto, that tax-free treatment on the back end can be significant. Traditional Crypto IRAs provide tax-deferred growth: pre-tax contributions lower your current taxable income, but withdrawals are taxed as ordinary income when taken.
Choosing between them depends on your expected tax rate in retirement, contribution eligibility, and your outlook on crypto's long-term performance.
How to Open and Fund a Crypto IRA or Solo 401(k) with IRA Financial
Opening and funding a Crypto IRA or Solo 401(k) comes down to three things: choosing the right account, completing the necessary paperwork, and moving funds in a way that preserves your tax status.
Start by confirming whether a Traditional IRA, Roth IRA, or Solo 401(k) makes sense for your situation. Then decide between custodian custody and an SDIRA LLC for checkbook control. From there, submit your identity verification and beneficiary forms.
If you opt for an SDIRA LLC, you will need to complete the formation documents and operating agreement so the IRA is the LLC member and you act as manager. Once setup is complete, fund the account and route assets into the IRAfi Crypto trading environment or your SDIRA LLC bank account to begin investing.
The table below summarizes the most common funding methods so you can choose the approach that fits your timeline.
| Funding Method | Key Characteristics | Typical Timeline |
| Trustee-to-Trustee Transfer | Direct institution-to-institution transfer that preserves tax status; no taxable event | 1-4 weeks depending on custodians |
| 401(k) Rollover | Moves employer plan assets into an IRA; must follow rollover rules to avoid taxes | 2-6 weeks including employer paperwork |
| Direct Contribution | Annual after-tax or pre-tax contributions subject to IRS limits | Immediate once deposited |
What Are the Steps to Set Up an IRA Financial Crypto IRA Account?
Setting up an IRA Financial crypto account follows a straightforward sequence. Here is what the process looks like:
- Choose your account type (Traditional IRA, Roth IRA, or Solo 401(k)) based on your tax strategy and eligibility
- Submit identity verification and beneficiary designation forms to the custodian
- If using an SDIRA LLC, complete the formation documents and operating agreement
- Activate custodian-managed custody or request IRAfi Crypto trading access
- Fund the account using a transfer, rollover, or direct contribution
Account openings typically take a few days. Forming an SDIRA LLC may add a few weeks to the timeline, so preparing documents in advance and coordinating trustee-to-trustee transfers helps reduce delays.
How to Fund Your Crypto IRA: Transfers, Rollovers, and Contributions
Each funding method works a little differently, and choosing the right one matters for your tax position.
Trustee-to-trustee transfers move assets directly between custodians without creating a taxable event. Rollovers move qualified plan assets into an IRA and are safe when handled as a direct trustee transfer. If you take a distribution and redeposit it yourself, the 60-day rule applies and missing it can trigger taxes. Direct contributions add after-tax or pre-tax funds within IRS annual limits.
Regardless of the method you use, keep thorough records including transfer paperwork, rollover forms, and contribution receipts. Good documentation protects your tax position and prevents accidental taxable distributions.
How to Invest in Bitcoin and Other Cryptocurrencies Within Your Retirement Account
Investing in crypto inside an IRA or Solo 401(k) requires a clear execution path, a custody decision, thoughtful asset selection, and disciplined recordkeeping.
Execution options include an integrated trading platform tied to the custodian, or using an SDIRA LLC checkbook account to trade on external exchanges. Custody determines who controls the private keys and how cold storage or insurance is handled. When selecting assets, focus on liquidity, market cap, and regulatory clarity. Bitcoin and Ethereum are common core holdings, while smaller tokens may offer diversification but require deeper due diligence.
Regular monitoring, rebalancing, and accurate transaction records keep the account aligned with your retirement goals and satisfy IRS reporting requirements.
Which Cryptocurrencies Can You Invest in Through IRA Financial?
IRA Financial supports over 40 popular cryptocurrencies appropriate for retirement portfolios, generally focused on top-tier tokens with strong liquidity and clearer regulatory standing. Bitcoin and Ethereum are the most common core holdings, with select altcoins and tokenized assets also available.
Asset selection emphasizes market capitalization, exchange liquidity, on-chain transparency, and legal and regulatory risk. Before adding less-liquid assets to your retirement account, verify token provenance, exchange counterparty reputation, and whether a token's protocol or yield strategy could trigger UBIT. Document your research and consult a tax advisor for anything outside the major tokens.
Book a free call with a self-directed retirement specialist
- Review your self-directed retirement options
- Learn about investing in alternative assets
- Get all of your questions answered
How Does IRAfi Crypto Enable 24/7 Trading and Secure Transactions?
IRAfi Crypto lets retirement investors place crypto trades around the clock, routing orders through exchange integrations while relying on custody partnerships that separate execution from long-term cold storage.
The ability to trade 24/7 matters in a global, always-on market where price moves don't wait for U.S. business hours. Security is layered: custody partners and cold storage isolate long-term holdings from the hot wallets used for active trading. The platform also emphasizes fee transparency, including no annual custody asset holding fees for certain custody flows.
Understanding how order routing, custody partners, and storage policies work together helps you align your trading activity with your risk tolerance.
What Are the Tax Advantages and IRS Rules for Crypto IRAs and Solo 401(k)s?
Crypto held inside an SDIRA or Solo 401(k) benefits from the tax treatment of the account. Traditional accounts offer tax-deferred growth. Roth accounts permit tax-free qualified withdrawals. Both can materially change your after-tax returns from volatile crypto gains compared to holding crypto in a taxable account.
The IRS classifies cryptocurrency as property, so trades inside retirement accounts follow IRA rules rather than triggering annual capital gains reporting. That said, certain strategies can generate Unrelated Business Taxable Income (UBIT), so it is worth understanding which activities carry that risk before pursuing them.
Accurate documentation and trustee-to-trustee transfers help avoid inadvertent taxable events. For Traditional IRAs, plan your distributions with RMD timing and your overall tax rate in mind.
How Does Tax-Deferred and Tax-Free Growth Work in Crypto IRAs?
In a Traditional Crypto IRA, gains compound without annual tax drag, producing larger pre-withdrawal accumulation. In a Roth Crypto IRA, qualified withdrawals are tax-free, which can dramatically improve net returns if crypto appreciates significantly over time.
Holding Bitcoin in a Roth IRA, for example, could allow years of appreciation to escape the capital gains taxes that would apply in a taxable account. By contrast, Traditional IRA withdrawals are taxed as ordinary income when taken. Roth IRAs also avoid required minimum distributions, while Traditional IRAs do not. Match your account choice to your time horizon and expectations for crypto performance.
What IRS Regulations Should You Know About Cryptocurrency in Retirement Accounts?
The key IRS considerations are crypto's classification as property, strict transaction recordkeeping, and the possibility that certain crypto-backed lending or yield activities create UBIT inside tax-advantaged accounts.
Maintain records showing acquisition dates, cost basis inside the IRA, and how transfers and trades were executed. Custodians and account holders share responsibility for correct reporting. Regulatory guidance continues to evolve, so conservative compliance practices are advisable. Consult a tax professional before pursuing complex strategies such as staking, lending, or tokenized securities.
How Does IRA Financial's Checkbook Control and SDIRA LLC Structure Enhance Crypto Investing?
An Self-Directed IRA LLC, also known as a Checkbook IRA, places the IRA as the LLC's sole member and names you as manager. You run a dedicated bank account on the IRA's behalf, giving you practical checkbook control over investments without requiring custodian approval for each transaction.
Checkbook control reduces approval delays and enables faster execution for time-sensitive crypto trades or private investments. The tradeoffs are real: you must avoid prohibited transactions, keep meticulous records, and ensure every action you take as manager is for the IRA's benefit. Done correctly, the structure provides execution speed while maintaining the IRA's tax advantages.
What Is an IRA LLC and How Does It Provide Full Checkbook Control?
An SDIRA LLC is formed with the IRA as the sole member. The IRA funds the LLC and designates a manager who can write checks and direct investments from the LLC bank account, allowing direct purchases without repeated custodian signoffs.
Setup requires formation documents, an operating agreement that documents IRA ownership, and coordination with the custodian to fund the LLC. Once funded, the manager executes transactions for the IRA's benefit. That workflow simplifies crypto purchases on exchanges or in OTC markets where speed matters. Strong documentation, separate bank accounts, and strict compliance with IRS prohibited transaction rules protect the IRA's tax status throughout.
How Does Checkbook Control Enable Immediate Cryptocurrency Transactions?
Checkbook control reduces latency by letting the IRA manager direct transactions from the LLC account directly, avoiding the multi-day approval cycles some custodians require. In a volatile market, that speed can matter.
For example, a manager can move funds from the LLC bank account to an exchange wallet and complete a crypto purchase within hours rather than days. To keep that process compliant, best practices include maintaining transaction logs, using dual-signature banking controls, and conducting periodic audits that align with IRA recordkeeping requirements. Those safeguards balance speed with the fiduciary responsibility to protect retirement assets.
How to Compare IRA Financial's Crypto IRA with Other Providers
When comparing providers, the factors that matter most are supported assets, custody model, trading hours, fees, availability of checkbook control, and security practices.
| Provider Feature | Characteristic | Practical Impact |
| Trading Hours | 24/7 trading availability | Allows execution across global crypto markets at any hour |
| Custody Model | Custodian custody or SDIRA LLC checkbook control | Determines who holds keys and how quickly you can execute |
| Fees | Trading fees and custody holding fees | Impacts long-term net returns; avoiding annual custody fees reduces drag |
| Alternative Investments | Support for private equity and tokenized assets | Expands diversification options inside retirement accounts |
When evaluating any provider, verify custody insurance limits, supported asset lists, checkbook availability, and any approval requirements or fees that could slow execution.
What Are the Key Differences Between IRA Financial and Competitors Like BitIRA or Fidelity?
Providers vary in meaningful ways. Some focus on custodial Crypto IRAs with third-party custody and limited alternative asset support. Others, like IRA Financial, enable checkbook control and private investment access that expands both choice and speed.
IRA Financial's IRAfi Crypto offering combines 24/7 trading with custody integrations and fee transparency, including no annual custody asset holding fees for certain custody flows. When comparing vendors, verify custody insurance limits, supported asset lists, checkbook availability, and any hidden fees that could affect long-term returns.
How Does IRA Financial Address Security and Risk Mitigation for Crypto Investments?
Security for retirement crypto investing centers on custody partnerships, cold storage practices, layered access controls, and diversification to limit concentration risk. IRA Financial separates active trading environments from long-term cold storage to reduce hot wallet exposure, and emphasizes governance for SDIRA LLC setups to support compliant checkbook operations.
Beyond the platform itself, investors should follow these core practices:
- Use custody segmentation: Keep trading hot wallets separate from long-term cold storage to reduce breach exposure
- Confirm custodian insurance: Verify counterparty insurance limits and custodial protections where available
- Limit concentration: Set allocation caps to avoid excessive exposure to a single token
- Maintain records: Keep transaction logs, transfer documents, and custody statements for IRS and audit readiness
Conclusion
Adding cryptocurrency to your retirement account can broaden diversification and offer meaningful tax advantages if approached carefully. Understanding how Crypto IRAs and Solo 401(k)s operate, from custody choices to funding mechanics and IRS rules, puts you in a position to make decisions that align with your long-term financial goals.
Review provider features, custody safeguards, and governance options before committing. And consult qualified tax and legal advisors before pursuing complex strategies. If you are ready to move forward, IRA Financial's team is available to walk through your options and help you get set up.
Frequently Asked Questions
Can I hold multiple cryptocurrencies in my retirement account?
Yes. Many custodians permit multiple cryptocurrencies inside a Crypto IRA or Solo 401(k). Major tokens like Bitcoin and Ethereum are commonly supported, along with select altcoins. Check your custodian's supported asset list and any restrictions before investing.
What are the risks associated with investing in cryptocurrencies through retirement accounts?
Risks include high market volatility, evolving regulation, and custody complexity. Crypto prices can swing widely, which directly affects retirement balances. Mitigate risk by using reputable custodians, keeping detailed records, and consulting financial and tax professionals before adopting advanced strategies.
How do I ensure compliance with IRS regulations when investing in crypto?
Maintain accurate records of all transactions including acquisition dates and internal cost basis, and preserve all transfer documentation. Avoid prohibited transactions, be aware of UBIT rules that apply to certain yield strategies, and work with a tax professional experienced in cryptocurrency.
What is the process for rolling over a 401(k) into a Crypto IRA?
Confirm rollover eligibility with your plan administrator, then contact your current 401(k) provider to initiate the process. Whenever possible, request a trustee-to-trustee transfer to avoid tax consequences. Once the receiving custodian accepts the funds, you can direct those assets into crypto investments within the new Crypto IRA.
Are there contribution limits for Crypto IRAs similar to traditional IRAs?
Yes. Crypto IRAs follow the same contribution limits as traditional IRAs. For 2026, the annual limit is $7,500, or $8,600 if you are age 50 or older, across all IRAs you own. Solo 401(k) contribution limits are higher, so self-employed savers can shelter more under that structure.
What are the tax implications of withdrawing from a Crypto IRA?
Tax treatment depends on the account type. Withdrawals from a Traditional Crypto IRA are taxed as ordinary income and may incur penalties if taken before age 59½. Qualified withdrawals from a Roth Crypto IRA are tax-free if holding-period and age rules are met. Plan distributions with your broader retirement tax strategy in mind.
How can I protect my cryptocurrency investments in a retirement account?
Choose a reputable custodian with strong security and cold storage practices, use multi-factor authentication, and keep comprehensive transaction records. Monitor accounts regularly, diversify holdings to reduce concentration risk, and consult advisors who specialize in crypto retirement planning.
Self-Directed IRA vs. Brokerage Account: Key Differences Explained
Most investors begin with a brokerage account. It is familiar, easy to open, and provides direct access to the financial markets. As your financial goals evolve, it becomes important to look beyond convenience and consider how your investment strategy supports long-term, tax-efficient growth.
Understanding the differences between a brokerage account and a Self-Directed IRA can help you make more informed decisions about how and where to invest.
What Is a Brokerage Account?
A brokerage account is a taxable investment account that allows you to buy and sell assets such as stocks, bonds, mutual funds, and ETFs. There are no limits on contributions, and funds can generally be accessed at any time.
This flexibility makes brokerage accounts a practical option for short-term investing and liquidity needs. However, investment income, including dividends, interest, and capital gains, is typically subject to taxation in the year it is earned. As a result, ongoing tax liability may reduce the amount of capital that remains invested over time.
What Is a Self-Directed IRA?
A Self-Directed IRA is a retirement account that allows you to direct your investments into a broader range of assets beyond traditional securities. While it follows the same IRS framework as other IRAs, it provides access to alternative investments such as real estate, private equity, and cryptocurrency.
Depending on whether the account is structured as a Traditional or Roth IRA, earnings are typically tax-deferred or, in the case of a Roth IRA, may be tax-free if IRS requirements are satisfied.
With a Self-Directed IRA, you make the investment decisions, subject to IRS rules and custodial requirements. This structure gives investors the ability to align their retirement strategy with their knowledge and experience.
Book a free call with a self-directed retirement specialist
- Review your self-directed retirement options
- Learn about investing in alternative assets
- Get all of your questions answered
Key Differences to Consider
Investment Flexibility
Brokerage accounts are generally limited to publicly traded securities and market-based investments.
A Self-Directed IRA allows for a wider range of investment options, including alternative assets. This expanded access can support greater diversification, depending on your investment strategy and risk tolerance.
Tax Treatment
Tax treatment is one of the most important distinctions between these accounts.
In a brokerage account, taxes are typically due each year on realized gains and investment income. This ongoing tax exposure can affect long-term compounding.
With a Self-Directed IRA, taxes are generally deferred until distribution in a Traditional IRA, or may be avoided on qualified distributions in a Roth IRA if IRS conditions are met. The impact on long-term growth will depend on individual circumstances, including tax position and investment performance.
Control Over Investments
A brokerage account often involves a more passive approach, with many investors relying on advisors, model portfolios, or fund managers.
A Self-Directed IRA allows you to take a more active role by directing your own investments. All decisions must be made in accordance with IRS guidelines, including rules regarding prohibited transactions and disqualified persons.
Contribution Rules and Access
Brokerage accounts do not impose contribution limits, and funds can generally be withdrawn without restriction.
Self-Directed IRAs are designed for retirement savings and are subject to annual contribution limits set by the IRS. Withdrawals prior to retirement age may be subject to taxes and penalties, depending on the circumstances.
Complexity and Responsibility
Brokerage accounts are relatively simple to manage and require minimal oversight.
A Self-Directed IRA involves additional responsibilities. Investors must understand and follow IRS regulations, perform appropriate due diligence, and ensure that all investments remain compliant. Alternative investments may also involve additional risks, including limited liquidity and less transparency compared to publicly traded assets.
Which Account Makes Sense for You?
The appropriate account depends on your financial goals, investment experience, and need for flexibility.
A brokerage account may be suitable for those who prioritize liquidity and ease of use, particularly for shorter-term strategies.
A Self-Directed IRA may offer advantages for investors focused on long-term, tax-advantaged growth and broader diversification, provided they are comfortable taking an active role and managing the associated responsibilities.
Some investors choose to use both account types as part of a diversified strategy, balancing accessibility with long-term planning.
The Bottom Line
You are not limited to a single approach when building wealth.
A Self-Directed IRA can provide greater flexibility in how you invest for retirement, along with potential tax advantages depending on your individual situation. When used appropriately and in compliance with IRS rules, it can serve as a valuable component of a long-term investment strategy.
Disclaimer: This content is for informational purposes only and does not constitute legal, tax, or investment advice. Investors should consult with a qualified professional before making financial decisions.