

How the Solo 401(k) Loan Can Save You Thousands in Credit Card Interest
If there is one financial trend that concerns me more than almost anything else today, it is the explosion of high-interest consumer debt. As a tax attorney, I spend my days helping entrepreneurs and investors legally reduce taxes and build long-term wealth. Yet I constantly meet successful business owners who are paying 20%, 25%, or even 30% interest on credit cards while simultaneously contributing to retirement accounts.
That simply does not make financial sense.
Far too many Americans are trapped in a cycle of debt. They make monthly credit card payments, but because interest rates are so high, very little of those payments actually reduce the principal balance. Others turn to payday loans or short-term cash advances that carry even higher effective interest rates, making it nearly impossible to get ahead.
Fortunately, if you are self-employed, there may be a much better solution that most financial advisors rarely discuss: the Solo 401(k) loan. Used responsibly, it can allow you to pay off expensive credit card debt, eliminate payday loans, improve your cash flow, and unlike borrowing from a bank, the interest you pay goes back into your own retirement account instead of enriching a credit card company.
Key Takeaways
- Americans owe nearly $1.25 trillion on credit cards, with average interest rates above 20%. Every dollar paid in interest is a dollar that cannot be invested or saved for retirement.
- A Solo 401(k) participant can borrow up to $50,000 or 50% of their vested account balance, whichever is less, with no credit check and no underwriting process.
- Unlike a bank loan, the interest paid on a Solo 401(k) loan goes back into your own retirement account rather than to a lender.
- The loan can be used for any purpose, including paying off high-interest credit card balances, covering unexpected expenses, or managing temporary business cash flow needs.
- The Solo 401(k) loan feature is not available in an IRA. It is unique to qualified retirement plans.
America's Credit Card Debt Problem
Americans owe nearly $1.25 trillion on their credit cards, while average credit card interest rates have climbed above 20%, with many consumers paying 24% or even 30%. Millions more rely on payday loans and other forms of emergency financing that can carry annualized rates approaching 400%. The result is staggering: Americans now pay well over $250 billion each year in credit card interest and fees, money that goes directly to banks and credit card companies instead of helping families build wealth.
The problem is not borrowing money itself. Businesses borrow every day to grow, and consumers occasionally need access to credit for unexpected expenses. The real problem is the cost of that debt. At rates of 20% to 30%, borrowers can spend years making payments while barely reducing the principal balance. A $30,000 credit card balance at 24% generates roughly $7,200 of interest every year if the balance remains outstanding. Instead of building wealth, you are effectively paying thousands of dollars annually to a credit card company simply for the privilege of borrowing money.
Every dollar paid in interest to a credit card company is a dollar that can never be invested, never earn compound returns, and never help fund your retirement. Over decades, that lost opportunity can amount to hundreds of thousands of dollars.
The Solo 401(k): One of the Most Powerful Retirement Plans Ever Created
The Solo 401(k) is available to almost anyone with self-employment income, whether you operate a full-time business, own an LLC, work as an independent contractor, earn consulting income, or have a profitable side hustle. To establish one, you must have self-employment income and generally cannot employ full-time employees other than yourself and, if applicable, your spouse.
For 2026, participants can generally contribute up to $72,000, with even higher limits available for those eligible for catch-up contributions. Contributions may be made on a pre-tax basis, reducing current taxable income, or as Roth contributions, allowing investments to grow completely tax-free if the distribution requirements are satisfied.
A properly designed Solo 401(k) also offers checkbook control, meaning you serve as trustee of your own plan and can write checks or initiate wires directly from the plan's bank account without waiting for custodian approval on every transaction. That flexibility opens the door to far more than traditional stocks and mutual funds, including cryptocurrency, rental real estate, private equity, venture capital, private lending, precious metals, and many other alternative assets.
The plan also enjoys excellent creditor protection under both federal and state law, and when purchasing real estate with a nonrecourse loan, a Solo 401(k) is generally exempt from the Unrelated Debt-Financed Income tax that typically applies to leveraged real estate owned by an IRA.
Despite all of these benefits, there is one feature that receives far too little attention: the ability to borrow from your own retirement account.
How the Solo 401(k) Loan Works
Unlike an IRA, a Solo 401(k) can generally allow participants to borrow from their retirement savings without triggering taxes or penalties, provided the loan satisfies the requirements of the Internal Revenue Code and the terms of the plan document.
Generally, a Solo 401(k) participant may borrow the lesser of $50,000 or 50% of the vested account balance. If your balance is $60,000, you can borrow up to $30,000. If your balance is $100,000 or more, you can generally borrow the maximum $50,000.
There is no credit check. Your credit score does not matter, your debt-to-income ratio does not matter, and there is no lengthy underwriting process. As long as your plan permits participant loans and you satisfy the IRS requirements, you can generally access the funds quickly.
The proceeds can be used for virtually any purpose: paying off high-interest credit card balances, eliminating payday loans, covering unexpected medical expenses, making home repairs, funding college tuition, consolidating debt, covering temporary business expenses, or simply providing short-term liquidity during a difficult period.
Repayment is generally required over no more than five years through substantially level installments of principal and interest, unless the loan is used to purchase a primary residence, in which case a longer repayment period may be permitted.
Now here is the part that changes the economics entirely. When you borrow from a bank, every interest payment benefits the bank. When you borrow from a Solo 401(k), the interest you pay is credited back to your own retirement account. You are paying yourself instead of paying a lender.
Using the current Prime Rate as an example, if your plan carries a 6.75% interest rate and you borrow $10,000 to eliminate credit card debt charging 24%, you are paying approximately $675 in annual interest rather than $2,400, and every dollar of that interest flows back into your own retirement account.
One important tradeoff: while the money is out on loan, it is no longer invested in the market. If the market performs exceptionally well during that period, you may miss some investment gains. That is why I generally recommend using a Solo 401(k) loan only when it serves a meaningful financial purpose, such as eliminating high-interest debt, not for unnecessary spending.
Book a free call with a self-directed retirement specialist
- Review your self-directed retirement options
- Learn about investing in alternative assets
- Get all of your questions answered
Case Study 1: Eliminating $40,000 of Credit Card Debt
John is a 45-year-old self-employed marketing consultant who has accumulated $200,000 in his Solo 401(k). After several slow business months, he relied on credit cards and now carries $40,000 in debt at 24% interest.
He has two options.
If John continues making credit card payments, his $40,000 balance generates approximately $9,600 of interest every year at 24%. Over five years of disciplined repayment, his monthly payment would be approximately $1,150 and he would pay nearly $29,000 in total interest directly to the credit card company.
Instead, John borrows $40,000 from his Solo 401(k) at 6.75% and immediately pays off every credit card balance. Repaid over five years, his monthly payment drops to approximately $787 and he pays approximately $7,200 in total interest, every dollar of which goes back into his own retirement account.
| Solo 401(k) Loan | Credit Card at 24% | |
|---|---|---|
| Monthly Payment | ~$787 | ~$1,150 |
| Total Interest Over Five Years | ~$7,200 | ~$29,000 |
| Interest Paid To | Your retirement account | The credit card company |
By using the Solo 401(k) loan, John lowers his monthly payment by more than $350, saves roughly $22,000 in interest, and redirects approximately $7,200 back into his own retirement account instead of a bank's pocket.
Case Study 2: Eliminating $13,000 of Credit Card Debt
Sarah is a self-employed consultant with $13,000 of credit card debt at 24% interest and more than $26,000 in her Solo 401(k), making her eligible to borrow up to $13,000.
Rather than continuing to pay 24% interest, Sarah borrows $13,000 from her Solo 401(k) at 6.75% and immediately pays off her balance. Repaid over five years, her monthly payment is approximately $256 and she pays approximately $2,340 in total interest back into her own account.
If Sarah had kept the credit card balance and committed to paying it off over the same five years, her monthly payment would have been approximately $374 and she would have paid roughly $9,450 in interest to the credit card company.
| Solo 401(k) Loan | Credit Card at 24% | |
|---|---|---|
| Monthly Payment | ~$256 | ~$374 |
| Total Interest Over Five Years | ~$2,340 | ~$9,450 |
| Interest Paid To | Your retirement account | The credit card company |
By using the Solo 401(k) loan, Sarah reduces her monthly payment by approximately $118, saves about $7,100 in borrowing costs, and redirects more than $2,300 of interest back into her own retirement account.
The Same Strategy Works for Payday Loans
The benefits become even more dramatic when payday loans are involved. Payday loans can carry annualized interest rates that exceed several hundred percent, and many borrowers repay one only to immediately take out another, creating a cycle that is extremely difficult to escape.
Consider a self-employed graphic designer who has built a Solo 401(k) worth $120,000 and finds herself with $15,000 in payday loans and high-interest cash advances after unexpected medical bills and several slow business months. Rather than continuing to refinance those loans at exorbitant rates, she borrows $15,000 from her Solo 401(k), immediately eliminates every payday loan, and begins repaying herself at a fraction of the cost. The payday loan cycle ends, her borrowing cost drops dramatically, her monthly payments become manageable, and every interest payment now rebuilds her retirement savings instead of going to a lender.
An Important Word of Caution
The Solo 401(k) loan is not a tool for financing vacations, luxury purchases, or unnecessary spending. The purpose of this strategy is to replace very expensive debt with far less expensive debt while allowing you to repay yourself rather than a financial institution.
Used responsibly, it can help business owners regain control of their finances, improve cash flow, reduce interest expense, and continue building long-term retirement wealth. But discipline is essential. If you eliminate your credit card balances only to run them up again, you have simply created a new financial problem. Used as a one-time tool to break free from high-interest debt with a commitment to responsible borrowing going forward, it can be one of the smartest financial decisions a self-employed individual ever makes.
Final Thoughts
The Solo 401(k) is one of the most powerful retirement plans available to self-employed Americans. It offers high contribution limits, valuable tax deductions, Roth contribution options, checkbook control, access to alternative investments, and the unique ability to borrow from your retirement savings without creating a taxable distribution when the loan is properly structured and repaid. No IRA offers that combination.
If you are self-employed and carrying high-interest credit card debt, do not assume your only choices are expensive personal loans, debt settlement companies, or payday lenders. The Solo 401(k) loan may be a far better alternative, one where you borrow from yourself at a fraction of the cost and repay the interest back into your own retirement account.
At IRA Financial, we have helped tens of thousands of entrepreneurs establish Solo 401(k) plans specifically designed to maximize the benefits Congress intended, including participant loans, Roth contributions, checkbook control, and the ability to invest in virtually any asset permitted under the Internal Revenue Code. If you want to understand whether a Solo 401(k) loan could work for your situation, our team of in-house tax specialists is available for a free consultation.
The smartest way to regain control of your finances may not be borrowing from someone else at all. It may be borrowing from yourself.

How Do You Title Real Estate in a Self-Directed IRA?
Real estate has long been one of the most popular alternative investments held inside retirement accounts. Many investors understand the benefits of owning rental properties, commercial buildings, raw land, or private real estate investments, but few realize that retirement funds can often be used to acquire these assets while preserving the tax advantages of an IRA.
A Self-Directed IRA allows retirement investors to move beyond traditional Wall Street investments and invest in assets they know and understand. While most brokerage firms limit IRA investments to stocks, bonds, mutual funds, and ETFs, the Internal Revenue Code generally permits IRAs to invest in almost any asset class except life insurance and collectibles. As a result, real estate has become one of the most common investments held within self-directed retirement accounts.
However, not all Self-Directed IRAs operate the same way. Investors generally have two options when purchasing real estate through a retirement account: a traditional custodian-administered Self-Directed IRA, often referred to as a full-service SDIRA, or a Self-Directed IRA LLC structure, commonly known as a checkbook control IRA. While both structures allow investors to purchase real estate using retirement funds, the way they operate, the level of investor control, and the administrative requirements are significantly different. Understanding these differences is critical because the right structure can make the process of acquiring and managing real estate substantially easier and more efficient.
Key Takeaways
- How real estate is titled in a Self-Directed IRA depends entirely on which structure is used. With a full-service custodian-controlled IRA, title is held in the custodian's name for the benefit of the IRA owner. With a Self-Directed IRA LLC, title is held in the name of the LLC.
- A Self-Directed IRA is not a separate legal term found in the Internal Revenue Code. It is simply an IRA administered by a custodian willing to permit investments beyond traditional securities, following the same tax rules as any other IRA.
- The full-service Self-Directed IRA is best suited for investors making passive investments that do not require frequent transactions, such as raw land or private fund investments.
- The Self-Directed IRA LLC, or checkbook control IRA, is better suited for active real estate investors who need the ability to move quickly, sign contracts directly, pay expenses without custodian delays, and manage multiple properties efficiently.
- Neither structure is inherently better. The right choice depends on how actively the investor intends to participate in real estate investing.
What Is a Self-Directed IRA?
Contrary to popular belief, a Self-Directed IRA is not a separate type of retirement account recognized under the Internal Revenue Code. It is simply an IRA administered by a custodian willing to permit investments beyond traditional securities.
From a tax perspective, a Self-Directed IRA follows the same rules as any other IRA. A Traditional Self-Directed IRA generally offers tax-deferred growth, meaning investments can grow without current taxation until distributions are taken. A Roth Self-Directed IRA is funded with after-tax dollars, but qualified distributions are completely tax-free. The primary distinction between a conventional IRA and a Self-Directed IRA is investment flexibility. Instead of being limited to publicly traded securities, a Self-Directed IRA can invest in real estate, private placements, private lending transactions, cryptocurrency, precious metals, tax liens, and many other alternative assets.
For investors who have expertise in real estate, this flexibility can be particularly attractive. Rather than investing retirement funds in assets they may not fully understand, they can use those funds to acquire properties, generate rental income, and potentially build long-term wealth within a tax-advantaged environment.
The Two Types of Self-Directed IRAs for Real Estate
Although investors often refer to all Self-Directed IRAs as if they operate identically, there are two primary structures used for real estate investing. The first is a traditional full-service Self-Directed IRA where the custodian remains actively involved in all investment transactions. The second utilizes a limited liability company owned by the IRA, giving the investor direct control through checkbook control. Both structures are fully permissible under IRS rules but differ considerably in terms of administration, flexibility, transaction speed, and cost.
Full-Service Self-Directed IRA
Under a full-service Self-Directed IRA structure, the custodian remains directly involved in every aspect of the investment transaction. The IRA owns the real estate directly, and the custodian serves as the record owner on behalf of the IRA.
When an investor identifies a property for purchase, they submit the contract and supporting documentation to the custodian. The custodian reviews the paperwork, processes the investment instructions, and sends the funds necessary to complete the acquisition. After the purchase is completed, all rental income flows back into the IRA account, and all expenses related to the property are paid directly by the IRA through the custodian.
For example, suppose John has $250,000 in his Self-Directed IRA and wishes to purchase a rental property for $200,000. John negotiates the purchase terms and submits the contract to his custodian. The custodian wires the funds from the IRA to the closing agent. Once the property is acquired, rental income is deposited into the IRA account, and expenses such as property taxes, insurance premiums, or repair costs are paid from IRA funds through the custodian.
The primary advantage of this structure is simplicity. Because the custodian remains involved in every transaction, investors have fewer administrative responsibilities. There is no need to establish a separate LLC, maintain corporate records, or manage a dedicated bank account. Startup costs are also generally lower because there are no LLC formation or annual maintenance expenses.
The primary disadvantage is that every transaction requires custodian involvement. Investors cannot write a check to a contractor, pay an earnest money deposit, or wire funds directly. They must submit instructions to the custodian and wait for processing. While this helps maintain compliance, it can create delays when a real estate transaction requires immediate action.
This structure is most appropriate for investors making passive investments that do not involve a high volume of transactions, such as raw land or private fund investments.
Self-Directed IRA LLC (Checkbook Control)
The Self-Directed IRA LLC structure is commonly referred to as a checkbook control IRA. Under this arrangement, the IRA forms and owns 100% of a limited liability company. The IRA owner typically serves as the manager of the LLC, while the IRA itself serves as the sole member and owner.
After the LLC is established, the IRA transfers its investment funds into the LLC's bank account. Because the investor serves as manager, they gain direct authority to control the LLC's assets and execute investment transactions without requiring custodian approval for each activity. In practical terms, this means the investor can write checks, send wires, sign purchase contracts, and manage investments directly from the LLC bank account.
For example, if John's IRA owns Sunshine LLC and John serves as manager, John can identify a property, negotiate the purchase terms, sign the contract as manager, and send funds directly from the LLC bank account to complete the acquisition without any custodian involvement.
This structure has become the most popular option for active real estate investors for three primary reasons.
Speed and control. Investors can react quickly to investment opportunities without waiting for custodian approval. This is especially valuable when purchasing distressed properties, participating in auctions, making private loans, or investing in competitive markets where timing is critical.
Limited liability protection. LLCs are recognized as separate legal entities, meaning the IRA owner's personal assets and the IRA itself are protected from the debts, obligations, and liabilities of the LLC. For investors owning multiple properties, this separation is particularly important.
Privacy. When an LLC makes an investment, the investment is recorded in the name of the LLC rather than the IRA custodian or the individual investor. Depending on the state in which the LLC is established, identifying the owner can be difficult. States such as Delaware and Wyoming offer particularly strong privacy protections.
The tradeoff is greater responsibility. Investors must maintain the LLC properly, keep accurate records, ensure all transactions comply with IRS prohibited transaction rules, and avoid commingling personal and retirement assets.
Book a free call with a self-directed retirement specialist
- Review your self-directed retirement options
- Learn about investing in alternative assets
- Get all of your questions answered
How Real Estate Is Titled in Each Structure
One of the most misunderstood aspects of Self-Directed IRA real estate investing is how title to the property is held. Getting this right is essential because the property must be owned by the retirement account, not the individual investor.
Full-service Self-Directed IRA titling. When the IRA owns the property directly through the custodian, title typically appears as:
IRA Financial Trust Company CFBO John Doe IRA
The custodian's name appears on title because the custodian is serving as the legal holder of the asset on behalf of the IRA. The investor's personal name should never appear as the property owner.
For example, if Lisa Smith is purchasing a property at 1234 Apple Street using her Roth IRA, she provides IRA Financial Trust, as custodian, the requisite closing documents for signature. Title to the property would be recorded as:
IRA Financial Trust Company FBO Lisa Smith Roth IRA
All income and gains from the property flow back to Lisa's Roth IRA tax-free. All expenses must be paid by the IRA custodian on behalf of the IRA since the IRA owns the asset, not Lisa personally.
Self-Directed IRA LLC titling. When a checkbook control structure is used, the deed is recorded simply in the name of the LLC. Suppose Lisa's IRA establishes an LLC named 1234 Apple Street LLC to purchase that same property. Title to the property would be recorded as:
1234 Apple Street LLC
The IRA owns the LLC, and the LLC owns the property. Lisa, as manager of the LLC, can sign leases, hire contractors, pay expenses, collect rents, and manage the property without waiting for custodian approval. Because the LLC has only one member, it is generally treated as a disregarded entity for federal income tax purposes, meaning no separate federal income tax return is required for the LLC.
How to Buy Real Estate Through a Self-Directed IRA
Regardless of which structure is used, the investment process follows the same general steps. The first step is funding the Self-Directed IRA through a transfer, rollover, or contribution. Once funded, the investor identifies a property and performs the necessary due diligence.
With a full-service Self-Directed IRA, the custodian executes the purchase on behalf of the IRA. With a checkbook control structure, the LLC completes the purchase directly. The most important concept to remember is that the retirement account, not the individual investor, is making the investment. All purchase funds must come from the IRA or IRA-owned LLC, and all income and expenses must flow back through that same structure.
Which Structure Is Right for You?
Both the full-service Self-Directed IRA and the Self-Directed IRA LLC are effective tools for investors seeking to use retirement funds to acquire real estate. Neither is inherently better than the other.
For investors seeking simplicity, lower startup costs, and greater custodian involvement, the traditional full-service Self-Directed IRA is often the right choice. For investors seeking maximum flexibility, enhanced privacy, limited liability protection, and direct control over their investments, the IRA LLC structure generally provides significant advantages.
The decision ultimately comes down to how actively the investor intends to participate in real estate investing. Regardless of the structure selected, both approaches allow retirement investors to diversify beyond traditional securities and use tax-advantaged retirement funds to build long-term wealth through real estate ownership.
IRA Financial vs Alto IRA
When you want to invest your retirement funds in alternative assets, such as real estate, private equity, or cryptocurrency, Self-Directed IRAs (SDIRAs) give you that flexibility. Two notable players are IRA Financial and Alto IRA. While both facilitate alternative investing, they have different philosophies, pricing models, strengths, and trade-offs.
Below is a side-by-side comparison across four critical areas: fees and pricing, product options, technology, and reputation.
Pricing & Fees: Transparent, Flat, and Investor-Friendly
Fees often determine whether a provider is advantageous for your strategy, especially when you have many transactions or your account grows. Alto IRA charges a quarterly Account Fee based on Total Invested Capital, plus separate service fees, while IRA Financial uses a flat annual fee.
IRA Financial | Alto IRA | |
Setup Fee | $0 | $0 |
Annual Fee | $495 | $400 |
Asset Value Fee | $0 | $0 |
Investment Fee | $0 | $300 |
Roth Conversion Fee | $0 | $50 |
1 Year Total Cost | $495 | $750 |
Pricing pulled from company website, as of the article publish date, based on 4 investments with a $200K total balance.
IRA Financial:
- IRA Financial offers flat, transparent annual fees starting at $495/year for a Self-Directed IRA, with other plans available starting as low as $100 annually.
- No asset-based fees, no transaction fees, and no hidden charges; what you see is what you pay.
- Their IRAfi Crypto platform offers low trading fees for buying, selling, and trading crypto through the integrated app.
Alto IRA:
- Quarterly Account Fee based on Total Invested Capital: $0 under $0.01, $37.50/quarter under $30,000, $100/quarter at $30,000 and above
- Investment processing fee varies by source: $0 through Alto Marketplace, $10 through an Integrated Partner, $75 for a Private investment
- $50 Roth conversion fee, $50 account closure fee
Summary
IRA Financial's flat-fee structure offers cost predictability, ideal for investors managing real estate, LLCs, or multiple deals. Alto IRA's costs vary depending on how each investment is sourced, Marketplace deals carry no processing fee, while private investments add $75 each, so the total cost depends heavily on where your deals come from.
Winner: IRA Financial.
A single flat annual fee that doesn't change based on how or where you source each investment.
Investment Flexibility & Product Options
When choosing a Self-Directed IRA, flexibility is everything. Both IRA Financial and Alto IRA give investors access to alternative assets, but the range and control differ.
IRA Financial | Alto IRA | |
Account Type | ||
Self-Directed IRA | ||
Solo 401(k) | ||
HSA | ||
Checkbook Control | ||
ROBS Structure | ||
Platform & Investments | ||
Crypto Platform | ||
Stock Trading | ||
Compliance & Protection | ||
In-House Compliance & Tax Services | ||
IRS Audit Protection |
IRA Financial:
- Offers all the traditional SDIRA investments, including real estate, private lending, startups, precious metals, as well as direct crypto investing.
- Integrated platform for crypto, checkbook control, real estate, and more under one roof.
- Stock, ETF, bond, and options trading powered by Interactive Brokers - available as a $100/year add-on, fully integrated inside your IRA Financial account.
- Advanced structures like Solo 401(k) plans, SEP & SIMPLE IRAs, HSA & Coverdell accounts, and ROBS structures for business funding.
- IRA Compliance Shield ($299/year): in-house audit protection, tax consultation, deal reviews, prohibited transaction pre-clearance, and UBIT/UDFI modeling.
Alto IRA:
- Offers access to private equity, startups, and crypto through its Marketplace and Integrated Partners
- Checkbook IRA LLC isn't part of Alto's offering; most investments run directly through Alto's platform without one
- Account types limited to Traditional, Roth, and SEP IRAs, no SIMPLE, HSA, Coverdell, or ROBS
Summary
IRA Financial provides full control and unlimited investment choices through its LLC or trust structure, making it ideal for hands-on investors. Alto IRA streamlines access to curated investments through its Marketplace and partners, but doesn't offer the same built-in checkbook control or account variety.
Winner: IRA Financial
Broader account types and built-in checkbook control for investors who want full control of their IRA assets.
Technology: Built for the Modern Investor
Technology defines how easily investors can manage their self-directed accounts. Both IRA Financial and Alto IRA use digital tools to simplify alternative investing, but their approaches reflect different priorities.
IRA Financial:
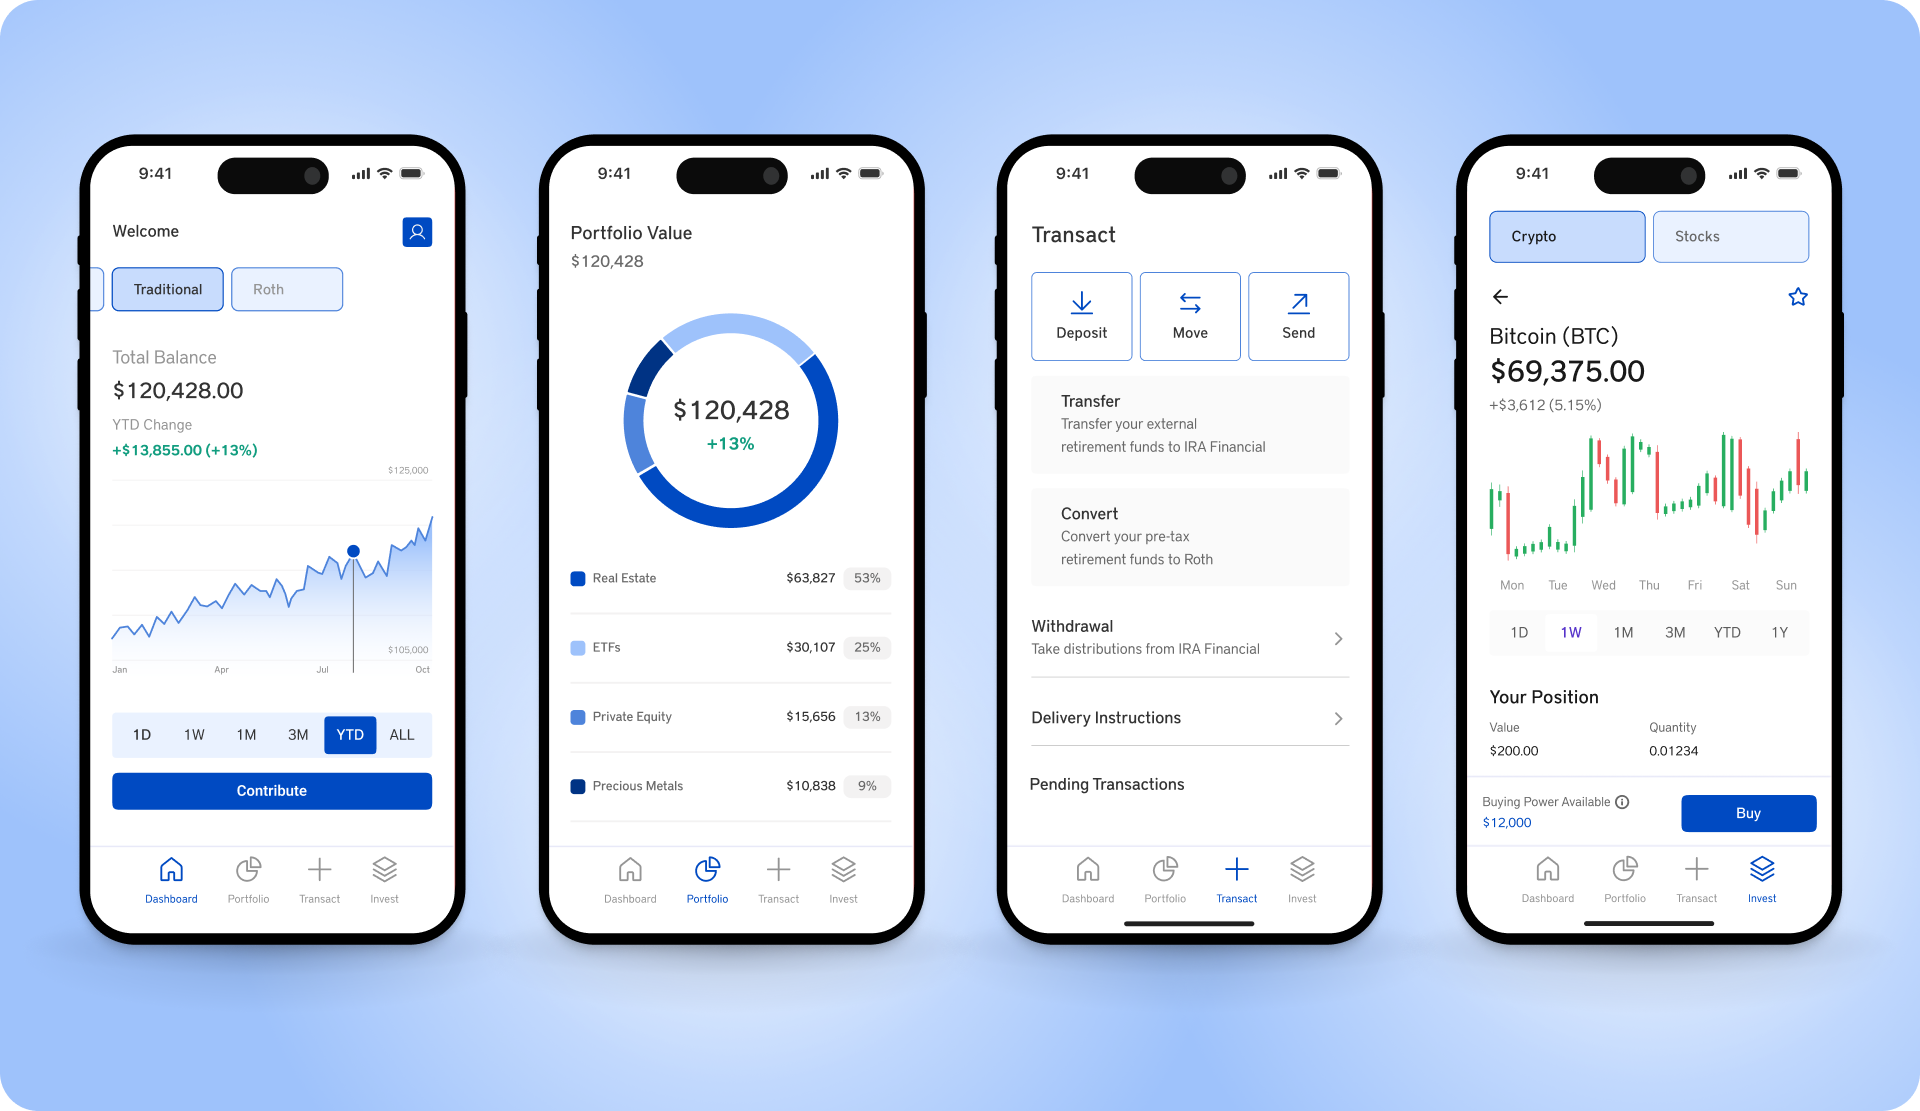
- Newly-updated mobile app and account dashboard with clean UI/UX and modern functionality.
- Offers a fully digital on-boarding experience, automated compliance, and secure document storage.
- In-house crypto trading, real-time dashboards, and checkbook control in a single portal.
Alto IRA:
- Clean, user-friendly online platform with guided investment workflows
- Mobile app available on iOS and Android, though Android users report more reliability issues than iOS users
- Focused on private market investments such as private equity, private credit, real estate, and infrastructure
Summary
IRA Financial leads in automation and consistency, offering crypto trading, checkbook control, and compliance tools all within one integrated platform. Alto IRA's interface is modern and intuitive, but its product scope is narrower, focused on private market investments through its Marketplace and partners rather than an all-in-one platform.
Winner: IRA Financial.
A single integrated platform where crypto trading, checkbook control, and compliance all live within one account experience.
Reputation & Customer Reviews
Reputation can signal reliability, especially when dealing with retirement assets. Alto IRA has historically held a strong reputation, but a recent event has significantly changed its standing.
IRA Financial | Alto IRA | |
Trustpilot | 4.8 / 5 | 2.9 / 5 |
4.3 / 5 | 2.7 / 5 |
IRA Financial:
- Strong reputation for fast account setup, responsive customer service, and straightforward pricing.
- Over 3,000 5-star reviews across Google, Trustpilot, and other platforms.
- Founded by tax attorney Adam Bergman, who educates investors via weekly videos, podcasts, and blog articles.
Alto IRA:
- Founded in 2018
- Holds a 2.9/5 rating on Trustpilot across more than 1,300 reviews
- Offers customer support by phone and email during business hours
Summary
Both platforms maintain visible customer feedback across major review sites, but IRA Financial's ratings remain consistently strong across a much larger volume of reviews.
Winner: IRA Financial.
A consistently strong reputation without a recent, disruptive platform transition affecting existing account holders.
The Bottom Line: Why IRA Financial Is the Smarter Choice
Both IRA Financial and Alto IRA have made alternative investing more accessible, but they serve different investor types. Alto IRA's low entry cost and guided marketplace still appeal to newer or smaller investors, but its cost structure varies by investment source, and its recent crypto custody transition has created real disruption for existing crypto account holders.
For investors who want predictable flat-fee pricing, full account flexibility, and a platform not currently navigating a disruptive custody change, IRA Financial offers more.
Book a free call with a self-directed retirement specialist
- Review your self-directed retirement options
- Learn about investing in alternative assets
- Get all of your questions answered
How to Close a Real Estate IRA Purchase: A Step-by-Step Compliance Checklist
A Real Estate IRA closing follows standard real estate procedures, but ownership, funding flow, and signatures must reflect the IRA, not you personally.
Most closing problems come from using personal defaults where IRA-specific rules apply.
Key Takeaways:
- How a Real Estate IRA closing differs from a personal purchase
- The correct title vesting language and why it matters
- How to handle earnest money, escrow, and closing costs from the IRA
- Insurance requirements that are frequently overlooked
- A closing checklist you can use immediately
How a Real Estate IRA Closing Differs From a Personal Closing
A Real Estate IRA purchase uses the same infrastructure as any other closing: agents, escrow, title, and lenders where applicable. What changes is how ownership and control are structured throughout the transaction.
Ownership sits with the IRA, not with you. That means your role at closing is limited to signing as an authorized representative rather than as the buyer. That distinction affects how contracts are written, where funds originate, who signs documents, and how insurance is issued. Every item on this checklist ties back to that structure.
Step 1: Confirm the Correct Title Vesting Language
Title must reflect IRA ownership exactly as required by your custodian. The standard vesting format is:
[Custodian Name] FBO [Your Name] IRA #[Account Number]
Common title errors to avoid include listing your personal name only, using an LLC or trust not owned by the IRA, and omitting "FBO" or the IRA account number. Incorrect vesting creates correction work and can result in invalid ownership records that complicate future transactions.
Step 2: Structure the Purchase Contract Correctly
The purchase agreement should identify the IRA as the buyer, not you personally. The buyer name in the contract must match the IRA vesting language exactly, the earnest money clause must specify IRA funds, and the signature block must reflect your role as an authorized signer rather than the owner.
Signature format: [Your Name], Authorized Signer for [Custodian Name] FBO [Your Name] IRA
Contracts signed personally without reference to the IRA create assignment issues later that can be difficult and costly to unwind.
Step 3: Handle Earnest Money From the IRA
Earnest money must originate from the IRA account. Acceptable methods include a custodian-issued check, a custodian wire, or a Checkbook IRA LLC account if the structure is set up correctly.
What is not acceptable: a personal check, business account funds, or any form of reimbursement after closing. Using personal funds, even temporarily, creates prohibited transaction risk that can jeopardize the entire account. This is one of the most common mistakes I see in Real Estate IRA transactions, and it is entirely avoidable with early planning.
Step 4: Coordinate Escrow With the IRA Custodian
Escrow needs to be set up with the IRA as the buyer from the start. That means the IRA must be listed as the buyer on escrow instructions, the custodian contact must be included early in the process, and the funding timeline must be aligned with custodian processing times.
The most common friction points are short escrow timelines, last-minute document requests, and wiring instructions issued too late for the custodian to process. Getting escrow and the custodian aligned early in the transaction eliminates most of these delays.
Step 5: Confirm All Funds and Closing Costs Flow From the IRA
All purchase-related costs must be paid by the IRA. That includes the purchase price, closing costs, title fees, and recording fees.
Costs that cannot be paid personally include repairs prior to purchase, inspection fees charged to the buyer, and any post-closing expenses. Mixing personal and IRA funds, even for minor costs, violates the required separation under IRA rules and can trigger a prohibited transaction.
Step 6: Issue Insurance in the IRA's Name
Insurance is one of the most frequently overlooked compliance points in a Real Estate IRA closing. The insured party on the policy must match the IRA title, no personal name should be listed as the owner, and the loss payee must be structured per custodian requirements.
Common mistakes include policies issued in the personal name, the IRA listed only as an additional interest rather than the insured owner, and incorrect mailing or billing setup. Insurance errors delay funding because custodians will not release closing funds until the policy correctly names the IRA as the insured owner. That gap can leave the property temporarily uncovered while corrections are made.
Step 7: Verify Who Signs What at Closing
| Document | Signer |
|---|---|
| Purchase agreement | Authorized signer |
| Escrow instructions | Authorized signer |
| Loan documents (if allowed) | IRA custodian |
| Deed | Seller only |
Signature authority rests with you as the IRA's authorized representative. Ownership remains with the IRA itself. Those are two different things and keeping them straight at closing is essential.
Step 8: Post-Closing Checks to Confirm Compliance
After recording, confirm that the deed is recorded in the correct IRA name, the insurance policy is active and correctly issued, the custodian has received the final settlement statement, and rent or income instructions direct all payments to the IRA account rather than to you personally.
Book a free call with a self-directed retirement specialist
- Review your self-directed retirement options
- Learn about investing in alternative assets
- Get all of your questions answered
Common Real Estate IRA Closing Mistakes
Nearly all closing mistakes come from handling the deal like a personal purchase rather than an IRA-owned transaction. The issues that appear most often are:
- Personal earnest money used to speed up closing
- Title issued in personal name "temporarily" with plans to correct later
- Insurance issued incorrectly in the owner's personal name
- Escrow unaware that the buyer is an IRA
- Incorrect signature blocks that reference you as the buyer rather than an authorized signer
Temporary workarounds that seem harmless in the moment can create prohibited transaction exposure that is far more difficult to resolve after the fact.
Read More: The Prohibited Transaction Minefield: Rules to Keep Your Real Estate IRA Compliant
How to Run a Real Estate IRA Closing in 2026
The single most important thing you can do is treat the custodian as part of the transaction team from the beginning, not as a back-office function you loop in at the end.
Send the contract draft to the custodian before signing. Confirm vesting language in writing before going under contract. Fund earnest money early. Loop escrow and insurance together so both are aligned on the IRA structure. Recheck title before recording to confirm nothing slipped through as personal ownership.
A Closing Checklist You Can Use Immediately
Before signing final documents, confirm each of the following:
- Buyer name on all documents matches IRA vesting language exactly
- All funds, including earnest money and closing costs, originate from the IRA
- Insurance policy names the IRA as the insured owner
- All signatures reflect authorized signer authority, not personal ownership
- Custodian has received and confirmed final documents
Real estate is one of the most powerful assets you can hold inside a Self-Directed IRA. It can generate tax-free rental income, appreciate without annual capital gains consequences, and eventually be distributed as part of a broader retirement strategy. But that potential only holds if the transaction is structured correctly from the first contract to the final recording. The checklist in this guide is not a formality. It is the difference between a clean transaction and one that requires corrections, penalties, or worse.
The Self-Employed Tax-Free Empire: How to Bundle Your Way to Tax-Free Millions
The tax code is often portrayed as the enemy of the self-employed. In reality, it is written in their favor. W-2 employees are largely limited to whatever retirement plan their employer offers. Self-employed individuals, freelancers, consultants, and 1099 contractors have access to a suite of retirement tools that can shelter far more income, offer far more investment flexibility, and generate far more tax-free wealth than anything available through a corporate plan.
The strategy is straightforward: bundle a Solo 401(k), a Self-Directed Roth IRA, a Health Savings Account, and a Coverdell ESA. Each account solves a different tax problem. Together, they create a structure where a significant portion of your business income can grow and ultimately be distributed without ever being taxed again.
Key Takeaways:
- Why the Solo 401(k) is the most powerful retirement account available to the self-employed
- How the Mega Backdoor Roth moves up to $72,000 annually into a tax-free environment
- Why the Self-Directed Roth IRA is the long-term wealth multiplier
- How the HSA functions as a stealth retirement account with triple tax advantages
- How the Coverdell ESA extends tax-free growth to education funding
The Solo 401(k): Your Primary Engine for Tax Reduction
The Solo 401(k) is the cornerstone of any self-employed retirement strategy. If you have a business with no full-time employees other than a spouse, this plan allows you to contribute in two capacities simultaneously, as both the employee and the employer, creating a level of annual tax sheltering that no other account type can match.
2026 contribution limits
| Age | Total Annual Limit |
|---|---|
| Under 50 | $72,000 |
| Age 50 to 59 | $80,000 (includes $8,000 catch-up) |
| Age 60 to 63 | $83,250 (SECURE 2.0 enhanced catch-up of $11,250) |
The two contribution categories work like this:
- Employee deferrals: Up to $24,500, which can go into a Traditional pre-tax or Roth after-tax account
- Employer contributions: Your business can contribute up to 25% of W-2 compensation or approximately 20% of net self-employment income for sole proprietors and single-member LLCs
For a consultant earning $250,000 in net self-employment income, this combination can shelter over $70,000 from federal taxation in a single year. A SEP IRA on the same income would allow only around $45,000. The difference is the employee deferral, which exists only in a 401(k) structure.
IRA Financial's Solo 401(k) supports both traditional asset classes and alternative investments including private equity, crypto, precious metals, and private lending, all under one flat annual fee with no asset-based charges.
The Participant Loan: Tax-Free Access to Your Capital
One of the most underused features of the Solo 401(k) is the plan loan. You can borrow up to 50% of your account value or $50,000, whichever is less, without triggering taxes or penalties. The loan must be repaid within five years with at least quarterly payments, and the interest rate is typically Prime plus 1%.
What makes this compelling for self-employed investors is that the interest you pay goes directly back into your own account rather than to a bank. In a year where cash flow is tight or a business opportunity requires quick capital, the Solo 401(k) loan provides liquidity without the tax consequences of a withdrawal.
Checkbook Control: Moving at the Speed of Business
IRA Financial's Solo 401(k) plans include checkbook control, meaning your plan trust maintains a dedicated bank account that you control as trustee. When an investment opportunity appears, whether a private placement, a startup equity position, or a crypto purchase, you write a check or wire funds directly from the account. No custodian approval, no processing delay.
For self-employed investors who are already accustomed to making fast business decisions, this level of control over retirement capital feels natural. For those accustomed to waiting days for a brokerage to process a trade, it is a significant shift in how quickly capital can be deployed.
If real estate is part of your investment strategy, IRA Financial's Solo 401(k) also includes a specific tax advantage over IRAs on leveraged property. For a detailed breakdown of that benefit and the full real estate bundled strategy, see our guide to The Real Estate Investor's Tax-Free Retirement Bundled Solution.
The Mega Backdoor Roth: Moving $72,000 Into a Tax-Free Environment
For self-employed investors who want to maximize tax-free accumulation, the Mega Backdoor Roth is the most powerful strategy available inside a Solo 401(k).
Standard Roth deferrals are capped at $24,500. The Mega Backdoor strategy allows you to make after-tax contributions above that cap, up to the $72,000 combined limit, and immediately convert those after-tax funds into Roth. The result is that a self-employed investor can move up to $72,000 per year into a tax-free Roth environment regardless of income level, something a standard Roth IRA cannot accomplish due to income limits and contribution caps.
The plan document must explicitly allow after-tax contributions and in-plan Roth conversions for this strategy to work. IRA Financial's Solo 401(k) plan documents include both provisions by default.
Book a free call with a self-directed retirement specialist
- Review your self-directed retirement options
- Learn about investing in alternative assets
- Get all of your questions answered
The Self-Directed Roth IRA: The Long-Term Wealth Multiplier
Even with a Solo 401(k), a Self-Directed Roth IRA plays a distinct and important role in the bundled strategy. The Solo 401(k) is the primary vehicle for sheltering current-year income. The Roth IRA is the long-term vehicle for compounding wealth that will never be taxed again.
2026 limits and income rules
- Contribution limit: $7,500, or $8,600 for those age 50 and older
- Phase-out for married filing jointly: $242,000 to $252,000
- Phase-out for single filers: $153,000 to $168,000
For investors above the income limits, the Backdoor Roth IRA remains fully legal in 2026. A non-deductible contribution to a Traditional IRA is immediately converted to a Roth, bypassing the income cap entirely. IRA Financial's tax team works through the pro-rata rules with clients to ensure the conversion is handled correctly.
Why hold both a Solo 401(k) and a Roth IRA?
The two accounts serve different purposes and have different distribution rules. The Solo 401(k) generates the largest current-year deduction. The Roth IRA builds wealth that is never subject to Required Minimum Distributions, can be passed to heirs tax-free, and can have contributions withdrawn at any time without penalty since they were already taxed.
Holding both means you can direct high-growth investments with long time horizons into the Roth and use the Solo 401(k) for current-year tax reduction. That separation produces better outcomes than relying on either account alone.
The HSA: Triple Tax Advantages Most Investors Ignore
The Health Savings Account is the most overlooked account in the self-employed toolkit. Used correctly, it functions as a stealth retirement account with a tax structure that no other account matches.
Eligibility
To contribute to an HSA you must be enrolled in a High-Deductible Health Plan (HDHP), not enrolled in Medicare, and not claimed as a dependent. For 2026, the minimum HDHP deductible is $1,700 for individual coverage and $3,400 for family coverage.
2026 contribution limits
- Individual coverage: $4,400
- Family coverage: $8,750
- Catch-up (age 55 and older): an additional $1,000
The triple tax advantage
- Contributions reduce your taxable income in the year they are made
- Investments grow tax-free inside the account
- Withdrawals for qualified medical expenses are completely tax-free
No other account in the tax code offers all three simultaneously. A Traditional IRA gives you one and two. A Roth IRA gives you two and three. The HSA gives you all three at once.
Read more: How a Self-Directed HSA Can Double as a Stealth Retirement Account
The delayed reimbursement strategy
The most powerful way to use an HSA as a retirement vehicle is to pay medical expenses out of pocket, save the receipts, invest the HSA balance for long-term growth, and reimburse yourself years or even decades later. There is no IRS deadline on reimbursement as long as the expense occurred after the account was opened and you have documentation. That means your HSA can compound tax-free for years before you ever touch it.
IRA Financial's HSA platform allows the account to hold alternative investments alongside traditional securities, and includes a dedicated debit card for immediate medical expense payments. That combination, investment flexibility plus spending convenience, is not available from standard HSA providers.
The Coverdell ESA: Extending Tax-Free Growth to Education
The Coverdell Education Savings Account rounds out the bundled strategy by extending tax-free compounding to education funding. Contributions of up to $2,000 per year per child are made with after-tax dollars, but all earnings and withdrawals are tax-free when used for qualified education expenses.
The Coverdell's advantage over a 529 plan is its flexibility. Funds can be used for K-12 expenses including private school tuition, tutoring, books, and educational technology, not just college costs. For self-employed investors with school-age children paying private school tuition, this distinction matters.
At IRA Financial, the Coverdell is set up with full checkbook control, allowing it to participate in investment deals alongside your other accounts. A Coverdell can hold a small equity position in the same private deal as your Solo 401(k), with the gains flowing back into the education account tax-free.
If the beneficiary does not use the funds by age 30, the balance can be rolled to another eligible family member under 30, keeping the tax-free growth within the family rather than triggering a penalty.
Read more: The “Triple-Threat” Education Strategy: 529, Self-Directed Coverdell, and the Trump Account
Final Thoughts
The bundled strategy works because the tax problem facing self-employed investors has multiple dimensions. Current-year income needs to be sheltered. Long-term gains need to grow without tax drag. Healthcare costs need to be managed efficiently. And education funding should not come from after-tax dollars if it does not have to.
The Solo 401(k), Self-Directed Roth IRA, HSA, and Coverdell ESA each address one of those dimensions. Together they create a structure where the self-employed investor keeps a significantly larger portion of what they earn, compounds it without interruption, and eventually accesses it in a way that the IRS has already agreed is tax-free.
The tax code was written with these vehicles in mind. Using them is not a workaround. It is the system working exactly as intended.
IRA Financial vs Columbia Private Trust
For investors looking to diversify their retirement portfolios with alternative assets, such as real estate, private equity, or cryptocurrency, Self-Directed IRAs (SDIRAs) are a powerful tool. Two well-known providers in this space are IRA Financial and Columbia Private Trust (formerly known as PENSCO and Pacific Premier Trust). While both allow you to step outside traditional Wall Street assets, they differ in important ways, especially around fees, investment flexibility, technology, and client experience.
This comparison walks through pricing, investment flexibility, technology, and reputation.
Pricing & Fees: Transparent, Flat, and Investor-Friendly
Cost is one of the most important, and often confusing, factors when selecting an SDIRA provider. IRA Financial offers a flat-fee model, while Columbia Private Trust uses a traditional custodial pricing structure based on total asset value plus per-transaction charges.
IRA Financial | Columbia Private Trust | |
Setup Fee | $0 | $0 |
Annual Fee | $495 | $750 |
Asset Value Fee | $0 | $0 |
Investment Fee | $0 | $700 |
Roth Conversion Fee | $0 | $150 |
1 Year Total Cost | $495 | $1,450 |
5 Year Total Cost | $2,475 | $4,450 |
Pricing pulled from company website, as of the article publish date, based on 4 investments with a $200K total balance.
IRA Financial:
- IRA Financial offers flat, transparent annual fees starting at $495/year for a Self-Directed IRA, with other plans available starting as low as $100 annually.
- No asset-based fees, no transaction fees, and no hidden charges; what you see is what you pay.
- Their IRAfi Crypto platform offers low trading fees for buying, selling, and trading crypto through the integrated app.
Columbia Private Trust:
- No separate account setup fee, but a $175 Asset Processing Fee applies to every purchase, liquidation, exchange, or incoming transfer of an asset
- Annual Administration Fee is based on Total Asset Value: 0.30% on the first $1,000,000, with a $750 minimum
- $150 fee to convert or recharacterize a Roth IRA
- $75/quarter Cash Balance Requirement Fee, waived with a $1,000+ average cash balance ($5,000+ for real estate accounts)
Summary
Columbia Private Trust's asset-value-based Administration Fee stays close to its $750 minimum for smaller accounts, but the $175 Asset Processing Fee on every transaction adds up quickly for investors holding multiple assets. For an investor holding 4 assets on a $200,000 balance, Columbia Private Trust costs nearly 3 times what IRA Financial charges over 5 years.
Winner: IRA Financial.
A single flat annual fee with no per-transaction charges, versus a fee structure that combines an asset-value-based annual fee with a separate charge for every purchase or transfer.
Investment Flexibility & Product Options
The type of assets you can hold, and how you can purchase them, differs between providers. Both support a wide range of alternatives, but the level of investor control is where they diverge.
IRA Financial | Columbia Private Trust | |
Account Type | ||
Self-Directed IRA | ||
Solo 401(k) | ||
HSA | ||
Checkbook Control | ||
ROBS Structure | ||
Platform & Investments | ||
Crypto Platform | ||
Stock Trading | ||
Compliance & Protection | ||
In-House Compliance & Tax Services | ||
IRS Audit Protection |
IRA Financial:
- Offers all the traditional SDIRA investments, including real estate, private lending, startups, precious metals, as well as direct crypto investing.
- Integrated platform for crypto, checkbook control, real estate, and more under one roof.
- Stock, ETF, bond, and options trading powered by Interactive Brokers - available as a $100/year add-on, fully integrated inside your IRA Financial account.
- Advanced structures like Solo 401(k) plans, SEP & SIMPLE IRAs, HSA & Coverdell accounts, and ROBS structures for business funding.
- IRA Compliance Shield ($299/year): in-house audit protection, tax consultation, deal reviews, prohibited transaction pre-clearance, and UBIT/UDFI modeling.
Columbia Private Trust:
- Direct custodian model with no checkbook control, every asset purchase is reviewed and approved before it's processed
- Supported assets: real estate, private equity, LLCs, LPs, notes, and precious metals
- Crypto available only through select partner platforms, not directly inside the account
- Account types limited to Roth, Traditional, SEP, SIMPLE, and Inherited IRAs, no Solo 401(k), HSA, Coverdell, or ROBS
Summary
IRA Financial offers more flexibility with checkbook control, direct crypto investing, and advanced retirement plan structures. Columbia Private Trust takes a traditional custodian role, better suited to investors who prefer oversight and compliance handled for them, but who don't need business-funding structures or same-day investment control.
Winner: IRA Financial
Checkbook control, direct crypto access, and account types like Solo 401(k) and ROBS that Columbia Private Trust does not offer.
Technology: Built for the Modern Investor
Both IRA Financial and Columbia Private Trust offer web-based account management with a companion mobile app, so the platforms themselves are fairly comparable on the surface. Where they differ is what happens once you want to act, IRA Financial lets you execute investments directly, while Columbia Private Trust requires custodian review and approval before a purchase, sale, or transfer is processed.
IRA Financial:
- Newly-updated mobile app and account dashboard with clean UI/UX and modern functionality.
- Offers a fully digital on-boarding experience, automated compliance, and secure document storage.
- In-house crypto trading, real-time dashboards, and checkbook control in a single portal.
Columbia Private Trust:
- Web-based client portal (Pacific Premier Wealth Online) plus a companion mobile app for viewing balances, transactions, and account dashboards
- Every asset purchase, sale, or transfer goes through a custodian review and approval process before it's processed
- The app itself requires an existing web portal login to use
Summary
Both providers offer a modern-enough web and mobile experience for checking balances and monitoring accounts. The real difference is speed to execution: IRA Financial lets investors act the moment they find an opportunity, while Columbia Private Trust's review process means transactions take longer to complete, regardless of which device you're using to request them.
Winner: IRA Financial.
Investments execute directly and immediately, without waiting on custodian review and approval for every transaction.
Reputation & Customer Reviews: Trusted by Thousands
Track record and trustworthiness are critical when entrusting a custodian with your retirement funds. IRA Financial and Columbia Private Trust both have reputations built over time, though they appeal to different investor profiles.
IRA Financial | Columbia Private Trust | |
Trustpilot | 4.8 / 5 | N/A |
4.3 / 5 | 4.7 / 5 |
IRA Financial:
- Strong reputation for fast account setup, responsive customer service, and straightforward pricing.
- Over 3,000 5-star reviews across Google, Trustpilot, and other platforms.
- Founded by tax attorney Adam Bergman, who educates investors via weekly videos, podcasts, and blog articles.
Columbia Private Trust:
- Strong Google rating with a substantial review volume
- One of the longest-established SDIRA custodians (since 1989, originally PENSCO), now backed by Columbia Bank (NASDAQ: COLB)
- No meaningful presence on Trustpilot
Summary
Columbia Private Trust's Google reviews reflect genuine institutional credibility built over decades. IRA Financial's advantage comes from a strong, consistent presence across multiple major review platforms rather than concentrated on one.
Winner: IRA Financial.
Strong reviews at scale across multiple platforms, backed by decades of combined client feedback, versus a strong showing concentrated mainly on Google.
The Bottom Line: Why IRA Financial Is the Smarter Choice
Both IRA Financial and Columbia Private Trust are strong players in the Self-Directed IRA space, and Columbia Private Trust's institutional stability and decades of experience are real credentials for investors who prefer a traditional, compliance-first custodian. But for someone who wants a lower flat fee, checkbook control, direct crypto access, and broader account structures like Solo 401(k) and ROBS, IRA Financial offers more.
Whether you're looking to invest in real estate, trade crypto, or access public markets, IRA Financial is designed to support every part of your retirement strategy, efficiently, affordably, and under one roof.
Book a free call with a self-directed retirement specialist
- Review your self-directed retirement options
- Learn about investing in alternative assets
- Get all of your questions answered
SEP IRA for S-Corps vs LLCs vs Sole Props
A SEP IRA follows the same IRS framework across all business types, but entity structure controls what counts as compensation, and that directly changes how contributions are calculated. In 2026, most SEP IRA mistakes come from applying the right percentage to the wrong income base.
Key Takeaways:
- We cover what stays consistent across all SEP IRA accounts regardless of entity type
- How compensation is defined differently for sole proprietors, LLCs, and S-corporations
- Side-by-side examples showing how the same profit level produces different contribution amounts
- The most common entity-specific mistakes and how to avoid them
- A practical step-by-step check before finalizing any SEP IRA contribution
What Does Not Change Across SEP IRA Accounts in 2026
The SEP IRA framework stays consistent regardless of entity type. The following rules apply to all SEP IRA accounts: contributions are employer-only, they are based on compensation, the same percentage must be contributed for all eligible employees, and annual IRS contribution caps apply.
What does change is the definition of compensation, and that shift is based entirely on how income is reported under your business structure.
Why Entity Type Controls SEP IRA Contribution Math
The IRS ties SEP IRA contributions to compensation, not profit or cash flow. Each entity reports compensation differently, and that reporting difference determines which income number the percentage applies to, how deductions affect the contribution base, and whether distributions count at all.
Because each entity reports compensation differently, the same SEP percentage produces meaningfully different contribution amounts depending on your business structure.
SEP IRA for Sole Proprietors
Sole proprietors calculate SEP contributions from net earnings. Compensation for SEP purposes is net profit from Schedule C, reduced by the deductible portion of self-employment tax, and reduced again by the SEP contribution itself.
Because both self-employment tax deductions and the SEP contribution itself lower net earnings, sole proprietors use a reduced effective rate to arrive at the correct contribution amount.
Example: $120,000 net income
| Step | Amount |
|---|---|
| Net income | $120,000 |
| SE tax deduction (approx.) | $8,500 |
| Adjusted base | $111,500 |
| SEP contribution (20%) | $22,300 |
A SEP IRA works well for sole proprietors when income is stable and there is no need for employee deferrals or Roth contribution options.
SEP IRA for Single-Member and Multi-Member LLCs
An LLC does not have its own SEP calculation rules. Contributions are based on the entity's tax classification, which means single-member LLCs follow sole proprietor rules and multi-member LLCs follow partnership rules.
For partners in a multi-member LLC, compensation typically comes from guaranteed payments, not profit distributions. That distinction matters significantly because it caps SEP contributions by excluding certain types of income from the compensation base.
The most common LLC pitfall is treating distributions as SEP-eligible compensation. Distributions feel like income because they represent business profits paid to the owner. But the IRS distinguishes between compensation for services and distributions of profit, even when both land in the same bank account. Only guaranteed payments qualify as SEP compensation for partners. Applying the SEP percentage to distributions inflates the contribution calculation and creates correction risk.
SEP IRA for S-Corporations
S-Corporation SEP IRA rules are the most restrictive of the three. Compensation for SEP purposes is limited to W-2 wages paid to the owner. Shareholder distributions are excluded entirely.
Example: $150,000 total business profit
| Income Type | SEP Eligible |
|---|---|
| W-2 wages ($80,000) | Yes |
| Distributions ($70,000) | No |
SEP calculations exclude distributions because they are profit payouts, not compensation for services. For S-Corp owners who intentionally keep their W-2 wages low to minimize payroll taxes, this can significantly reduce the SEP contribution limit compared to what the same total income would produce under a sole proprietor structure.
Side-by-Side Comparison by Entity Type
| Entity Type | SEP Compensation Base | Common Mistake |
|---|---|---|
| Sole proprietor | Net earnings after deductions | Using gross income |
| Single-member LLC | Net earnings | Skipping SE tax adjustment |
| Partnership or multi-member LLC | Guaranteed payments | Using distributions |
| S-Corporation | W-2 wages only | Including distributions |
The SEP contribution percentage is fixed. What changes is the income it applies to, and that varies based on entity type and compensation rules.
Book a free call with a self-directed retirement specialist
- Review your self-directed retirement options
- Learn about investing in alternative assets
- Get all of your questions answered
How SEP IRA Employee Contribution Requirements Apply Regardless of Entity Type
SEP IRAs require equal treatment across all eligible employees. Whatever percentage the owner contributes for themselves must also be contributed for each eligible employee. Entity type does not change this rule. It changes how expensive the rule becomes as headcount grows.
This is why SEP IRAs lose efficiency as a business scales. A 20% contribution rate that works well for a solo operator can become a significant expense when applied across a growing team.
How Entity Choice Affects Maximum Contributions
Entity choice can cap contributions earlier than expected. S-corporations limit SEP contributions when wages are intentionally kept low to minimize payroll taxes. Sole proprietors and single-member LLCs allow higher contribution bases when profits are strong. Partnerships depend heavily on how payments to owners are structured and reported.
The practical implication is that identical profit levels can produce different SEP limits simply because each entity type uses a different compensation base. This is worth modeling before choosing a business structure for tax reasons, since the entity that minimizes current taxes may also unintentionally limit retirement contributions.
A Practical Step-by-Step Check Before Finalizing a SEP IRA Contribution
Most SEP IRA errors originate from starting with the wrong compensation figure and carrying that mistake through the rest of the calculation. This check helps catch problems before they become corrections.
1. Identify the exact income line that qualifies as compensation: Confirm whether the SEP contribution is based on W-2 wages, net earnings, or guaranteed payments. Using profit or distributions will overstate the limit.
2. Apply entity-specific adjustments to that income figure: Sole proprietors must account for self-employment tax deductions. Partnerships must isolate guaranteed payments. S-corporations must exclude all distributions from the calculation.
3. Run the calculation using IRS-approved adjusted rates: Self-employed owners need to apply the reduced effective SEP rate rather than the headline percentage to avoid circular overcontributions.
4. Review employee contribution requirements using the same percentage: Any percentage applied to the owner must also be applied to eligible employees. That can materially change the total cost of the contribution for business owners with staff.
5. Confirm the final number against the 2026 annual dollar cap: The calculated contribution cannot exceed the lesser of 25% of compensation or $72,000 for 2026.
Final Thoughts
The SEP IRA is one of the most straightforward retirement accounts available but straightforward does not mean simple when entity structure is involved. The same contribution percentage applied across different business types produces different results, and the difference is not always obvious until the math is done correctly.
Understanding how your entity type defines compensation is not a detail to sort out at tax time. It is the foundation of using a SEP IRA correctly from the start.
IRA Financial vs Broad Financial
For investors who want more control over their retirement savings, a Self-Directed IRA (SDIRA) makes it possible to go beyond Wall Street and invest in alternative assets such as real estate, private lending, startups, precious metals, and cryptocurrency. Two well-known providers in this space are IRA Financial and Broad Financial. Both offer Checkbook Control and Solo 401(k) plans, but their approaches differ, especially in fees, technology, and breadth of services. Broad Financial works in partnership with its sister company, Madison Trust, for custody and administration.
This comparison walks through pricing, investment options, technology, and reputation.
Pricing & Fees: Transparent, Flat, and Investor-Friendly
Note: this table compares the Checkbook IRA (IRA LLC) offering of both companies, since that is Broad Financial's core product.
IRA Financial | Broad Financial | |
Setup Fee | $0 | $1,270 ($1,145 LLC/Trust + $125 Madison Trust setup) |
Annual Fee | $495 | $556 |
Asset Value Fee | $0 | $0 |
Investment Fee | $0 | $0 |
Roth Conversion Fee | $0 | $100 |
1 Year Total Cost | $495 | $1,826 |
5 Year Total Cost | $2,475 | $3,494 |
Pricing pulled from company website, as of the article publish date, and based on a $200,000 account balance.
IRA Financial:
- Checkbook IRA setup fee of $999, then a flat $495/year with no transaction or asset value fees.
- No asset-based fees or per-transaction charges beyond the setup and annual fee.
- Integrated crypto investing with low trading costs inside the IRA Financial app.
Broad Financial:
- $1,145 one-time fee to establish the IRA LLC or IRA Trust, plus a separate $125 setup fee to Madison Trust as custodian.
- $556/year custodial fee, billed quarterly at $139, fixed regardless of account size or number of assets held.
- $100 fee if you convert or recharacterize a Roth IRA.
- Solo 401(k) plans carry a separate $995 setup fee plus a $149 annual compliance fee, not the IRA LLC/Trust custodial fee above.
Summary
Broad Financial's setup costs more upfront than IRA Financial's Checkbook IRA, but its flat $556/year custodial fee doesn't rise as you add more assets, unlike Madison Trust's direct per-asset pricing. Over 5 years, the gap between the two providers narrows to less than the cost of a single transaction.
Winner: IRA Financial.
A lower setup fee and a lower annual cost, though the margin is narrow for investors who plan to hold several assets long-term.
Product & Service Offerings: Focused vs. Full-Service
Choosing the right custodian depends on the types of investments you want to make and the level of support you need. IRA Financial and Broad Financial both give investors checkbook control, but Broad Financial's offering stays narrower and is built exclusively around checkbook structures.
IRA Financial | Broad Financial | |
Account Type | ||
Self-Directed IRA | ||
Solo 401(k) | ||
HSA | ||
Checkbook Control | ||
ROBS Structure | ||
Platform & Investments | ||
Crypto Platform | ||
Stock Trading | ||
Compliance & Protection | ||
In-House Compliance & Tax Services | ||
IRS Audit Protection |
IRA Financial:
- Full range of traditional SDIRA investments plus direct crypto investing through IRAfi Crypto, all inside one account.
- Offers both a standard custodian-directed Self-Directed IRA and a Checkbook IRA, so investors can choose the structure that fits their needs.
- Stock, ETF, bond, and options trading through Interactive Brokers, available as a $100/year add-on.
- Advanced structures including Solo 401(k), SEP and SIMPLE IRAs, HSA and Coverdell accounts, and ROBS for business funding.
- IRA Compliance Shield ($299/year): in-house audit protection, tax consultation, and prohibited transaction pre-clearance.
Broad Financial:
- Specializes exclusively in checkbook-control structures: IRA LLC, IRA Trust, and Solo 401(k), with no standard custodian-directed SDIRA option.
- Supports real estate, private lending, precious metals, tax liens, startups, and crypto through an LLC structure.
- Crypto access through CryptoFlex IRA requires a dedicated LLC and an external Titan Bank checking account.
- No HSA, Coverdell, or ROBS structures.
- Relies on Madison Trust for custody, recordkeeping, and compliance rather than offering it in-house.
Summary
Broad Financial's entire model is built around checkbook control, so investors who want that structure exclusively get a provider focused on doing it well. But there's no option to start with a simpler custodian-directed SDIRA and add checkbook control later, or vice versa. IRA Financial offers both structures side by side, plus a broader set of account types, integrated crypto trading, and in-house compliance support.
Winner: IRA Financial
More account types, the flexibility to choose a standard SDIRA or Checkbook IRA, and in-house compliance support that Broad Financial does not offer.
Technology: Built for the Modern Investor
Technology plays a growing role in managing retirement accounts, especially for investors who want real-time visibility. IRA Financial has built a mobile-first platform, while Broad Financial relies on web-based forms and its sister company's custodian portal.
IRA Financial:
- Newly-updated mobile app and account dashboard with clean UI/UX and modern functionality.
- Offers a fully digital on-boarding experience, automated compliance, and secure document storage.
- In-house crypto trading, real-time dashboards, and checkbook control in a single portal.
Broad Financial:
- Web-based forms and account setup through downloadable documents.
- No proprietary mobile app or live investor dashboard.
- Transactions and account management run through Madison Trust's custodian portal or manual communication.
Summary
Broad Financial leans on personalized onboarding and its custodian partner's portal rather than its own digital tools. IRA Financial keeps every feature, from real-time dashboards to crypto trading, under a single login.
Winner: IRA Financial.
A mobile-first, all-in-one platform, versus a process that relies on manual forms and a separate company's portal.
Reputation & Customer Reviews: Trusted by Thousands
Reputation matters when trusting a provider with your retirement assets. Both IRA Financial and Broad Financial have built track records in the self-directed space.
IRA Financial | Broad Financial | |
Trustpilot | 4.8 / 5 | 4.4/ 5 |
4.3 / 5 | 4.8 / 5 |
IRA Financial:
- Strong reputation for fast account setup, responsive customer service, and straightforward pricing.
- Over 3,000 5-star reviews across Google, Trustpilot, and other platforms.
- Founded by tax attorney Adam Bergman, who educates investors via weekly videos, podcasts, and blog articles.
Broad Financial:
- Strong Google rating with a large review volume, with clients praising responsive support.
- A+ BBB rating since 2014.
- Small sample size on Trustpilot, so its high rating carries less weight than a larger platform.
Summary
Broad Financial's Google reviews reflect a genuinely well-regarded support team at scale. IRA Financial's advantage comes from a strong, consistent presence across multiple major platforms rather than concentrated on one.
Winner: IRA Financial.
Strong reviews at scale across multiple platforms, versus a review base concentrated mostly on Google.
The Bottom Line: Why IRA Financial Is the Smarter Choice
Both IRA Financial and Broad Financial give investors checkbook control over their retirement funds, and Broad Financial's focused approach and personalized onboarding are real strengths for investors who want exactly that. But for someone who wants the flexibility to choose between a standard SDIRA or a Checkbook IRA, a broader set of account types, and in-house compliance support, IRA Financial offers more.
Whether you're looking to invest in real estate, trade crypto, or fund a new business with your retirement account, IRA Financial is designed to support every part of your retirement strategy, efficiently, affordably, and under one roof.
Book a free call with a self-directed retirement specialist
- Review your self-directed retirement options
- Learn about investing in alternative assets
- Get all of your questions answered
Self-Directed HSA Investment Rules by Asset Type
Most people think of an HSA as a healthcare spending account that earns a little interest. That significantly undersells what a Self-Directed HSA can actually do. In 2026, a properly structured Self-Directed HSA can hold real estate, private notes, private funds, digital assets, precious metals, and publicly traded stocks and ETFs, all growing tax-free inside an account originally designed for medical expenses.
HSAs have no approved asset list. What the IRS cares about is use, control, and personal benefit. Those three factors govern every investment decision inside the account.
Key Takeaways:
- How Self-Directed HSA investment rules actually work in 2026
- What each asset type looks like inside an HSA
- Where the compliance risk shows up
- How to do real-time stock trading alongside alternatives in one HSA
- The prohibited transaction triggers that catch investors off guard
- How to match assets to an HSA structure intelligently
How Self-Directed HSA Rules Work in 2026
Health Savings Accounts follow a narrower purpose than IRAs. The account exists to pay or reimburse qualified medical expenses, even though investment growth remains tax advantaged. That purpose shapes every compliance question.
The IRS focuses on outcomes. If funds benefit you outside of qualified medical expenses, penalties apply. HSAs do not publish an official approved asset list. They operate under transaction rules instead. That means compliance depends less on what you invest in and more on how income is used, how expenses are handled, and when distributions occur.
What a Self-Directed HSA Can Invest In
Broadly, a Self-Directed HSA can invest in public securities including stocks and ETFs, private funds, certain real estate structures, notes and private lending, precious metals, and digital assets depending on custodian support.
HSA compliance varies by asset type because each one affects use, tracking, and distributions differently. The sections below break down what that looks like in practice.
Real Estate
Real estate is one of the more complex assets to hold inside an HSA, not because it is prohibited, but because proper execution of ownership, expense payment, and income retention all have to be handled precisely.
Properties cannot be used personally by the account holder. Expenses must be paid directly from the HSA. Income must remain inside the account. And distributions must still align with qualified medical expenses regardless of what the property generates.
Unlike IRAs, HSAs introduce timing sensitivity that investors often underestimate. Rental income may grow tax-free inside the account, but it does not change the rules governing how and when distributions can be taken. Real estate compliance depends on consistent handling of payments and records throughout the life of the investment.
| Factor | Impact on HSA Compliance |
|---|---|
| Personal use | Creates a prohibited transaction |
| Expense handling | Requires precise payment flow from the HSA |
| Income timing | Must remain inside the HSA |
| Custodian speed | Affects closings and ongoing expense processing |
Private Notes and Lending
Private notes are operationally one of the cleaner assets to hold inside an HSA. There is no personal use risk, payment streams are predictable, income tracking is straightforward, and the structure does not require frequent expense reimbursements.
The compliance requirement is simple but non-negotiable: payments must route directly into the HSA to stay compliant. Where things get complicated is when payments arrive late or off schedule. At that point, custodian tracking quality becomes a real differentiator. A custodian without loan-specific workflows will struggle to keep records clean when a payment does not arrive on time.
Private Funds and Syndications
Private funds work inside an HSA when documentation supports compliant distributions tied to medical expenses. The extended holding periods typical of private equity and syndications are compatible with HSA rules. The liquidity mismatch is where investors need to plan carefully.
Capital calls must come from the HSA. Distributions remain inside the account. Valuations may be infrequent. And liquidity events can arrive at times that do not align with your medical expense needs.
Private funds work best inside an HSA when medical expenses are reasonably predictable, other cash sources exist to cover unexpected costs, and the HSA is part of a broader financial plan rather than the only source of liquidity for healthcare.
Crypto and Digital Assets
Crypto investments remain compliant inside an HSA when custodial controls around wallets, valuation, and reporting are properly maintained. Growth alone does not change how funds may be used. The same distribution rules that apply to every other HSA asset apply to crypto.
The practical considerations are wallet custody structure, valuation reporting consistency, token support limitations by custodian, and distribution documentation. Custodian platforms differ significantly in how they handle valuations and transaction records, which directly affects reporting complexity and audit readiness.
Precious Metals
Precious metals are one of the more straightforward alternative assets to hold inside a Self-Directed HSA. IRS-approved metals include certain gold, silver, platinum, and palladium coins and bars that meet purity standards. The compliance requirements are clean: the metals must be held by a qualified custodian, not personally by the account holder, and all purchases and sales must flow through the HSA.
The primary risk with precious metals is custody. Physical metals cannot sit in your home safe or a personally controlled storage facility. They must be held at an approved depository. Violating that requirement constitutes personal use and triggers a prohibited transaction. Beyond custody, precious metals are straightforward assets inside an HSA. There are no capital calls, no ongoing expense payments, and no income streams to track.
Stocks, ETFs, and Real-Time Trading
Most HSA investors who want exposure to public markets are limited to a narrow menu of mutual funds through their bank or insurer. IRA Financial's platform powered by Interactive Brokers changes that. Through our platform, HSA holders can trade stocks, ETFs, and bonds in real time inside their Self-Directed HSA, the same account that holds their alternative assets.
That combination is genuinely rare. IRA Financial is one of the only providers that offers real-time stock and ETF trading alongside alternative investments inside a single HSA. Every trade happens within the HSA's tax-free wrapper, which means stock gains, dividends, and alternative asset income all compound without annual tax drag.
For HSA investors who want a diversified portfolio rather than a single-asset strategy, this capability closes the gap between the flexibility a self-directed structure offers and the convenience of a traditional brokerage account.
Book a free call with a self-directed retirement specialist
- Review your self-directed retirement options
- Learn about investing in alternative assets
- Get all of your questions answered
Asset-by-Asset Allowance and Risk Overview
| Asset Type | Technically Allowed | Primary Risk Driver |
|---|---|---|
| Real estate | Yes | Personal use and expense handling |
| Private notes | Yes | Payment tracking |
| Private funds | Yes | Liquidity and valuation |
| Crypto | Yes, custodian-dependent | Custody and reporting |
| Precious metals | Yes, IRS-approved metals only | Custody requirements |
| Stocks and ETFs | Yes, via IRA Financial's Platform | Standard market risk, no HSA-specific compliance issues |
HSA Prohibited Transactions That Catch Investors Off Guard
Transactions become prohibited when they provide personal benefit or involve improper timing of distributions. The triggers I see most often are paying non-medical expenses from the account, reimbursing yourself without documentation, using HSA assets personally in any way, mixing personal and HSA funds, and taking distributions before qualified expenses occur.
Each issue ties back to use. The IRS is strict on that point, and the penalties for a prohibited transaction inside an HSA are significant. A single violation can disqualify the entire account.
How to Match Assets to an HSA in 2026
Investors who hold notes or funds inside an HSA tend to find the ongoing compliance simpler than real estate or other assets requiring frequent expense payments. Simple structures with predictable cash flows create fewer documentation demands over time.
Regardless of asset type, strong records linking every distribution to documented medical expenses are essential. Complex assets tend to fit more cleanly inside an HSA when the investor has other liquidity available and is not relying on the account for near-term healthcare spending. That is not a rule, but it is a pattern worth understanding before committing to a long-duration illiquid investment inside the account.
Final Thoughts
A Self-Directed HSA supports more asset types than most investors expect. Compliance depends on use, control, and documentation, not on how creative the investment strategy is. The accounts that stay powerful over time are the ones where every distribution is documented, every asset is properly titled, and the account holder understands that the flexibility comes with real responsibility.
In 2026, disciplined structure is what keeps a Self-Directed HSA both productive and penalty-free.
4 Ways to Fund a Self-Directed Roth IRA in 2026
The Self-Directed Roth IRA has become one of the most sought-after retirement structures available to investors who want both tax-free growth and control over what they invest in. While a standard IRA offers a tax break today, the Self-Directed Roth IRA offers something more valuable: a tax-free tomorrow, on assets that go far beyond stocks and mutual funds.
Key Takeaways:
- What a Roth IRA is and why it offers unique tax advantages
- The 2026 contribution limits, income restrictions, and the Backdoor Roth strategy
- Why a Self-Directed Roth IRA expands your investment universe
- The four funding pathways: transfer, rollover, contribution, and conversion
- How the Roth conversion and valuation discount strategy works
What Is a Roth IRA?
A Roth IRA is a type of individual retirement account where you contribute after-tax dollars. Because you have already paid taxes on the money you put in, your investments grow tax-free and your qualified distributions in retirement are entirely tax-exempt.
Three features make it stand out from every other retirement account structure.
Tax-free distributions. Unlike a Traditional IRA where every dollar withdrawn is taxed as ordinary income, every dollar you take out of a Roth IRA after meeting the requirements is yours to keep. You are effectively locking in today's tax rates to avoid potentially higher rates in the future.
No Required Minimum Distributions. Most retirement accounts force you to start taking money out at age 73 or 75. The Roth IRA does not. You can leave the money in the account for your entire life, allowing it to compound indefinitely.
Liquidity of contributions. You can withdraw your original contributions at any time, for any reason, tax and penalty-free. Since that money was already taxed, the IRS allows you to pull it back out if you need it, making it a powerful secondary source of liquidity.
https://youtu.be/olMIEmA8wlU
2026 rules and requirements
- Contribution limits: $7,500 for those under 50, or $8,600 if you are age 50 or older
- The 5-year rule and age 59½: To take qualified tax-free distributions of your earnings, the account must have been open for at least five years and you must be at least 59½
- Income restrictions: The IRS limits direct Roth IRA contributions for higher earners based on Modified Adjusted Gross Income (MAGI)
For single filers, the phase-out range in 2026 is $153,000 to $168,000. Below $153,000 you can make a full contribution. At $168,000 or above, direct contributions are not permitted.
For married couples filing jointly, the phase-out range is $242,000 to $252,000. Below $242,000 both spouses can fully fund their Roth IRAs. At $252,000 or above, direct contributions stop entirely.
For married filing separately, the phase-out range is $0 to $10,000, meaning almost any earned income disqualifies direct contributions.
Read more: IRS Announces 2026 401(k) and IRA Contribution Limits
The Backdoor Roth strategy
If your income exceeds the direct contribution limits, the Backdoor Roth IRA remains a fully legal option in 2026. By making a non-deductible contribution to a Traditional IRA, which has no income limits for the contribution itself, and then converting those funds to a Roth IRA, you can bypass the income restrictions entirely. The key is understanding the pro-rata tax rules that apply to the conversion, which IRA Financial's tax team works through with clients to ensure the conversion is handled correctly.
Read more: Mega Backdoor Roth
Why Set Up a Self-Directed Roth IRA in 2026?
A Self-Directed Roth IRA is simply a Roth IRA that allows you to invest in alternative assets. While a bank might only let you buy CDs or mutual funds, a self-directed custodian like IRA Financial gives you control over a much broader investment universe.
The combination of Roth tax treatment and alternative asset access is what makes this structure uniquely powerful. Most people have their entire retirement tied to the stock market. A Self-Directed Roth IRA lets you diversify into real estate, private businesses, precious metals, and crypto, assets that have historically moved independently of public markets and can serve as a natural hedge against inflation.
The compounding effect is significant. If your Roth IRA purchases an asset for $50,000 and that asset grows to $1,000,000, you will never pay a single cent of tax on that gain upon a qualified distribution. That is not a loophole. It is exactly what the Roth IRA was designed to do.
Book a free call with a self-directed retirement specialist
- Review your self-directed retirement options
- Learn about investing in alternative assets
- Get all of your questions answered
Pathway 1: The Roth IRA Transfer
If you already have a Roth IRA at a traditional firm, you can move those funds to a Self-Directed Roth IRA through a direct transfer. This is a custodian-to-custodian move that is entirely tax-free and does not count as a new contribution. You can transfer as much as you want, as often as you want.
IRA Financial handles the paperwork to pull the funds from your old provider, ensuring the money moves safely into the new self-directed structure so you can begin investing in alternative assets immediately.
Pathway 2: Rollover from a Roth 401(k)
If you have a Roth 401(k), sometimes called a Designated Roth Account, from a previous employer, you can roll those funds into a Self-Directed Roth IRA. While this is a tax-free event, it is governed by more specific IRS rules than a simple IRA-to-IRA transfer.
The triggering event requirement
Unlike a standard IRA, funds held in a 401(k) are locked within the employer's plan until a triggering event occurs. Common triggering events include separation from service (leaving the employer through resignation, retirement, or termination), reaching age 59½ under an in-service distribution provision, plan termination by the employer, or disability.
Without one of these events, the 401(k) custodian is not permitted to release the funds.
The like-to-like rule
Only the Roth portion of your 401(k), the funds you contributed after-tax, can be rolled into a Roth IRA. If your employer made matching or profit-sharing contributions on a pre-tax basis, those funds must roll into a Traditional IRA. Moving pre-tax employer contributions into a Roth IRA would be treated as a Roth conversion, triggering income tax in the year of the move.
Many of IRA Financial's 27,000 members choose to roll their Roth 401(k) funds into a Self-Directed Roth IRA specifically to escape plan-specific fees and the limited investment menu of corporate plans. By rolling over, those tax-free dollars can be put to work in real estate, private equity, and crypto under one flat-fee structure.
Always use a direct rollover. This ensures the check is made out to the new custodian on your behalf rather than to you personally. A direct rollover avoids the mandatory 20% federal tax withholding and eliminates the risk of missing the 60-day deposit window.
Pathway 3: Annual Contributions
For those starting fresh, you can fund your Self-Directed Roth IRA through annual contributions.
Even modest annual contributions benefit significantly from tax-free compounding over time. Because you can always withdraw your original contributions without penalty, this is also a low-risk way to begin your alternative investment journey. Starting small with fractional interests in real estate or smaller crypto positions allows the tax-free gains to build incrementally while you learn the structure.
Pathway 4: The Roth IRA Conversion
A Roth IRA conversion occurs when you move funds from a pre-tax account such as a Traditional IRA or 401(k) into a Roth IRA. The goal is to pay taxes on the value of the asset now, at today's tax rates, so that all future growth is entirely tax-free. This approach makes the most sense when you expect your investments to appreciate significantly or when you anticipate higher tax rates in the future.
The valuation discount strategy
When you convert an alternative asset, the tax you owe is based on the fair market value of that asset at the time of conversion. For certain types of assets held inside an IRA, that value can be legitimately lower than what an outside buyer might pay.
For example, if your IRA owns a minority stake in an LLC, that interest may be worth 20% to 40% less on paper due to lack of marketability or minority interest discounts. These are IRS-recognized valuation concepts, not workarounds. Converting at this lower valuation means paying less in tax today while still moving the entire asset into the tax-free Roth environment.
IRA Financial's tax team has worked through this process with clients across a wide range of alternative asset types. The key is ensuring the valuation methodology is properly documented and defensible under IRS standards, which requires genuine tax expertise rather than a generic template.
Final Thoughts
The Self-Directed Roth IRA combines two of the most powerful features in the retirement planning world: tax-free growth and investment flexibility. Used correctly, it allows you to build wealth in assets you understand, shield that wealth from future taxation, and pass it on without the forced distribution requirements that apply to every other retirement account type.
The rules surrounding these accounts are specific and the stakes are high. Getting the structure right from the start, and maintaining it correctly over time, is what separates investors who fully capture these benefits from those who encounter avoidable problems down the road.