

Why Self-Directed IRA Fees Really Matter
When investors evaluate retirement accounts, they typically focus on investment performance. They compare returns, asset classes, and market opportunities. They spend countless hours researching stocks, real estate, private equity, cryptocurrency, and other alternative investments.
What many overlook, however, is one of the most important factors influencing long-term retirement success: fees.
Every dollar paid in fees is a dollar that is no longer invested and no longer compounding for your future. As a tax attorney who has spent decades helping investors build retirement wealth through self-directed retirement accounts, I have seen firsthand how seemingly small fees can quietly erode retirement savings over time.
Key Takeaways
- Fee leakage, the ongoing reduction of retirement assets through recurring fees, is largely invisible but compounds against you over time. A modest 1% annual asset-based fee can cost hundreds of thousands of dollars over a 30 or 40-year retirement horizon.
- With a Self-Directed IRA, the investor identifies the investment, performs due diligence, negotiates the terms, and assumes the risk. The custodian's role is administrative. An asset-based fee that grows as your account grows does not reflect that division of work.
- Flat-fee pricing aligns the cost with the actual services being provided rather than the value of assets in the account, allowing investors to keep more of their gains and benefit more fully from long-term compounding.
- When evaluating a Self-Directed IRA provider, look beyond the setup fee. Asset valuation fees, transaction fees, wire fees, and account termination fees can significantly increase the true annual cost of maintaining an account.
Why Retirement Account Fees Deserve More Attention
Most investors understand that earning an extra 1% or 2% annually can significantly impact retirement outcomes. What many fail to recognize is that paying an extra 1% or 2% in fees can have the exact opposite effect.
Compounding is one of the most powerful forces in investing. When investment gains remain in a retirement account, those gains generate additional gains. Over time, this creates exponential growth. Unfortunately, fees compound as well. Every dollar removed from an account through fees not only reduces current account value but also eliminates all the future growth that dollar could have generated. This is commonly referred to as fee leakage, and it is largely invisible. Investors may not notice a $1,000 or $2,000 annual fee, but over decades, those fees can grow into hundreds of thousands of dollars of lost retirement wealth. The longer the investment horizon, the more damaging fee leakage becomes.
The Hidden Cost of Percentage-Based Fees
Many financial institutions charge fees based on a percentage of assets under management. The larger the account becomes, the larger the fee, even though the amount of administrative work required to maintain the account generally does not change.
Consider two fee structures applied to an account that begins with $100,000 and earns an average annual return of 10%.
| Investment Period | 1% Asset-Based Fee | $500 Flat Fee | Difference |
|---|---|---|---|
| 10 Years | ~$24,000 | $5,000 | $19,000 |
| 15 Years | ~$50,000 | $7,500 | $42,500 |
| 20 Years | ~$95,000 | $10,000 | $85,000 |
| 25 Years | ~$170,000 | $12,500 | $157,500 |
| 30 Years | ~$295,000 | $15,000 | $280,000 |
| 40 Years | $840,000+ | $20,000 | $820,000+ |
These figures reflect only fees paid. The actual economic impact is even greater because every dollar paid in fees also loses the opportunity to compound and generate future returns. Over a retirement lifetime, the difference can be staggering.
Why Flat Fees Make Sense for Self-Directed Investors
In a traditional wealth management relationship, an assets-under-management fee may be justified. If an advisor is selecting investments, managing a portfolio, monitoring performance, and providing ongoing investment advice, there is at least a rationale for tying compensation to account growth.
A Self-Directed IRA is fundamentally different.
With a Self-Directed IRA, the investor is doing the work. The investor identifies the opportunity, performs due diligence, negotiates the terms, assumes the risk, and makes the investment decision. The custodian's role is to administer the account, maintain records, process transactions, and satisfy IRS reporting requirements. Those administrative responsibilities generally do not become more complex simply because an account grows from $100,000 to $1 million.
Consider two Self-Directed IRA investors. One account remains at $100,000. The other invests in real estate, private equity, or Bitcoin and grows to $2 million. Under an asset-based fee model, the second investor pays tens of thousands of dollars more annually for essentially the same custodial services. The custodian did not find the investment, negotiate the deal, contribute capital, or assume any investment risk. Yet it participates in the upside simply because the asset appreciated.
That structure is difficult to justify. Every dollar paid in unnecessary fees is a dollar that can no longer compound for retirement. Over 10, 20, 30, or 40 years, that fee leakage can cost investors hundreds of thousands of dollars. Flat-fee pricing solves this problem by aligning the fee with the actual services being provided, not the value of the assets in the account.
Why Fees Matter Even More for Alternative Assets
Fee considerations become particularly important when investing in alternative assets. Many Self-Directed IRA investors own real estate, private equity, venture capital, cryptocurrency, mortgage notes, precious metals, and private businesses. These investments often involve long holding periods and significant appreciation potential.
An asset-based fee structure can become increasingly expensive as those investments grow in value. An investor who purchases a private investment for $100,000 that appreciates to $1 million may find that annual percentage-based fees increase dramatically despite no meaningful increase in administrative complexity. This is one reason many experienced alternative asset investors pay close attention to fee structures before selecting a retirement account provider.
Book a free call with a self-directed retirement specialist
- Review your self-directed retirement options
- Learn about investing in alternative assets
- Get all of your questions answered
Looking Beyond the Advertised Fee
When evaluating a Self-Directed IRA provider, look beyond the initial setup fee. Some providers charge asset valuation fees, transaction fees, wire fees, annual maintenance fees, asset-based custody fees, and account termination fees. Understanding the complete fee structure is critical. A provider with a low setup fee may ultimately become significantly more expensive if recurring fees increase as account values grow.
Investors should always ask for a complete breakdown of all fees before opening an account, including whether any fees increase as account values grow and how total fees compare with alternative providers.
Focus on What You Can Control
No investor can control market performance, interest rates, or inflation. But every investor can control fees.
While selecting quality investments remains important, minimizing unnecessary fee leakage may be one of the easiest ways to improve long-term retirement results. The impact of a lower fee structure may not be obvious in the first year. Over 10, 20, 30, or 40 years, however, the difference can be substantial.
Most investors spend their time searching for the next great investment opportunity. Far fewer spend the same amount of time evaluating what may be one of the biggest drags on long-term retirement wealth. As a tax attorney, I have always believed that retirement planning is not simply about maximizing returns. It is about maximizing the amount of wealth that ultimately remains in your retirement account.
At IRA Financial, we have always embraced a flat-fee model because we believe investors should keep as much of their hard-earned retirement wealth as possible. When our clients win, they should keep the benefits of that success. The purpose of a Self-Directed IRA is to empower investors to take control of their retirement and build wealth through their own investment decisions. Escalating asset-based custody fees that grow simply because your investments performed well work against that purpose.
The goal of retirement planning is not merely to accumulate assets. It is to maximize the wealth available when you need it most. The less money that leaves your account in unnecessary fees, the more money remains working for you. And over a lifetime of investing, that difference can be enormous.

IRA Financial vs The Entrust Group
For investors seeking greater control over their retirement portfolios with alternative assets, such as real estate, private equity, precious metals, and cryptocurrencies, selecting the right Self-Directed IRA or Solo 401(k) provider is essential. The Entrust Group has built a strong reputation over more than 40 years in the industry, while IRA Financial offers a modern, flexible approach built around flat pricing and integrated technology.
This comparison examines fees, product options, technology, and reputation to help investors make an informed decision.
Pricing & Fees: Transparent, Flat, and Investor-Friendly
Understanding the fee structure is critical for retirement investors, as costs can accumulate over time and impact overall returns. IRA Financial uses a single flat annual fee, while The Entrust Group charges an asset-value-based recordkeeping fee plus a separate charge for every purchase, sale, or exchange.
IRA Financial | The Entrust Group | |
Setup Fee | $0 | $50 |
Annual Fee | $495 | $329 |
Asset Value Fee | $0 | $255 |
Investment Fee | $0 | $420 |
Roth Conversion Fee | $0 | $0 |
1 Year Total Cost | $495 | $1,054 |
5 Year Total Cost | $2,475 | $3,390 |
Pricing pulled from company website, as of the article publish date, based on 4 investments with a $200K total balance.
IRA Financial:
- Self-Directed IRAs start at $495/year, with other plans available from $100/year
- No setup fee for a custodian-controlled plan; a one-time fee applies only for Checkbook IRA structures
- No asset-based or transaction fees, just one clear, predictable price
- IRAfi Crypto platform offers low-cost trading for buying, selling, and managing crypto directly in the app
The Entrust Group:
- $50 one-time account establishment fee
- Annual recordkeeping fee of $329/year for two or more assets, plus 0.17% of total asset value over $50,000
- $105 fee for the purchase, sale, or exchange of most alternative assets ($175 for real estate)
- Recordkeeping fees are capped at $2,299/year regardless of account size
Summary
The Entrust Group's asset-value-based recordkeeping fee combined with a per-transaction charge on every purchase or sale adds up quickly for investors holding several assets. For an investor with 4 assets on a $200,000 balance, Entrust costs more than double what IRA Financial charges in year one, and the gap grows further over 5 years.
Winner: IRA Financial.
A single flat annual fee with no per-transaction charges and no cost that climbs as the account's asset value grows.
Investment Flexibility & Product Options
The range of investment options and account structures available can significantly affect portfolio diversification and long-term flexibility.
IRA Financial | The Entrust Group | |
Account Type | ||
Self-Directed IRA | ||
Solo 401(k) | ||
HSA | ||
Checkbook Control | ||
ROBS Structure | ||
Platform & Investments | ||
Crypto Platform | ||
Stock Trading | ||
Compliance & Protection | ||
In-House Compliance & Tax Services | ||
IRS Audit Protection |
IRA Financial:
- Full investment freedom: real estate, private equity, precious metals, notes, startups, and crypto
- Direct crypto investing through IRA Financial's integrated platform
- Checkbook IRA and Solo 401(k) options for maximum control, with the LLC formed for you as part of the service
- Supports SEP, SIMPLE, Roth, and Traditional IRAs, plus ROBS for business funding
The Entrust Group:
- Offers Self-Directed IRAs, Solo 401(k)s, HSAs, and Coverdell ESAs, a broader set of tax-advantaged account types than most competitors
- Supports checkbook control through an IRA LLC, but Entrust explicitly does not create or sell LLCs, investors must set one up independently
- No ROBS structure, integrated stock trading, or in-house compliance and audit protection services
Summary
The Entrust Group offers a genuinely broad set of account types, including HSAs and Coverdell ESAs that not every custodian supports. Where IRA Financial pulls ahead is in business-funding structures like ROBS, fully integrated crypto and stock trading, and handling LLC formation directly rather than leaving that step to the investor.
Winner: IRA Financial
Broader business-funding options and a fully integrated platform, including LLC formation for checkbook control, that Entrust leaves to the investor to arrange independently.
Technology: Built for the Modern Investor
An intuitive, integrated platform can save time and reduce errors, especially for investors handling multiple alternative assets.
IRA Financial:
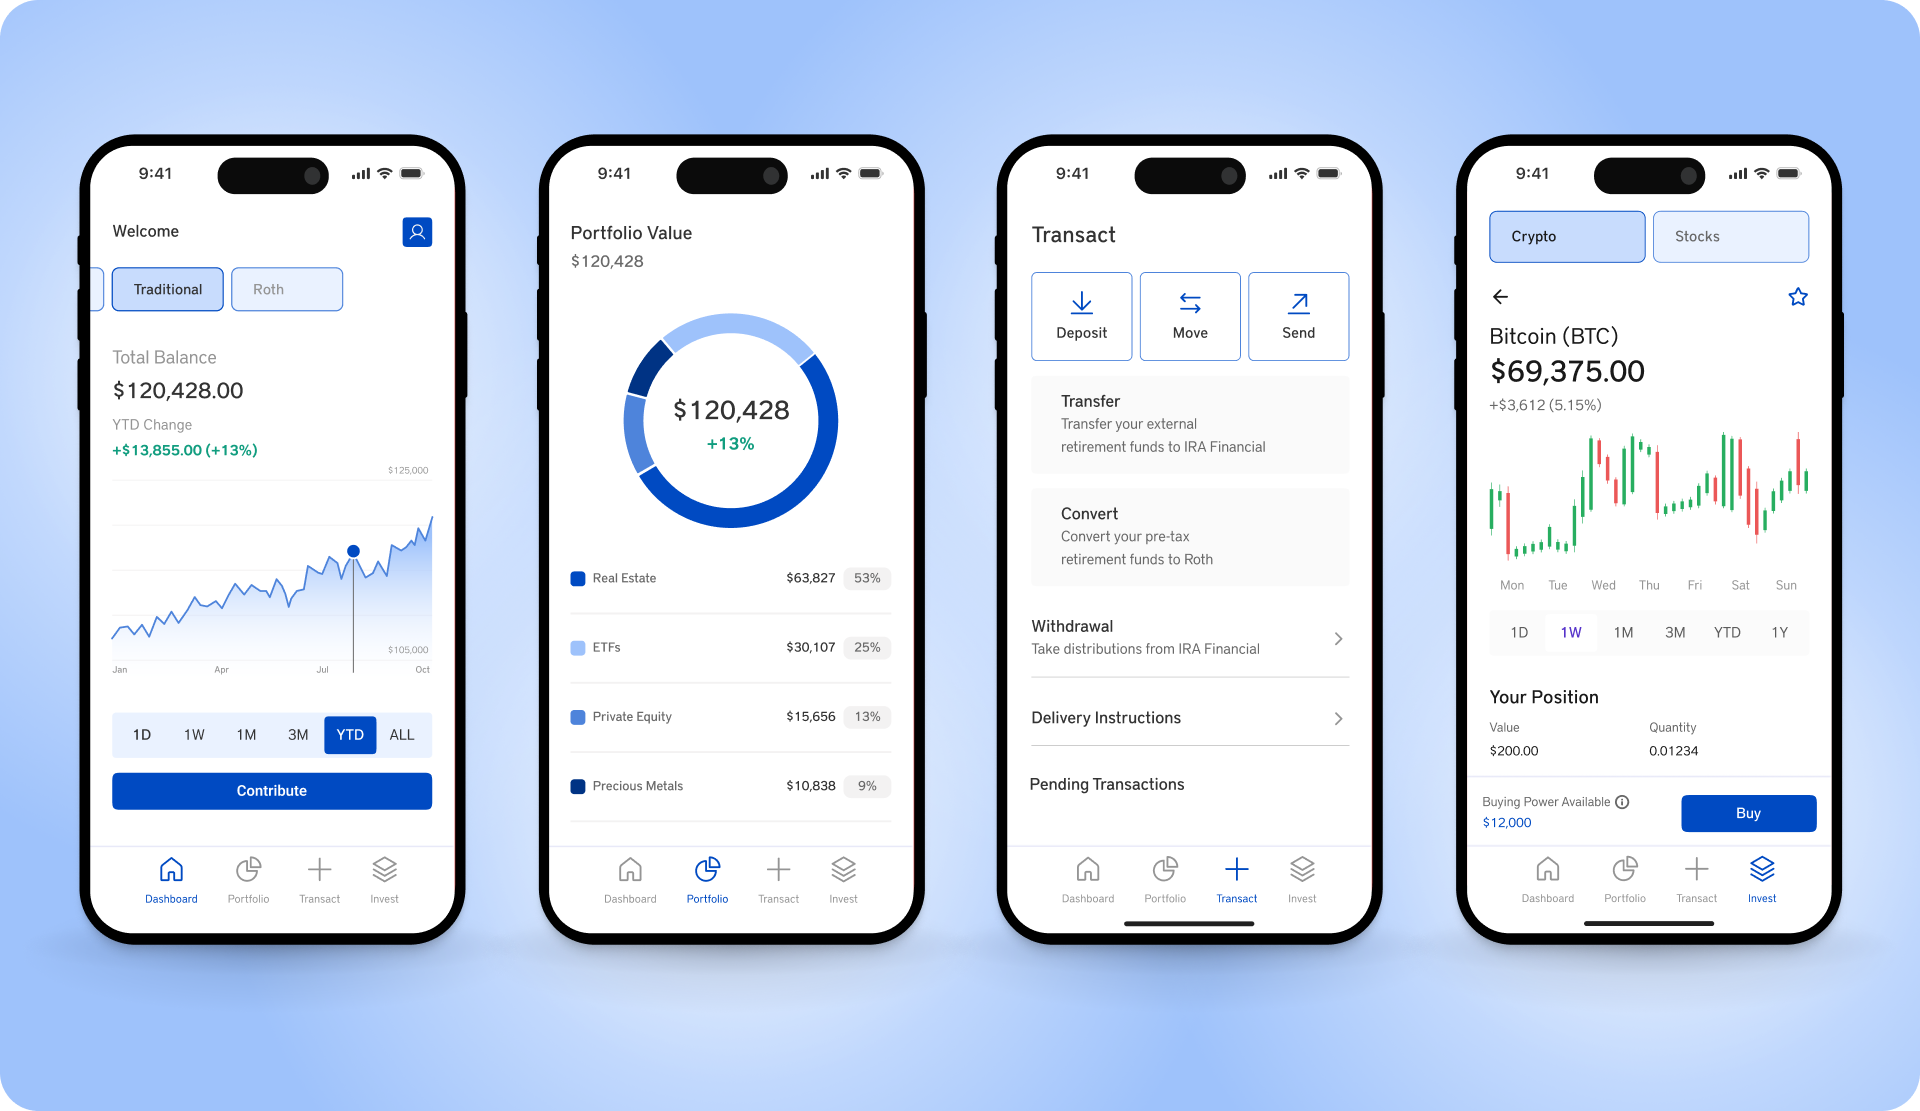
- Newly-updated mobile app and account dashboard with clean UI/UX and modern functionality.
- Offers a fully digital on-boarding experience, automated compliance, and secure document storage.
- Streamlined tools for crypto, transfers, and checkbook control in one place
The Entrust Group:
- Functional online portal for account management
- Documentation process is more traditional and may involve additional paperwork
- Support is available but less integrated with technology
Summary
Entrust has a reliable system for managing Self-Directed IRAs, but IRA Financial's technology-driven approach reduces administrative hurdles and gives investors faster, more efficient control.
Winner: IRA Financial.
Modern platform enhances efficiency and investor confidence.
Reputation & Customer Reviews: Trusted by Thousands
Longevity and reliability are key considerations for custodians of retirement accounts, though online review sentiment can tell a different story than years in business alone.
IRA Financial | The Entrust Group | |
Trustpilot | 4.8 / 5 | 1.8 / 5 |
4.3 / 5 | 4.4 / 5 |
IRA Financial:
- Strong reputation for fast account setup, responsive customer service, and straightforward pricing.
- Over 3,000 5-star reviews across Google, Trustpilot, and other platforms.
- Founded by tax attorney Adam Bergman, who educates investors via weekly videos, podcasts, and blog articles.
The Entrust Group:
- One of the oldest Self-Directed IRA custodians in the U.S., founded in 1981
- Solid Google rating with a meaningful review volume
- Trustpilot reviews skew heavily negative, with recent complaints citing high fees and slow response times
Summary
The Entrust Group's decades of experience and solid Google rating are real credentials, but its Trustpilot reviews reveal a notable gap in day-to-day client sentiment. IRA Financial holds a strong, consistent rating across every major platform.
Winner: IRA Financial.
Consistently strong ratings across platforms, without the sharp platform-to-platform swing Entrust shows between Google and Trustpilot.
The Bottom Line: Why IRA Financial Is the Smarter Choice
Both The Entrust Group and IRA Financial offer secure paths for investing in alternative assets through self-directed retirement accounts. Entrust's decades of experience and broad account type support, including HSAs and Coverdell ESAs, are genuine strengths for investors who value that history. But for investors who want lower, more predictable fees, business-funding structures like ROBS, and a fully integrated platform that handles LLC formation directly, IRA Financial offers more.
Book a free call with a self-directed retirement specialist
- Review your self-directed retirement options
- Learn about investing in alternative assets
- Get all of your questions answered
How to Buy Mortgage Notes With a Self-Directed IRA in 2026
Most Self-Directed IRA investors are familiar with investing in rental real estate, private funds, precious metals, and cryptocurrency. However, one of the most overlooked investment opportunities available through a Self-Directed IRA is mortgage note investing.
Mortgage notes can offer attractive yields, recurring income, and the security of real estate collateral without the responsibilities of property ownership. In today's higher interest rate environment, many investors are once again turning to mortgage notes as an alternative to traditional fixed-income investments.
As a tax attorney who has spent decades helping retirement investors diversify beyond Wall Street, I have seen mortgage notes become a valuable component of many retirement portfolios. When structured properly, mortgage note investments can generate tax-deferred income inside a Traditional IRA or potentially tax-free income inside a Roth IRA.
Key Takeaways
- A mortgage note investment turns your Self-Directed IRA into the lender. Instead of purchasing real estate directly, your IRA purchases the right to receive future principal and interest payments from a borrower, secured by real property.
- Interest income generated by a mortgage note held inside an IRA is generally not subject to current taxation. It grows tax-deferred in a Traditional Self-Directed IRA or potentially tax-free in a Roth Self-Directed IRA.
- Unlike leveraged real estate investments, mortgage note investments generally do not trigger Unrelated Debt-Financed Income tax because the IRA is acting as the lender rather than the borrower.
- The prohibited transaction rules under IRC Section 4975 apply to mortgage note investing. Your IRA generally cannot lend money to, or purchase notes from, disqualified persons including the IRA owner, their spouse, parents, children, or entities they control.
- The two structures available for mortgage note investing through a Self-Directed IRA are the full-service custodian-controlled IRA and the Self-Directed IRA LLC with checkbook control. Both offer the same tax advantages but differ in control, speed, and administrative requirements.
What Is a Mortgage Note?
A mortgage note is a legal agreement in which a borrower promises to repay money borrowed from a lender. The note typically outlines the principal amount, interest rate, repayment schedule, maturity date, and default provisions. In most cases, the note is secured by real estate through a mortgage or deed of trust, which gives the lender certain rights against the property if the borrower fails to make payments.
When investing in mortgage notes through a Self-Directed IRA, your IRA essentially becomes the lender. Instead of purchasing real estate directly, your IRA purchases the right to receive future payments from the borrower. Those payments consist of principal and interest and flow directly back into the IRA.
Mortgage notes can be secured by residential real estate, commercial real estate, vacant land, multifamily properties, construction projects, and seller-financed transactions. Because the investment is backed by real property, many investors view mortgage notes as offering a balance between income generation and collateral protection.
Why Mortgage Notes Are Becoming More Popular in 2026
The mortgage note market has experienced renewed interest in recent years due to several significant economic trends.
Interest rates remain substantially higher than they were during the ultra-low-rate environment of 2020 through 2022. Higher borrowing costs have increased demand for alternative lending and private financing solutions. Private credit has also emerged as one of the fastest-growing investment sectors globally, with investors seeking yield increasingly looking beyond traditional bonds and into asset-backed lending opportunities such as mortgage notes.
Additionally, certain segments of the mortgage market have begun experiencing increased delinquency levels. While overall mortgage performance remains relatively healthy, rising delinquencies have created opportunities for investors interested in purchasing both performing and non-performing notes. As a result, Self-Directed IRA investors have access to a broader range of mortgage note opportunities than they have seen in years.
Why Mortgage Notes Work Well in a Self-Directed IRA
Mortgage notes can be particularly attractive retirement investments because they generally generate passive interest income. From a tax perspective, interest income earned by an IRA is generally not subject to current taxation. The income grows tax-deferred in a Traditional IRA or potentially tax-free in a Roth IRA.
Unlike leveraged real estate investments, mortgage note investments generally do not trigger Unrelated Debt-Financed Income because the IRA is acting as the lender rather than the borrower.
Many investors appreciate mortgage notes because they offer predictable cash flow, real estate-backed collateral, no property management responsibilities, no tenant issues, diversification from stocks and bonds, and tax-advantaged growth. For retirement investors seeking income-producing investments without directly owning property, mortgage notes can be an attractive solution.
Types of Mortgage Notes
Performing Notes. A performing note is one where the borrower is making payments as agreed. These notes typically provide consistent monthly income and generally involve less risk. Investors often purchase performing notes to generate predictable cash flow within their retirement accounts.
Non-Performing Notes. A non-performing note is one where the borrower has stopped making payments. These notes are often purchased at significant discounts and may provide opportunities for greater returns, but they require substantially more due diligence, legal oversight, and patience. Investors in non-performing notes may seek to modify the loan, negotiate repayment terms, reinstate the loan, foreclose on the property, or acquire the underlying real estate. Non-performing notes are generally better suited for experienced investors.
First-Lien Notes. A first-position mortgage has priority over all junior liens. If foreclosure becomes necessary, the first-position lender generally gets paid before any subordinate lienholders. For many Self-Directed IRA investors, first-lien residential notes represent the most conservative approach to mortgage note investing.
Second-Lien Notes. Second mortgages are subordinate to first mortgages. While second-position notes may offer higher yields, they also carry additional risk because the first-position lender has priority in a foreclosure scenario.
Book a free call with a self-directed retirement specialist
- Review your self-directed retirement options
- Learn about investing in alternative assets
- Get all of your questions answered
Two Ways to Purchase Mortgage Notes Through a Self-Directed IRA
Full-Service Custodian-Controlled Self-Directed IRA. Under this structure, a special IRA custodian such as IRA Financial serves as the custodian and handles all investment transactions on behalf of the IRA. The note is titled in the name of the IRA custodian for the benefit of the IRA owner. For example: IRA Financial Trust Company FBO John Smith IRA. All principal and interest payments flow back to the IRA through the custodian, and the custodian handles all required IRS administration including filing Forms 1099-R and 5498. This approach is best suited for investors making less frequent investments who prefer additional custodian oversight.
Self-Directed IRA LLC with Checkbook Control. Under this structure, a limited liability company is created, funded, and owned entirely by the IRA, with the IRA owner serving as manager. Because the investor controls the LLC directly, they can execute mortgage note transactions, sign documents, and send funds without waiting for custodian approval on every transaction. The note is titled in the name of the LLC rather than the IRA directly. This structure is particularly well suited for mortgage note investing because notes often require quick action, multiple transactions, and ongoing payment management. The IRA LLC structure was affirmed by the Tax Court in Swanson v. Commissioner, 106 T.C. 76 (1996), and later confirmed by the IRS in Field Service Advice Memorandum 200128011.
Important Tax Rules to Understand
One of the biggest advantages of mortgage note investing is that the tax rules are generally straightforward. Interest income generated by a mortgage note is generally exempt from current taxation while inside the IRA. However, investors must still comply with the prohibited transaction rules under Internal Revenue Code Section 4975.
These rules prohibit an IRA from engaging in transactions with disqualified persons, including the IRA owner, the owner's spouse, parents, grandparents, children, grandchildren, and certain entities controlled by these individuals. Your IRA generally cannot lend money to your child, purchase a note from your spouse, or acquire a mortgage secured by property owned by a disqualified person. Violating these rules can result in the entire IRA being deemed distributed, triggering taxes and potentially significant penalties.
As I often tell clients, the investment itself is rarely the problem. Most prohibited transactions occur because investors unknowingly engage in transactions with family members or businesses they control.
Due Diligence Tips for Mortgage Note Investors
Verify the collateral. Never purchase a mortgage note without understanding the underlying property. Review the property value, condition, title reports, tax records, insurance coverage, and existing liens before committing IRA funds.
Focus on loan-to-value ratios. The lower the LTV, the larger the equity cushion protecting the lender. A $150,000 loan secured by a $300,000 property provides significantly more protection than a $270,000 loan on the same asset.
Review payment history. A borrower's payment history often tells a more complete story than the interest rate alone. A note yielding 8% with a strong payment history may be far more attractive than a note yielding 12% with repeated delinquencies.
Understand foreclosure laws. Foreclosure procedures vary dramatically by state. Some states allow relatively efficient processes while others may involve lengthy judicial proceedings. Before purchasing a note, understand the legal costs, timelines, and procedures that may apply if the borrower defaults.
Obtain independent due diligence. Never rely solely on information provided by the seller. Independent verification of property values, title status, taxes, insurance, and payment history can help avoid costly mistakes.
Keep proper records. Retain copies of all promissory notes, mortgages or deeds of trust, assignments, payment histories, insurance records, and title reports. Proper documentation is particularly important for IRA compliance purposes.
Potential Risks of Mortgage Note Investing
Like any investment, mortgage notes involve risk. Potential risks include borrower default, property value declines, foreclosure costs, bankruptcy proceedings, title defects, insurance issues, and market illiquidity. Mortgage notes are generally less liquid than publicly traded securities, and investors should be prepared to hold notes for extended periods. For this reason, note investing is often best viewed as a long-term retirement strategy rather than a short-term trading opportunity.
Final Thoughts
Mortgage notes continue to represent one of the most compelling opportunities available to Self-Directed IRA investors. In a higher-rate environment, they can provide attractive income, diversification, and real estate-backed security while avoiding many of the management challenges associated with direct property ownership.
From a tax attorney's perspective, the key to successful mortgage note investing is not simply finding the highest yield. It is understanding the collateral, conducting thorough due diligence, maintaining compliance with the prohibited transaction rules, and ensuring the investment is properly structured through the IRA. When done correctly, mortgage notes can provide a powerful combination of income, asset protection, and tax-advantaged growth that can help investors build long-term retirement wealth.
IRA Financial vs Rocket Dollar
For investors looking to diversify their retirement portfolios with alternative assets, such as real estate, precious metals, private companies, and cryptocurrencies, selecting the right Self-Directed IRA or Solo 401(k) provider is critical. Each provider offers unique features, fee structures, and account management tools that can significantly impact your retirement strategy.
Two well-known names in the self-directed space are IRA Financial and Rocket Dollar. Both offer checkbook control and access to alternative assets, but they differ in how their account types are priced. IRA Financial offers a standard Self-Directed IRA, a Checkbook IRA, and a Solo 401(k) as distinct account types, each with its own transparent pricing, while Rocket Dollar bundles checkbook control and Solo 401(k) access into its higher-cost tiers. This comparison looks at IRA Financial and Rocket Dollar across pricing, product options, technology, and reputation, helping investors make an informed decision.
Pricing & Fees: Transparent, Flat, and Investor-Friendly
When it comes to retirement investing, predictable costs and transparent pricing are essential. High or unclear fees can eat into investment returns over time, particularly for those investing in alternative assets like real estate or private equity. To compare equivalent capabilities, this table uses IRA Financial's Checkbook IRA pricing against Rocket Dollar's Platinum tier, since both include checkbook control.
IRA Financial | Rocket Dollar | |
Setup Fee | $999 | $900 |
Annual Fee | $495 | $600 |
Asset Value Fee | $0 | $0 |
Investment Fee | $0 | $0 |
Roth Conversion Fee | $0 | $0 |
1 Year Total Cost | $1,494 | $1,500 |
5 Year Total Cost | $3,474 | $3,900 |
Pricing pulled from company website, as of the article publish date, based on 4 investments with a $200K total balance.
IRA Financial:
- Checkbook IRA setup fee of $999, then a flat $495/year, with no transaction or asset-based fees
- A standard, custodian-directed Self-Directed IRA is also available with no setup fee, for investors who don't need checkbook control
- IRAfi Crypto platform with low trading costs for buying, selling, and trading crypto directly in the IRA Financial app.
Rocket Dollar:
- Three pricing tiers: Silver ($360 setup + $30/month) offers a Self-Directed IRA only, with no checkbook control
- Gold ($600 setup + $40/month) adds Checkbook IRA w/ Trust
- Platinum ($900 setup + $50/month) adds Checkbook IRA w/ LLC and Solo 401(k) access, the tier most comparable to IRA Financial's Checkbook IRA
- No asset-based fees or per-investment fees on any tier, though their custodian, Digital Trust, may charge separate transaction or asset-related fees depending on the specific investment
Summary
Comparing tiers with equivalent capabilities tells a closer story than pricing alone might suggest: IRA Financial's Checkbook IRA costs slightly more upfront than Rocket Dollar's Platinum tier, but a lower annual fee brings the total cost close over time, with IRA Financial coming out ahead by a modest margin over 5 years.
Winner: IRA Financial.
A lower annual fee holds the edge over 5 years once both platforms' checkbook-control and Solo 401(k) tiers are compared directly, though the year-one costs are nearly identical.
Investment Flexibility & Product Options
A self-directed retirement account should allow you to invest in a wide range of assets without unnecessary restrictions. Having multiple options gives investors the flexibility to diversify and optimize returns. Both IRA Financial and Rocket Dollar support checkbook control and a broad set of alternative assets, but IRA Financial includes several account types and services that Rocket Dollar does not offer at any tier.
IRA Financial | Rocket Dollar | |
Account Type | ||
Self-Directed IRA | ||
Solo 401(k) | ||
HSA | ||
Checkbook Control | ||
ROBS Structure | ||
Platform & Investments | ||
Crypto Platform | ||
Stock Trading | ||
Compliance & Protection | ||
In-House Compliance & Tax Services | ||
IRS Audit Protection |
IRA Financial:
- Offers all the traditional SDIRA investments, including real estate, private lending, startups, precious metals, as well as direct crypto investing.
- Integrated platform for crypto, checkbook control, real estate, and more under one roof.
- Stock, ETF, bond, and options trading powered by Interactive Brokers - available as a $100/year add-on, fully integrated inside your IRA Financial account.
- Advanced structures like Solo 401(k) plans, SEP & SIMPLE IRAs, HSA & Coverdell accounts, and ROBS structures for business funding.
- IRA Compliance Shield ($299/year): in-house audit protection, tax consultation, deal reviews, prohibited transaction pre-clearance, and UBIT/UDFI modeling.
Rocket Dollar:
- Offers Self-Directed IRAs and Solo 401(k) plans, including Traditional and Roth accounts, though checkbook control and Solo 401(k) access are only available on their Gold and Platinum tiers, not their base Silver plan
- Supports alternative assets such as real estate, private equity, and cryptocurrencies through an extensive partner network
- Stock and bond trading is not well supported inside a standard Rocket Dollar account; investors are advised to keep a separate brokerage IRA for public securities
- No ROBS structure, HSA, or in-house compliance and audit protection services
Summary
Rocket Dollar covers the fundamentals of checkbook-controlled alternative investing well, and its partner network gives investors curated access to deals. IRA Financial goes further with business-funding structures like ROBS, HSA accounts, integrated stock trading, and in-house compliance support.
Winner: IRA Financial
More account types, integrated stock trading, and in-house compliance support that Rocket Dollar does not offer.
Technology: Built for the Modern Investor
An intuitive platform can save time and reduce errors when managing retirement accounts, especially when handling multiple alternative investments. Technology and support matter for both experienced and first-time self-directed investors.
IRA Financial:
- Newly-updated mobile app and account dashboard with clean UI/UX and modern functionality.
- Offers a fully digital on-boarding experience, automated compliance, and secure document storage.
- In-house crypto trading, real-time dashboards, and checkbook control in a single portal.
Rocket Dollar:
- Online platform for account setup, funding, and investment tracking
- Functional but may require customer support for complex transactions
- Limited integration for alternative asset documentation
Summary
Rocket Dollar provides a functional platform, but IRA Financial's technology and support reduce administrative burdens, making it easier to invest efficiently and confidently across a range of asset types.
Winner: IRA Financial.
Smooth, integrated platform enhances efficiency and investor confidence.
Reputation & Customer Reviews: Trusted by Thousands
Trust and reliability are crucial when choosing a custodian for retirement accounts, particularly for alternative assets. Reputation can reflect both longevity in the industry and the quality of support offered to clients. Both IRA Financial and Rocket Dollar have positive track records, though their review presence looks different depending on the platform.
IRA Financial | Rocket Dollar | |
Trustpilot | 4.8 / 5 | 3.3 / 5 |
4.3 / 5 | 4.9 / 5 |
IRA Financial:
- Strong reputation for fast account setup, responsive customer service, and straightforward pricing.
- Over 3,000 5-star reviews across Google, Trustpilot, and other platforms.
- Founded by tax attorney Adam Bergman, who educates investors via weekly videos, podcasts, and blog articles.
Rocket Dollar:
- Strong Google rating at meaningful scale: 4.9/5 from 381 reviews
- Very limited presence on Trustpilot (only 2 reviews), too small a sample to draw conclusions from
- Known for enabling alternative asset investing and strong cryptocurrency support
Summary
Rocket Dollar's Google reviews are genuinely excellent and backed by a real sample size, a legitimate strength. Where IRA Financial pulls ahead is consistency across multiple platforms rather than being concentrated on just one.
Winner: IRA Financial.
A large, consistent review base across multiple platforms, rather than strength concentrated on a single review site.
The Bottom Line: Why IRA Financial Is the Smarter Choice
Both Rocket Dollar and IRA Financial offer options for self-directed retirement accounts and alternative asset investing. Rocket Dollar's Silver plan is a genuinely strong low-cost entry point for investors who want checkbook control without a lot of complexity. But for investors who want broader account types, integrated stock trading, in-house compliance support, and a platform with a larger, more established review base, IRA Financial offers more.
Book a free call with a self-directed retirement specialist
- Review your self-directed retirement options
- Learn about investing in alternative assets
- Get all of your questions answered
Carried Interest in Your Roth IRA: What Investment Professionals Need to Know
For private equity managers, venture capital sponsors, real estate syndicators, and hedge fund managers, a carried interest is often the most valuable economic asset they will ever create. A successful carry can generate millions of dollars in long-term gains over the life of a fund. The challenge is that those gains are generally taxable when received.
But what if some or all of that carried interest could be legally owned by a Roth IRA?
If properly structured, a carried interest held inside a Self-Directed Roth IRA can potentially generate decades of tax-free growth and ultimately produce tax-free distributions. For the right investment professional, it may be one of the most powerful retirement planning strategies available under the Internal Revenue Code.
The strategy is not new. Congress has never prohibited a Roth IRA from owning a carried interest or profits interest. However, the transaction sits at the intersection of partnership taxation, retirement account rules, valuation principles, and the IRS prohibited transaction rules under Internal Revenue Code Section 4975. The structure must be carefully implemented.
Two legal principles are central to getting this right. First, the Roth IRA must acquire the carried interest at fair market value. Second, the Roth IRA owner and other disqualified persons generally should own less than 50% of the entity selling or issuing the carried interest. Get those two issues wrong and the strategy could be challenged by the IRS. Get them right and the Roth IRA may become one of the most tax-efficient places to hold future carried interest economics.
Key Takeaways
- A carried interest held inside a Self-Directed Roth IRA can potentially grow and distribute completely tax-free if the Roth IRA rules are satisfied, making it one of the most powerful tax planning strategies available to fund managers and sponsors.
- The Roth IRA must acquire the carried interest at fair market value. The best time to structure the transaction is near fund formation, when the carry often has little or no liquidation value because no profits yet exist.
- The Roth IRA owner and all disqualified persons combined should generally own less than 50% of the entity issuing or transferring the carried interest to avoid prohibited transaction risk under IRC Section 4975.
- Three primary structures exist for allocating a carried interest to a Roth IRA: having the Roth IRA invest in the general partner entity, having the Roth IRA purchase the carry directly from the general partner, or issuing a special class of interests directly to the Roth IRA. Each carries different risks.
- UBIT analysis is highly fact-specific. Carried interest allocations that retain capital gain character may not generate UBIT, but leverage at the fund level can create UDFI exposure that must be evaluated before implementation.
What Is a Carried Interest?
A carried interest is a profits interest granted to the sponsor, general partner, or manager of an investment fund. Unlike a capital interest, which represents ownership based on contributed capital, a carried interest represents the right to receive a share of future profits after investors receive their invested capital back and, in many cases, a preferred return.
In a typical private equity, venture capital, private credit, or real estate fund, investors receive 80% of the profits while the sponsor receives 20% through the carried interest. The carried interest holder often contributes little or no capital but participates in the upside generated by successful investments.
Because the carried interest is contingent on future performance, it often has very little value when the fund is initially formed. However, if the fund performs well, the value can become substantial. This unique characteristic is precisely what creates the Roth IRA planning opportunity.
Under current law, investment fund managers often report income from carried interest at the long-term capital gains rate. This has generated some controversy since some argue that a carried interest functions more like compensation and should be taxed accordingly. Regardless of that debate, the opportunity to hold the carry inside a Roth IRA remains an attractive and legitimate planning strategy.
Why a Roth IRA Creates a Powerful Tax Opportunity
A Roth IRA is one of the most valuable tax planning vehicles available. Unlike a Traditional IRA, where future distributions are generally taxable, qualified Roth IRA distributions are completely tax-free. There are also no required minimum distributions during the Roth IRA owner's lifetime.
A carried interest fits the Roth IRA profile almost perfectly. At inception, a carried interest may have minimal current value. Years later, it may generate significant profits from successful exits, refinancings, recapitalizations, or portfolio company sales. If those economics accrue inside a Roth IRA, the long-term tax savings can be extraordinary.
Why a Self-Directed Roth IRA Is Required
Traditional brokerage firms generally do not permit private carried interest investments. To invest in private funds or hold a carried interest, a Self-Directed Roth IRA is required. A Self-Directed Roth IRA allows the account to own alternative assets, including private equity, venture capital, private credit funds, and partnership interests, subject to IRS rules.
In some cases, the Roth IRA invests directly into the carry vehicle. In others, the Roth IRA owns a special purpose LLC, often referred to as a checkbook control IRA LLC, which then holds the carried interest. This structure can simplify administration but must be set up correctly to avoid prohibited transactions.
Book a free call with a self-directed retirement specialist
- Review your self-directed retirement options
- Learn about investing in alternative assets
- Get all of your questions answered
Three Ways to Structure a Carried Interest in a Roth IRA
The 2014 Government Accountability Office report on IRAs identified several approaches for allocating a carried interest to a Roth IRA. Each has different risk profiles.
Option 1: Roth IRA Invests in the General Partner Entity
By having the Roth IRA own interests in the general partner or management entity, any profits interest allocated to that entity would pass through proportionally to the Roth IRA. The risk here is twofold. First, an argument can be made that the management company is engaged in an active trade or business, which could subject the carried interest passed through to the Roth IRA to the Unrelated Business Income Tax at up to 37%. Second, if the Roth IRA owner and other disqualified persons together own more than 50% of the general partner, significant prohibited transaction concerns arise. This approach requires careful analysis before implementation.
Option 2: Roth IRA Purchases the Carried Interest from the General Partner
Under this structure, the general partner or fund manager sells some or all of the carried interest directly to the Roth IRA. The transaction shifts ownership of the carry from the general partner to the retirement account. The critical issues are valuation and prohibited transaction compliance. The Roth IRA must pay fair market value, and the ownership structure of the selling entity must be carefully reviewed to avoid prohibited transaction exposure.
Option 3: Issuing a Special Class of Interests Directly to the Roth IRA
This approach is generally considered the cleanest and carries the least prohibited transaction risk. Rather than having the Roth IRA transact with the general partner entity, a new class of partnership interests is issued directly to the Roth IRA at formation.
For example, the general partner establishes a fund and creates two classes of interests. The standard limited partner class receives the normal investment return. A second class, often called Class B, is issued to the Roth IRA at a lower initial value because it is subject to a different distribution waterfall that only produces returns upon a highly successful capital event. If the fund performs exceptionally well, the Class B interests receive the carried interest economics. If the fund underperforms, the Class B interests may produce no return at all.
Because the Class B units are priced to reflect their increased risk and subordinated position, they can be acquired by the Roth IRA at a relatively low initial value. This structure also reduces direct transaction risk with the management entity because the Roth IRA is investing in the fund itself rather than purchasing from the general partner.
The key requirement is that the Class B units must be priced to accurately reflect their risk profile. The lower price must be justified by the terms of the distribution waterfall, not by an artificial attempt to shift future value into the Roth IRA at below-market pricing.
The Critical Requirement: Fair Market Value
When evaluating any carried interest Roth IRA strategy, valuation is the first issue I focus on as a tax attorney. The IRS has repeatedly challenged transactions where taxpayers attempted to shift future value into a Roth IRA without paying fair market value.
The best time to structure the transaction is generally near fund formation. At that stage, the carried interest often has little or no liquidation value because investors have not yet received returns and future profits remain speculative. A carried interest at inception frequently has a fair market value near zero under liquidation methodology.
The Roth IRA cannot receive the carried interest for free, nor can it purchase the interest at an artificially depressed price. The transaction must be conducted at fair market value, and that valuation should be documented contemporaneously. Obtaining a third-party valuation or a defensible valuation memorandum at the time of acquisition is a best practice.
Prohibited Transaction Rules
The IRS prohibited transaction rules under Internal Revenue Code Section 4975 do not restrict what a retirement account can invest in. They restrict who the retirement account can transact with.
A disqualified person is generally defined as the IRA owner, their lineal descendants, their spouse, and any entity controlled by such persons at more than 50% in the aggregate. If the general partner or fund management entity is owned more than 50% by the Roth IRA holder, their lineal descendants, and their retirement accounts combined, significant prohibited transaction concerns arise.
Even if aggregate ownership falls below 50%, self-dealing and conflict-of-interest type transactions must be carefully analyzed under the specific facts and circumstances of each situation.
For most investment funds, the limited partners own 90% or more of the LP interests, which significantly limits the applicability of the prohibited transaction rules and is one reason the Class B interest structure is often viewed as the most defensible approach.
UBIT Considerations
One of the most frequently asked questions involves Unrelated Business Income Tax. The answer depends on the nature of the carried interest and the underlying fund investments.
Many practitioners take the position that carried interest allocations that retain capital gain character should not generate UBIT because capital gains are generally excluded from unrelated business taxable income under the Internal Revenue Code. However, if leverage is used at the fund level, debt-financed income issues may arise under the Unrelated Debt-Financed Income rules, creating UBIT exposure even on otherwise clean carried interest allocations.
The UBIT analysis is highly fact-specific and should be completed before implementing any Roth IRA carried interest strategy. When UBIT exposure is a concern, some investors choose to interpose a C Corporation blocker between the Roth IRA and the fund. The corporation pays tax at the 21% corporate rate, and dividends to the Roth IRA are generally not subject to UBIT. This approach trades certainty for added complexity and some tax drag, but for certain strategies it may be appropriate.
Understanding the Actual Risk Profile
A proper understanding of the risk involved helps place this strategy in perspective.
If the IRS were to challenge a Roth IRA carried interest transaction as a prohibited transaction, the consequence under Internal Revenue Code Section 408(e) is generally that the IRA is treated as having been distributed as of the first day of the year in which the violation occurred. The value of the IRA investment becomes taxable as a distribution.
This is where proper valuation becomes particularly important. In most cases, a newly created carried interest has very little current fair market value at inception. The Roth IRA may invest $5,000, $10,000, or $25,000 to acquire a carry that could eventually generate millions of dollars of future profits. Even if the IRS were to challenge the transaction, the taxable amount at issue would typically be the modest fair market value at the time of acquisition, not the future appreciation.
This does not mean the rules should be ignored. Proper valuation, documentation, and prohibited transaction analysis remain essential. But it does help frame the risk-reward profile of a well-structured transaction realistically.
Final Thoughts
The ability to allocate a carried interest to a Roth IRA is a genuine and significant tax planning opportunity for fund managers, sponsors, and syndicators. When properly structured, the future economics of a successful carry can accumulate and distribute completely tax-free inside a retirement account.
Two issues require the most careful attention: valuation and the prohibited transaction rules. The Roth IRA must acquire the carried interest at fair market value, ideally near fund formation when that value is at its lowest. And the ownership structure of the entity issuing or selling the carry must be carefully designed to avoid prohibited transaction exposure.
Before implementing any carried interest Roth IRA strategy, investors should work with qualified tax and ERISA counsel to ensure the transaction is properly structured and documented. The opportunity is significant, but the execution must be disciplined.
How the Solo 401(k) Loan Can Save You Thousands in Credit Card Interest
If there is one financial trend that concerns me more than almost anything else today, it is the explosion of high-interest consumer debt. As a tax attorney, I spend my days helping entrepreneurs and investors legally reduce taxes and build long-term wealth. Yet I constantly meet successful business owners who are paying 20%, 25%, or even 30% interest on credit cards while simultaneously contributing to retirement accounts.
That simply does not make financial sense.
Far too many Americans are trapped in a cycle of debt. They make monthly credit card payments, but because interest rates are so high, very little of those payments actually reduce the principal balance. Others turn to payday loans or short-term cash advances that carry even higher effective interest rates, making it nearly impossible to get ahead.
Fortunately, if you are self-employed, there may be a much better solution that most financial advisors rarely discuss: the Solo 401(k) loan. Used responsibly, it can allow you to pay off expensive credit card debt, eliminate payday loans, improve your cash flow, and unlike borrowing from a bank, the interest you pay goes back into your own retirement account instead of enriching a credit card company.
Key Takeaways
- Americans owe nearly $1.25 trillion on credit cards, with average interest rates above 20%. Every dollar paid in interest is a dollar that cannot be invested or saved for retirement.
- A Solo 401(k) participant can borrow up to $50,000 or 50% of their vested account balance, whichever is less, with no credit check and no underwriting process.
- Unlike a bank loan, the interest paid on a Solo 401(k) loan goes back into your own retirement account rather than to a lender.
- The loan can be used for any purpose, including paying off high-interest credit card balances, covering unexpected expenses, or managing temporary business cash flow needs.
- The Solo 401(k) loan feature is not available in an IRA. It is unique to qualified retirement plans.
America's Credit Card Debt Problem
Americans owe nearly $1.25 trillion on their credit cards, while average credit card interest rates have climbed above 20%, with many consumers paying 24% or even 30%. Millions more rely on payday loans and other forms of emergency financing that can carry annualized rates approaching 400%. The result is staggering: Americans now pay well over $250 billion each year in credit card interest and fees, money that goes directly to banks and credit card companies instead of helping families build wealth.
The problem is not borrowing money itself. Businesses borrow every day to grow, and consumers occasionally need access to credit for unexpected expenses. The real problem is the cost of that debt. At rates of 20% to 30%, borrowers can spend years making payments while barely reducing the principal balance. A $30,000 credit card balance at 24% generates roughly $7,200 of interest every year if the balance remains outstanding. Instead of building wealth, you are effectively paying thousands of dollars annually to a credit card company simply for the privilege of borrowing money.
Every dollar paid in interest to a credit card company is a dollar that can never be invested, never earn compound returns, and never help fund your retirement. Over decades, that lost opportunity can amount to hundreds of thousands of dollars.
The Solo 401(k): One of the Most Powerful Retirement Plans Ever Created
The Solo 401(k) is available to almost anyone with self-employment income, whether you operate a full-time business, own an LLC, work as an independent contractor, earn consulting income, or have a profitable side hustle. To establish one, you must have self-employment income and generally cannot employ full-time employees other than yourself and, if applicable, your spouse.
For 2026, participants can generally contribute up to $72,000, with even higher limits available for those eligible for catch-up contributions. Contributions may be made on a pre-tax basis, reducing current taxable income, or as Roth contributions, allowing investments to grow completely tax-free if the distribution requirements are satisfied.
A properly designed Solo 401(k) also offers checkbook control, meaning you serve as trustee of your own plan and can write checks or initiate wires directly from the plan's bank account without waiting for custodian approval on every transaction. That flexibility opens the door to far more than traditional stocks and mutual funds, including cryptocurrency, rental real estate, private equity, venture capital, private lending, precious metals, and many other alternative assets.
The plan also enjoys excellent creditor protection under both federal and state law, and when purchasing real estate with a nonrecourse loan, a Solo 401(k) is generally exempt from the Unrelated Debt-Financed Income tax that typically applies to leveraged real estate owned by an IRA.
Despite all of these benefits, there is one feature that receives far too little attention: the ability to borrow from your own retirement account.
How the Solo 401(k) Loan Works
Unlike an IRA, a Solo 401(k) can generally allow participants to borrow from their retirement savings without triggering taxes or penalties, provided the loan satisfies the requirements of the Internal Revenue Code and the terms of the plan document.
Generally, a Solo 401(k) participant may borrow the lesser of $50,000 or 50% of the vested account balance. If your balance is $60,000, you can borrow up to $30,000. If your balance is $100,000 or more, you can generally borrow the maximum $50,000.
There is no credit check. Your credit score does not matter, your debt-to-income ratio does not matter, and there is no lengthy underwriting process. As long as your plan permits participant loans and you satisfy the IRS requirements, you can generally access the funds quickly.
The proceeds can be used for virtually any purpose: paying off high-interest credit card balances, eliminating payday loans, covering unexpected medical expenses, making home repairs, funding college tuition, consolidating debt, covering temporary business expenses, or simply providing short-term liquidity during a difficult period.
Repayment is generally required over no more than five years through substantially level installments of principal and interest, unless the loan is used to purchase a primary residence, in which case a longer repayment period may be permitted.
Now here is the part that changes the economics entirely. When you borrow from a bank, every interest payment benefits the bank. When you borrow from a Solo 401(k), the interest you pay is credited back to your own retirement account. You are paying yourself instead of paying a lender.
Using the current Prime Rate as an example, if your plan carries a 6.75% interest rate and you borrow $10,000 to eliminate credit card debt charging 24%, you are paying approximately $675 in annual interest rather than $2,400, and every dollar of that interest flows back into your own retirement account.
One important tradeoff: while the money is out on loan, it is no longer invested in the market. If the market performs exceptionally well during that period, you may miss some investment gains. That is why I generally recommend using a Solo 401(k) loan only when it serves a meaningful financial purpose, such as eliminating high-interest debt, not for unnecessary spending.
Book a free call with a self-directed retirement specialist
- Review your self-directed retirement options
- Learn about investing in alternative assets
- Get all of your questions answered
Case Study 1: Eliminating $40,000 of Credit Card Debt
John is a 45-year-old self-employed marketing consultant who has accumulated $200,000 in his Solo 401(k). After several slow business months, he relied on credit cards and now carries $40,000 in debt at 24% interest.
He has two options.
If John continues making credit card payments, his $40,000 balance generates approximately $9,600 of interest every year at 24%. Over five years of disciplined repayment, his monthly payment would be approximately $1,150 and he would pay nearly $29,000 in total interest directly to the credit card company.
Instead, John borrows $40,000 from his Solo 401(k) at 6.75% and immediately pays off every credit card balance. Repaid over five years, his monthly payment drops to approximately $787 and he pays approximately $7,200 in total interest, every dollar of which goes back into his own retirement account.
| Solo 401(k) Loan | Credit Card at 24% | |
|---|---|---|
| Monthly Payment | ~$787 | ~$1,150 |
| Total Interest Over Five Years | ~$7,200 | ~$29,000 |
| Interest Paid To | Your retirement account | The credit card company |
By using the Solo 401(k) loan, John lowers his monthly payment by more than $350, saves roughly $22,000 in interest, and redirects approximately $7,200 back into his own retirement account instead of a bank's pocket.
Case Study 2: Eliminating $13,000 of Credit Card Debt
Sarah is a self-employed consultant with $13,000 of credit card debt at 24% interest and more than $26,000 in her Solo 401(k), making her eligible to borrow up to $13,000.
Rather than continuing to pay 24% interest, Sarah borrows $13,000 from her Solo 401(k) at 6.75% and immediately pays off her balance. Repaid over five years, her monthly payment is approximately $256 and she pays approximately $2,340 in total interest back into her own account.
If Sarah had kept the credit card balance and committed to paying it off over the same five years, her monthly payment would have been approximately $374 and she would have paid roughly $9,450 in interest to the credit card company.
| Solo 401(k) Loan | Credit Card at 24% | |
|---|---|---|
| Monthly Payment | ~$256 | ~$374 |
| Total Interest Over Five Years | ~$2,340 | ~$9,450 |
| Interest Paid To | Your retirement account | The credit card company |
By using the Solo 401(k) loan, Sarah reduces her monthly payment by approximately $118, saves about $7,100 in borrowing costs, and redirects more than $2,300 of interest back into her own retirement account.
The Same Strategy Works for Payday Loans
The benefits become even more dramatic when payday loans are involved. Payday loans can carry annualized interest rates that exceed several hundred percent, and many borrowers repay one only to immediately take out another, creating a cycle that is extremely difficult to escape.
Consider a self-employed graphic designer who has built a Solo 401(k) worth $120,000 and finds herself with $15,000 in payday loans and high-interest cash advances after unexpected medical bills and several slow business months. Rather than continuing to refinance those loans at exorbitant rates, she borrows $15,000 from her Solo 401(k), immediately eliminates every payday loan, and begins repaying herself at a fraction of the cost. The payday loan cycle ends, her borrowing cost drops dramatically, her monthly payments become manageable, and every interest payment now rebuilds her retirement savings instead of going to a lender.
An Important Word of Caution
The Solo 401(k) loan is not a tool for financing vacations, luxury purchases, or unnecessary spending. The purpose of this strategy is to replace very expensive debt with far less expensive debt while allowing you to repay yourself rather than a financial institution.
Used responsibly, it can help business owners regain control of their finances, improve cash flow, reduce interest expense, and continue building long-term retirement wealth. But discipline is essential. If you eliminate your credit card balances only to run them up again, you have simply created a new financial problem. Used as a one-time tool to break free from high-interest debt with a commitment to responsible borrowing going forward, it can be one of the smartest financial decisions a self-employed individual ever makes.
Final Thoughts
The Solo 401(k) is one of the most powerful retirement plans available to self-employed Americans. It offers high contribution limits, valuable tax deductions, Roth contribution options, checkbook control, access to alternative investments, and the unique ability to borrow from your retirement savings without creating a taxable distribution when the loan is properly structured and repaid. No IRA offers that combination.
If you are self-employed and carrying high-interest credit card debt, do not assume your only choices are expensive personal loans, debt settlement companies, or payday lenders. The Solo 401(k) loan may be a far better alternative, one where you borrow from yourself at a fraction of the cost and repay the interest back into your own retirement account.
At IRA Financial, we have helped tens of thousands of entrepreneurs establish Solo 401(k) plans specifically designed to maximize the benefits Congress intended, including participant loans, Roth contributions, checkbook control, and the ability to invest in virtually any asset permitted under the Internal Revenue Code. If you want to understand whether a Solo 401(k) loan could work for your situation, our team of in-house tax specialists is available for a free consultation.
The smartest way to regain control of your finances may not be borrowing from someone else at all. It may be borrowing from yourself.
How Do You Title Real Estate in a Self-Directed IRA?
Real estate has long been one of the most popular alternative investments held inside retirement accounts. Many investors understand the benefits of owning rental properties, commercial buildings, raw land, or private real estate investments, but few realize that retirement funds can often be used to acquire these assets while preserving the tax advantages of an IRA.
A Self-Directed IRA allows retirement investors to move beyond traditional Wall Street investments and invest in assets they know and understand. While most brokerage firms limit IRA investments to stocks, bonds, mutual funds, and ETFs, the Internal Revenue Code generally permits IRAs to invest in almost any asset class except life insurance and collectibles. As a result, real estate has become one of the most common investments held within self-directed retirement accounts.
However, not all Self-Directed IRAs operate the same way. Investors generally have two options when purchasing real estate through a retirement account: a traditional custodian-administered Self-Directed IRA, often referred to as a full-service SDIRA, or a Self-Directed IRA LLC structure, commonly known as a checkbook control IRA. While both structures allow investors to purchase real estate using retirement funds, the way they operate, the level of investor control, and the administrative requirements are significantly different. Understanding these differences is critical because the right structure can make the process of acquiring and managing real estate substantially easier and more efficient.
Key Takeaways
- How real estate is titled in a Self-Directed IRA depends entirely on which structure is used. With a full-service custodian-controlled IRA, title is held in the custodian's name for the benefit of the IRA owner. With a Self-Directed IRA LLC, title is held in the name of the LLC.
- A Self-Directed IRA is not a separate legal term found in the Internal Revenue Code. It is simply an IRA administered by a custodian willing to permit investments beyond traditional securities, following the same tax rules as any other IRA.
- The full-service Self-Directed IRA is best suited for investors making passive investments that do not require frequent transactions, such as raw land or private fund investments.
- The Self-Directed IRA LLC, or checkbook control IRA, is better suited for active real estate investors who need the ability to move quickly, sign contracts directly, pay expenses without custodian delays, and manage multiple properties efficiently.
- Neither structure is inherently better. The right choice depends on how actively the investor intends to participate in real estate investing.
What Is a Self-Directed IRA?
Contrary to popular belief, a Self-Directed IRA is not a separate type of retirement account recognized under the Internal Revenue Code. It is simply an IRA administered by a custodian willing to permit investments beyond traditional securities.
From a tax perspective, a Self-Directed IRA follows the same rules as any other IRA. A Traditional Self-Directed IRA generally offers tax-deferred growth, meaning investments can grow without current taxation until distributions are taken. A Roth Self-Directed IRA is funded with after-tax dollars, but qualified distributions are completely tax-free. The primary distinction between a conventional IRA and a Self-Directed IRA is investment flexibility. Instead of being limited to publicly traded securities, a Self-Directed IRA can invest in real estate, private placements, private lending transactions, cryptocurrency, precious metals, tax liens, and many other alternative assets.
For investors who have expertise in real estate, this flexibility can be particularly attractive. Rather than investing retirement funds in assets they may not fully understand, they can use those funds to acquire properties, generate rental income, and potentially build long-term wealth within a tax-advantaged environment.
The Two Types of Self-Directed IRAs for Real Estate
Although investors often refer to all Self-Directed IRAs as if they operate identically, there are two primary structures used for real estate investing. The first is a traditional full-service Self-Directed IRA where the custodian remains actively involved in all investment transactions. The second utilizes a limited liability company owned by the IRA, giving the investor direct control through checkbook control. Both structures are fully permissible under IRS rules but differ considerably in terms of administration, flexibility, transaction speed, and cost.
Full-Service Self-Directed IRA
Under a full-service Self-Directed IRA structure, the custodian remains directly involved in every aspect of the investment transaction. The IRA owns the real estate directly, and the custodian serves as the record owner on behalf of the IRA.
When an investor identifies a property for purchase, they submit the contract and supporting documentation to the custodian. The custodian reviews the paperwork, processes the investment instructions, and sends the funds necessary to complete the acquisition. After the purchase is completed, all rental income flows back into the IRA account, and all expenses related to the property are paid directly by the IRA through the custodian.
For example, suppose John has $250,000 in his Self-Directed IRA and wishes to purchase a rental property for $200,000. John negotiates the purchase terms and submits the contract to his custodian. The custodian wires the funds from the IRA to the closing agent. Once the property is acquired, rental income is deposited into the IRA account, and expenses such as property taxes, insurance premiums, or repair costs are paid from IRA funds through the custodian.
The primary advantage of this structure is simplicity. Because the custodian remains involved in every transaction, investors have fewer administrative responsibilities. There is no need to establish a separate LLC, maintain corporate records, or manage a dedicated bank account. Startup costs are also generally lower because there are no LLC formation or annual maintenance expenses.
The primary disadvantage is that every transaction requires custodian involvement. Investors cannot write a check to a contractor, pay an earnest money deposit, or wire funds directly. They must submit instructions to the custodian and wait for processing. While this helps maintain compliance, it can create delays when a real estate transaction requires immediate action.
This structure is most appropriate for investors making passive investments that do not involve a high volume of transactions, such as raw land or private fund investments.
Self-Directed IRA LLC (Checkbook Control)
The Self-Directed IRA LLC structure is commonly referred to as a checkbook control IRA. Under this arrangement, the IRA forms and owns 100% of a limited liability company. The IRA owner typically serves as the manager of the LLC, while the IRA itself serves as the sole member and owner.
After the LLC is established, the IRA transfers its investment funds into the LLC's bank account. Because the investor serves as manager, they gain direct authority to control the LLC's assets and execute investment transactions without requiring custodian approval for each activity. In practical terms, this means the investor can write checks, send wires, sign purchase contracts, and manage investments directly from the LLC bank account.
For example, if John's IRA owns Sunshine LLC and John serves as manager, John can identify a property, negotiate the purchase terms, sign the contract as manager, and send funds directly from the LLC bank account to complete the acquisition without any custodian involvement.
This structure has become the most popular option for active real estate investors for three primary reasons.
Speed and control. Investors can react quickly to investment opportunities without waiting for custodian approval. This is especially valuable when purchasing distressed properties, participating in auctions, making private loans, or investing in competitive markets where timing is critical.
Limited liability protection. LLCs are recognized as separate legal entities, meaning the IRA owner's personal assets and the IRA itself are protected from the debts, obligations, and liabilities of the LLC. For investors owning multiple properties, this separation is particularly important.
Privacy. When an LLC makes an investment, the investment is recorded in the name of the LLC rather than the IRA custodian or the individual investor. Depending on the state in which the LLC is established, identifying the owner can be difficult. States such as Delaware and Wyoming offer particularly strong privacy protections.
The tradeoff is greater responsibility. Investors must maintain the LLC properly, keep accurate records, ensure all transactions comply with IRS prohibited transaction rules, and avoid commingling personal and retirement assets.
Book a free call with a self-directed retirement specialist
- Review your self-directed retirement options
- Learn about investing in alternative assets
- Get all of your questions answered
How Real Estate Is Titled in Each Structure
One of the most misunderstood aspects of Self-Directed IRA real estate investing is how title to the property is held. Getting this right is essential because the property must be owned by the retirement account, not the individual investor.
Full-service Self-Directed IRA titling. When the IRA owns the property directly through the custodian, title typically appears as:
IRA Financial Trust Company CFBO John Doe IRA
The custodian's name appears on title because the custodian is serving as the legal holder of the asset on behalf of the IRA. The investor's personal name should never appear as the property owner.
For example, if Lisa Smith is purchasing a property at 1234 Apple Street using her Roth IRA, she provides IRA Financial Trust, as custodian, the requisite closing documents for signature. Title to the property would be recorded as:
IRA Financial Trust Company FBO Lisa Smith Roth IRA
All income and gains from the property flow back to Lisa's Roth IRA tax-free. All expenses must be paid by the IRA custodian on behalf of the IRA since the IRA owns the asset, not Lisa personally.
Self-Directed IRA LLC titling. When a checkbook control structure is used, the deed is recorded simply in the name of the LLC. Suppose Lisa's IRA establishes an LLC named 1234 Apple Street LLC to purchase that same property. Title to the property would be recorded as:
1234 Apple Street LLC
The IRA owns the LLC, and the LLC owns the property. Lisa, as manager of the LLC, can sign leases, hire contractors, pay expenses, collect rents, and manage the property without waiting for custodian approval. Because the LLC has only one member, it is generally treated as a disregarded entity for federal income tax purposes, meaning no separate federal income tax return is required for the LLC.
How to Buy Real Estate Through a Self-Directed IRA
Regardless of which structure is used, the investment process follows the same general steps. The first step is funding the Self-Directed IRA through a transfer, rollover, or contribution. Once funded, the investor identifies a property and performs the necessary due diligence.
With a full-service Self-Directed IRA, the custodian executes the purchase on behalf of the IRA. With a checkbook control structure, the LLC completes the purchase directly. The most important concept to remember is that the retirement account, not the individual investor, is making the investment. All purchase funds must come from the IRA or IRA-owned LLC, and all income and expenses must flow back through that same structure.
Which Structure Is Right for You?
Both the full-service Self-Directed IRA and the Self-Directed IRA LLC are effective tools for investors seeking to use retirement funds to acquire real estate. Neither is inherently better than the other.
For investors seeking simplicity, lower startup costs, and greater custodian involvement, the traditional full-service Self-Directed IRA is often the right choice. For investors seeking maximum flexibility, enhanced privacy, limited liability protection, and direct control over their investments, the IRA LLC structure generally provides significant advantages.
The decision ultimately comes down to how actively the investor intends to participate in real estate investing. Regardless of the structure selected, both approaches allow retirement investors to diversify beyond traditional securities and use tax-advantaged retirement funds to build long-term wealth through real estate ownership.
IRA Financial vs Alto IRA
When you want to invest your retirement funds in alternative assets, such as real estate, private equity, or cryptocurrency, Self-Directed IRAs (SDIRAs) give you that flexibility. Two notable players are IRA Financial and Alto IRA. While both facilitate alternative investing, they have different philosophies, pricing models, strengths, and trade-offs.
Below is a side-by-side comparison across four critical areas: fees and pricing, product options, technology, and reputation.
Pricing & Fees: Transparent, Flat, and Investor-Friendly
Fees often determine whether a provider is advantageous for your strategy, especially when you have many transactions or your account grows. Alto IRA charges a quarterly Account Fee based on Total Invested Capital, plus separate service fees, while IRA Financial uses a flat annual fee.
IRA Financial | Alto IRA | |
Setup Fee | $0 | $0 |
Annual Fee | $495 | $400 |
Asset Value Fee | $0 | $0 |
Investment Fee | $0 | $300 |
Roth Conversion Fee | $0 | $50 |
1 Year Total Cost | $495 | $750 |
Pricing pulled from company website, as of the article publish date, based on 4 investments with a $200K total balance.
IRA Financial:
- IRA Financial offers flat, transparent annual fees starting at $495/year for a Self-Directed IRA, with other plans available starting as low as $100 annually.
- No asset-based fees, no transaction fees, and no hidden charges; what you see is what you pay.
- Their IRAfi Crypto platform offers low trading fees for buying, selling, and trading crypto through the integrated app.
Alto IRA:
- Quarterly Account Fee based on Total Invested Capital: $0 under $0.01, $37.50/quarter under $30,000, $100/quarter at $30,000 and above
- Investment processing fee varies by source: $0 through Alto Marketplace, $10 through an Integrated Partner, $75 for a Private investment
- $50 Roth conversion fee, $50 account closure fee
Summary
IRA Financial's flat-fee structure offers cost predictability, ideal for investors managing real estate, LLCs, or multiple deals. Alto IRA's costs vary depending on how each investment is sourced, Marketplace deals carry no processing fee, while private investments add $75 each, so the total cost depends heavily on where your deals come from.
Winner: IRA Financial.
A single flat annual fee that doesn't change based on how or where you source each investment.
Investment Flexibility & Product Options
When choosing a Self-Directed IRA, flexibility is everything. Both IRA Financial and Alto IRA give investors access to alternative assets, but the range and control differ.
IRA Financial | Alto IRA | |
Account Type | ||
Self-Directed IRA | ||
Solo 401(k) | ||
HSA | ||
Checkbook Control | ||
ROBS Structure | ||
Platform & Investments | ||
Crypto Platform | ||
Stock Trading | ||
Compliance & Protection | ||
In-House Compliance & Tax Services | ||
IRS Audit Protection |
IRA Financial:
- Offers all the traditional SDIRA investments, including real estate, private lending, startups, precious metals, as well as direct crypto investing.
- Integrated platform for crypto, checkbook control, real estate, and more under one roof.
- Stock, ETF, bond, and options trading powered by Interactive Brokers - available as a $100/year add-on, fully integrated inside your IRA Financial account.
- Advanced structures like Solo 401(k) plans, SEP & SIMPLE IRAs, HSA & Coverdell accounts, and ROBS structures for business funding.
- IRA Compliance Shield ($299/year): in-house audit protection, tax consultation, deal reviews, prohibited transaction pre-clearance, and UBIT/UDFI modeling.
Alto IRA:
- Offers access to private equity, startups, and crypto through its Marketplace and Integrated Partners
- Checkbook IRA LLC isn't part of Alto's offering; most investments run directly through Alto's platform without one
- Account types limited to Traditional, Roth, and SEP IRAs, no SIMPLE, HSA, Coverdell, or ROBS
Summary
IRA Financial provides full control and unlimited investment choices through its LLC or trust structure, making it ideal for hands-on investors. Alto IRA streamlines access to curated investments through its Marketplace and partners, but doesn't offer the same built-in checkbook control or account variety.
Winner: IRA Financial
Broader account types and built-in checkbook control for investors who want full control of their IRA assets.
Technology: Built for the Modern Investor
Technology defines how easily investors can manage their self-directed accounts. Both IRA Financial and Alto IRA use digital tools to simplify alternative investing, but their approaches reflect different priorities.
IRA Financial:
- Newly-updated mobile app and account dashboard with clean UI/UX and modern functionality.
- Offers a fully digital on-boarding experience, automated compliance, and secure document storage.
- In-house crypto trading, real-time dashboards, and checkbook control in a single portal.
Alto IRA:
- Clean, user-friendly online platform with guided investment workflows
- Mobile app available on iOS and Android, though Android users report more reliability issues than iOS users
- Focused on private market investments such as private equity, private credit, real estate, and infrastructure
Summary
IRA Financial leads in automation and consistency, offering crypto trading, checkbook control, and compliance tools all within one integrated platform. Alto IRA's interface is modern and intuitive, but its product scope is narrower, focused on private market investments through its Marketplace and partners rather than an all-in-one platform.
Winner: IRA Financial.
A single integrated platform where crypto trading, checkbook control, and compliance all live within one account experience.
Reputation & Customer Reviews
Reputation can signal reliability, especially when dealing with retirement assets. Alto IRA has historically held a strong reputation, but a recent event has significantly changed its standing.
IRA Financial | Alto IRA | |
Trustpilot | 4.8 / 5 | 2.9 / 5 |
4.3 / 5 | 2.7 / 5 |
IRA Financial:
- Strong reputation for fast account setup, responsive customer service, and straightforward pricing.
- Over 3,000 5-star reviews across Google, Trustpilot, and other platforms.
- Founded by tax attorney Adam Bergman, who educates investors via weekly videos, podcasts, and blog articles.
Alto IRA:
- Founded in 2018
- Holds a 2.9/5 rating on Trustpilot across more than 1,300 reviews
- Offers customer support by phone and email during business hours
Summary
Both platforms maintain visible customer feedback across major review sites, but IRA Financial's ratings remain consistently strong across a much larger volume of reviews.
Winner: IRA Financial.
A consistently strong reputation without a recent, disruptive platform transition affecting existing account holders.
The Bottom Line: Why IRA Financial Is the Smarter Choice
Both IRA Financial and Alto IRA have made alternative investing more accessible, but they serve different investor types. Alto IRA's low entry cost and guided marketplace still appeal to newer or smaller investors, but its cost structure varies by investment source, and its recent crypto custody transition has created real disruption for existing crypto account holders.
For investors who want predictable flat-fee pricing, full account flexibility, and a platform not currently navigating a disruptive custody change, IRA Financial offers more.
Book a free call with a self-directed retirement specialist
- Review your self-directed retirement options
- Learn about investing in alternative assets
- Get all of your questions answered
How to Close a Real Estate IRA Purchase: A Step-by-Step Compliance Checklist
A Real Estate IRA closing follows standard real estate procedures, but ownership, funding flow, and signatures must reflect the IRA, not you personally.
Most closing problems come from using personal defaults where IRA-specific rules apply.
Key Takeaways:
- How a Real Estate IRA closing differs from a personal purchase
- The correct title vesting language and why it matters
- How to handle earnest money, escrow, and closing costs from the IRA
- Insurance requirements that are frequently overlooked
- A closing checklist you can use immediately
How a Real Estate IRA Closing Differs From a Personal Closing
A Real Estate IRA purchase uses the same infrastructure as any other closing: agents, escrow, title, and lenders where applicable. What changes is how ownership and control are structured throughout the transaction.
Ownership sits with the IRA, not with you. That means your role at closing is limited to signing as an authorized representative rather than as the buyer. That distinction affects how contracts are written, where funds originate, who signs documents, and how insurance is issued. Every item on this checklist ties back to that structure.
Step 1: Confirm the Correct Title Vesting Language
Title must reflect IRA ownership exactly as required by your custodian. The standard vesting format is:
[Custodian Name] FBO [Your Name] IRA #[Account Number]
Common title errors to avoid include listing your personal name only, using an LLC or trust not owned by the IRA, and omitting "FBO" or the IRA account number. Incorrect vesting creates correction work and can result in invalid ownership records that complicate future transactions.
Step 2: Structure the Purchase Contract Correctly
The purchase agreement should identify the IRA as the buyer, not you personally. The buyer name in the contract must match the IRA vesting language exactly, the earnest money clause must specify IRA funds, and the signature block must reflect your role as an authorized signer rather than the owner.
Signature format: [Your Name], Authorized Signer for [Custodian Name] FBO [Your Name] IRA
Contracts signed personally without reference to the IRA create assignment issues later that can be difficult and costly to unwind.
Step 3: Handle Earnest Money From the IRA
Earnest money must originate from the IRA account. Acceptable methods include a custodian-issued check, a custodian wire, or a Checkbook IRA LLC account if the structure is set up correctly.
What is not acceptable: a personal check, business account funds, or any form of reimbursement after closing. Using personal funds, even temporarily, creates prohibited transaction risk that can jeopardize the entire account. This is one of the most common mistakes I see in Real Estate IRA transactions, and it is entirely avoidable with early planning.
Step 4: Coordinate Escrow With the IRA Custodian
Escrow needs to be set up with the IRA as the buyer from the start. That means the IRA must be listed as the buyer on escrow instructions, the custodian contact must be included early in the process, and the funding timeline must be aligned with custodian processing times.
The most common friction points are short escrow timelines, last-minute document requests, and wiring instructions issued too late for the custodian to process. Getting escrow and the custodian aligned early in the transaction eliminates most of these delays.
Step 5: Confirm All Funds and Closing Costs Flow From the IRA
All purchase-related costs must be paid by the IRA. That includes the purchase price, closing costs, title fees, and recording fees.
Costs that cannot be paid personally include repairs prior to purchase, inspection fees charged to the buyer, and any post-closing expenses. Mixing personal and IRA funds, even for minor costs, violates the required separation under IRA rules and can trigger a prohibited transaction.
Step 6: Issue Insurance in the IRA's Name
Insurance is one of the most frequently overlooked compliance points in a Real Estate IRA closing. The insured party on the policy must match the IRA title, no personal name should be listed as the owner, and the loss payee must be structured per custodian requirements.
Common mistakes include policies issued in the personal name, the IRA listed only as an additional interest rather than the insured owner, and incorrect mailing or billing setup. Insurance errors delay funding because custodians will not release closing funds until the policy correctly names the IRA as the insured owner. That gap can leave the property temporarily uncovered while corrections are made.
Step 7: Verify Who Signs What at Closing
| Document | Signer |
|---|---|
| Purchase agreement | Authorized signer |
| Escrow instructions | Authorized signer |
| Loan documents (if allowed) | IRA custodian |
| Deed | Seller only |
Signature authority rests with you as the IRA's authorized representative. Ownership remains with the IRA itself. Those are two different things and keeping them straight at closing is essential.
Step 8: Post-Closing Checks to Confirm Compliance
After recording, confirm that the deed is recorded in the correct IRA name, the insurance policy is active and correctly issued, the custodian has received the final settlement statement, and rent or income instructions direct all payments to the IRA account rather than to you personally.
Book a free call with a self-directed retirement specialist
- Review your self-directed retirement options
- Learn about investing in alternative assets
- Get all of your questions answered
Common Real Estate IRA Closing Mistakes
Nearly all closing mistakes come from handling the deal like a personal purchase rather than an IRA-owned transaction. The issues that appear most often are:
- Personal earnest money used to speed up closing
- Title issued in personal name "temporarily" with plans to correct later
- Insurance issued incorrectly in the owner's personal name
- Escrow unaware that the buyer is an IRA
- Incorrect signature blocks that reference you as the buyer rather than an authorized signer
Temporary workarounds that seem harmless in the moment can create prohibited transaction exposure that is far more difficult to resolve after the fact.
Read More: The Prohibited Transaction Minefield: Rules to Keep Your Real Estate IRA Compliant
How to Run a Real Estate IRA Closing in 2026
The single most important thing you can do is treat the custodian as part of the transaction team from the beginning, not as a back-office function you loop in at the end.
Send the contract draft to the custodian before signing. Confirm vesting language in writing before going under contract. Fund earnest money early. Loop escrow and insurance together so both are aligned on the IRA structure. Recheck title before recording to confirm nothing slipped through as personal ownership.
A Closing Checklist You Can Use Immediately
Before signing final documents, confirm each of the following:
- Buyer name on all documents matches IRA vesting language exactly
- All funds, including earnest money and closing costs, originate from the IRA
- Insurance policy names the IRA as the insured owner
- All signatures reflect authorized signer authority, not personal ownership
- Custodian has received and confirmed final documents
Real estate is one of the most powerful assets you can hold inside a Self-Directed IRA. It can generate tax-free rental income, appreciate without annual capital gains consequences, and eventually be distributed as part of a broader retirement strategy. But that potential only holds if the transaction is structured correctly from the first contract to the final recording. The checklist in this guide is not a formality. It is the difference between a clean transaction and one that requires corrections, penalties, or worse.
The Self-Employed Tax-Free Empire: How to Bundle Your Way to Tax-Free Millions
The tax code is often portrayed as the enemy of the self-employed. In reality, it is written in their favor. W-2 employees are largely limited to whatever retirement plan their employer offers. Self-employed individuals, freelancers, consultants, and 1099 contractors have access to a suite of retirement tools that can shelter far more income, offer far more investment flexibility, and generate far more tax-free wealth than anything available through a corporate plan.
The strategy is straightforward: bundle a Solo 401(k), a Self-Directed Roth IRA, a Health Savings Account, and a Coverdell ESA. Each account solves a different tax problem. Together, they create a structure where a significant portion of your business income can grow and ultimately be distributed without ever being taxed again.
Key Takeaways:
- Why the Solo 401(k) is the most powerful retirement account available to the self-employed
- How the Mega Backdoor Roth moves up to $72,000 annually into a tax-free environment
- Why the Self-Directed Roth IRA is the long-term wealth multiplier
- How the HSA functions as a stealth retirement account with triple tax advantages
- How the Coverdell ESA extends tax-free growth to education funding
The Solo 401(k): Your Primary Engine for Tax Reduction
The Solo 401(k) is the cornerstone of any self-employed retirement strategy. If you have a business with no full-time employees other than a spouse, this plan allows you to contribute in two capacities simultaneously, as both the employee and the employer, creating a level of annual tax sheltering that no other account type can match.
2026 contribution limits
| Age | Total Annual Limit |
|---|---|
| Under 50 | $72,000 |
| Age 50 to 59 | $80,000 (includes $8,000 catch-up) |
| Age 60 to 63 | $83,250 (SECURE 2.0 enhanced catch-up of $11,250) |
The two contribution categories work like this:
- Employee deferrals: Up to $24,500, which can go into a Traditional pre-tax or Roth after-tax account
- Employer contributions: Your business can contribute up to 25% of W-2 compensation or approximately 20% of net self-employment income for sole proprietors and single-member LLCs
For a consultant earning $250,000 in net self-employment income, this combination can shelter over $70,000 from federal taxation in a single year. A SEP IRA on the same income would allow only around $45,000. The difference is the employee deferral, which exists only in a 401(k) structure.
IRA Financial's Solo 401(k) supports both traditional asset classes and alternative investments including private equity, crypto, precious metals, and private lending, all under one flat annual fee with no asset-based charges.
The Participant Loan: Tax-Free Access to Your Capital
One of the most underused features of the Solo 401(k) is the plan loan. You can borrow up to 50% of your account value or $50,000, whichever is less, without triggering taxes or penalties. The loan must be repaid within five years with at least quarterly payments, and the interest rate is typically Prime plus 1%.
What makes this compelling for self-employed investors is that the interest you pay goes directly back into your own account rather than to a bank. In a year where cash flow is tight or a business opportunity requires quick capital, the Solo 401(k) loan provides liquidity without the tax consequences of a withdrawal.
Checkbook Control: Moving at the Speed of Business
IRA Financial's Solo 401(k) plans include checkbook control, meaning your plan trust maintains a dedicated bank account that you control as trustee. When an investment opportunity appears, whether a private placement, a startup equity position, or a crypto purchase, you write a check or wire funds directly from the account. No custodian approval, no processing delay.
For self-employed investors who are already accustomed to making fast business decisions, this level of control over retirement capital feels natural. For those accustomed to waiting days for a brokerage to process a trade, it is a significant shift in how quickly capital can be deployed.
If real estate is part of your investment strategy, IRA Financial's Solo 401(k) also includes a specific tax advantage over IRAs on leveraged property. For a detailed breakdown of that benefit and the full real estate bundled strategy, see our guide to The Real Estate Investor's Tax-Free Retirement Bundled Solution.
The Mega Backdoor Roth: Moving $72,000 Into a Tax-Free Environment
For self-employed investors who want to maximize tax-free accumulation, the Mega Backdoor Roth is the most powerful strategy available inside a Solo 401(k).
Standard Roth deferrals are capped at $24,500. The Mega Backdoor strategy allows you to make after-tax contributions above that cap, up to the $72,000 combined limit, and immediately convert those after-tax funds into Roth. The result is that a self-employed investor can move up to $72,000 per year into a tax-free Roth environment regardless of income level, something a standard Roth IRA cannot accomplish due to income limits and contribution caps.
The plan document must explicitly allow after-tax contributions and in-plan Roth conversions for this strategy to work. IRA Financial's Solo 401(k) plan documents include both provisions by default.
Book a free call with a self-directed retirement specialist
- Review your self-directed retirement options
- Learn about investing in alternative assets
- Get all of your questions answered
The Self-Directed Roth IRA: The Long-Term Wealth Multiplier
Even with a Solo 401(k), a Self-Directed Roth IRA plays a distinct and important role in the bundled strategy. The Solo 401(k) is the primary vehicle for sheltering current-year income. The Roth IRA is the long-term vehicle for compounding wealth that will never be taxed again.
2026 limits and income rules
- Contribution limit: $7,500, or $8,600 for those age 50 and older
- Phase-out for married filing jointly: $242,000 to $252,000
- Phase-out for single filers: $153,000 to $168,000
For investors above the income limits, the Backdoor Roth IRA remains fully legal in 2026. A non-deductible contribution to a Traditional IRA is immediately converted to a Roth, bypassing the income cap entirely. IRA Financial's tax team works through the pro-rata rules with clients to ensure the conversion is handled correctly.
Why hold both a Solo 401(k) and a Roth IRA?
The two accounts serve different purposes and have different distribution rules. The Solo 401(k) generates the largest current-year deduction. The Roth IRA builds wealth that is never subject to Required Minimum Distributions, can be passed to heirs tax-free, and can have contributions withdrawn at any time without penalty since they were already taxed.
Holding both means you can direct high-growth investments with long time horizons into the Roth and use the Solo 401(k) for current-year tax reduction. That separation produces better outcomes than relying on either account alone.
The HSA: Triple Tax Advantages Most Investors Ignore
The Health Savings Account is the most overlooked account in the self-employed toolkit. Used correctly, it functions as a stealth retirement account with a tax structure that no other account matches.
Eligibility
To contribute to an HSA you must be enrolled in a High-Deductible Health Plan (HDHP), not enrolled in Medicare, and not claimed as a dependent. For 2026, the minimum HDHP deductible is $1,700 for individual coverage and $3,400 for family coverage.
2026 contribution limits
- Individual coverage: $4,400
- Family coverage: $8,750
- Catch-up (age 55 and older): an additional $1,000
The triple tax advantage
- Contributions reduce your taxable income in the year they are made
- Investments grow tax-free inside the account
- Withdrawals for qualified medical expenses are completely tax-free
No other account in the tax code offers all three simultaneously. A Traditional IRA gives you one and two. A Roth IRA gives you two and three. The HSA gives you all three at once.
Read more: How a Self-Directed HSA Can Double as a Stealth Retirement Account
The delayed reimbursement strategy
The most powerful way to use an HSA as a retirement vehicle is to pay medical expenses out of pocket, save the receipts, invest the HSA balance for long-term growth, and reimburse yourself years or even decades later. There is no IRS deadline on reimbursement as long as the expense occurred after the account was opened and you have documentation. That means your HSA can compound tax-free for years before you ever touch it.
IRA Financial's HSA platform allows the account to hold alternative investments alongside traditional securities, and includes a dedicated debit card for immediate medical expense payments. That combination, investment flexibility plus spending convenience, is not available from standard HSA providers.
The Coverdell ESA: Extending Tax-Free Growth to Education
The Coverdell Education Savings Account rounds out the bundled strategy by extending tax-free compounding to education funding. Contributions of up to $2,000 per year per child are made with after-tax dollars, but all earnings and withdrawals are tax-free when used for qualified education expenses.
The Coverdell's advantage over a 529 plan is its flexibility. Funds can be used for K-12 expenses including private school tuition, tutoring, books, and educational technology, not just college costs. For self-employed investors with school-age children paying private school tuition, this distinction matters.
At IRA Financial, the Coverdell is set up with full checkbook control, allowing it to participate in investment deals alongside your other accounts. A Coverdell can hold a small equity position in the same private deal as your Solo 401(k), with the gains flowing back into the education account tax-free.
If the beneficiary does not use the funds by age 30, the balance can be rolled to another eligible family member under 30, keeping the tax-free growth within the family rather than triggering a penalty.
Read more: The “Triple-Threat” Education Strategy: 529, Self-Directed Coverdell, and the Trump Account
Final Thoughts
The bundled strategy works because the tax problem facing self-employed investors has multiple dimensions. Current-year income needs to be sheltered. Long-term gains need to grow without tax drag. Healthcare costs need to be managed efficiently. And education funding should not come from after-tax dollars if it does not have to.
The Solo 401(k), Self-Directed Roth IRA, HSA, and Coverdell ESA each address one of those dimensions. Together they create a structure where the self-employed investor keeps a significantly larger portion of what they earn, compounds it without interruption, and eventually accesses it in a way that the IRS has already agreed is tax-free.
The tax code was written with these vehicles in mind. Using them is not a workaround. It is the system working exactly as intended.
